


CB Financial Services walked into its Q3 2026 release with the stock already on a steady upward grind, then added another 3.2% in the first full trading day after the numbers were released. The headline was simple enough. Earnings per share came in just above US$1 with net income a little over US$5.3 million, solid figures for a community bank of this size.
Short term traders appeared to focus on that clean profit result and the roughly 3.8% net interest margin as confirmation of a comfortable story. The real question for you is whether a one day relief rally fully reflects what those profitability and loan quality trends are indicating beneath the surface.
Like the clean net interest margin at CB Financial Services but want more banks with solid profitability profiles and resilient balance sheets in one place? Check out a broader peer set in our list of solid balance sheet and fundamentals stocks (24 results)
Q3 2026 Earnings Summary
- Total Revenue (Q3 2026 vs. Q3 2025): US$16.078 million vs. US$2.159 million (very large year over year increase).
- Net Income (Excl. Extra Items) (Q3 2026 vs. Q3 2025): US$5.327 million vs. a loss of US$5.696 million (swing to profit).
- Basic EPS (Q3 2026 vs. Q3 2025): US$1.0480 vs. a loss of US$1.1426 (sharp improvement per share).
- Net Interest Margin (NIM, Q3 2026 vs. Q3 2025): 3.79% vs. 3.67% (modest uplift in lending spread).
Earnings tell you what happened this quarter, but the cash flowing through CB Financial Services' books is what many valuation focused investors watch most closely.
When you focus on CB Financial Services' cash generation rather than the income statement headlines, the stock could be a mild 12% undervalued.
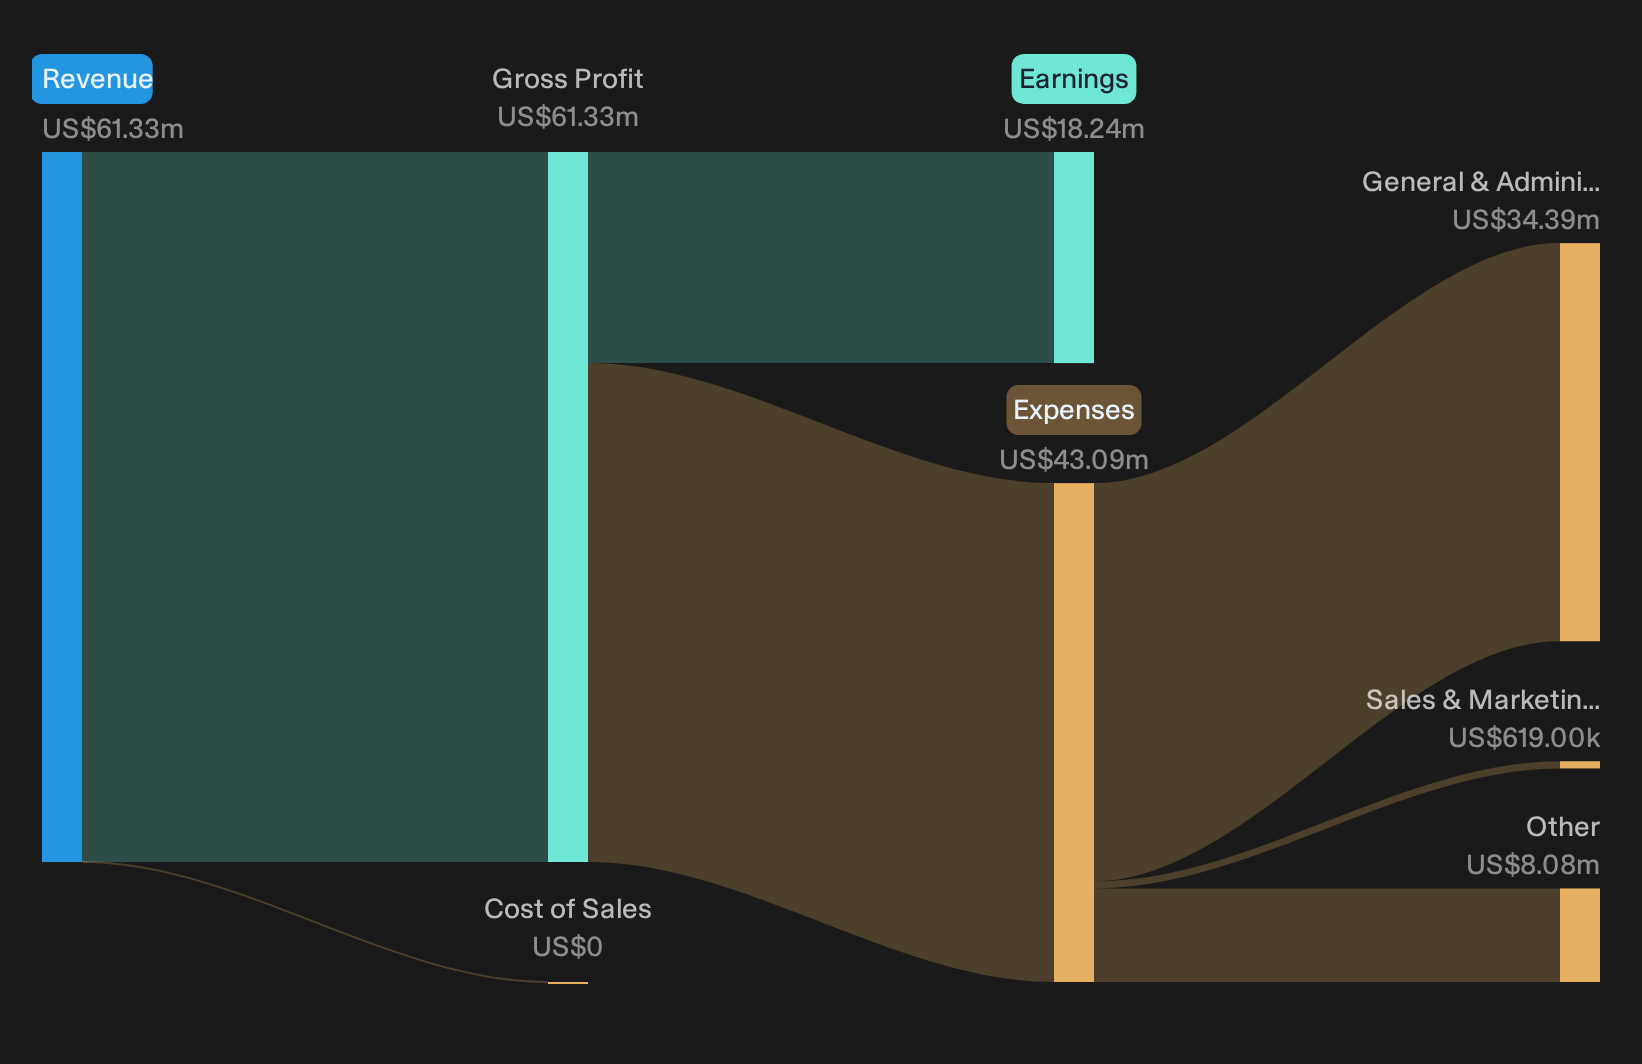
CB Financial Services: Profits Back The Optimists
The bullish story around CB Financial Services as a conservative community bank gets some backing from these figures. Revenue of US$16.078 million sits alongside net income of US$5.327 million, which is a clear move away from last year’s loss. Basic EPS of US$1.0480 turns a prior per share loss into a meaningful profit. A 3.79% net interest margin, slightly higher than the prior 3.67%, fits a thesis that the lending model is still doing its job without obvious strain on spreads.
Profit Swing Helps, But Risks Not Erased
Bearish worries around small bank fragility look less acute when CB Financial Services posts a profit instead of a US$5.696 million loss. The firmer 3.79% net interest margin also suggests lending spreads have not come under visible pressure. That said, a very large move in reported revenue versus Q3 2025 raises questions about one off items, mix shifts, or accounting changes. For anyone worried about credit or rate sensitivity, these results soften the near term alarm but do not remove the need to scrutinize sustainability.
Reveal where the calm Q3 profit swing for CB Financial Services might hide its next real stress test or upside surprise by checking what the street is quietly baking into revenue, margin and EPS, then access the analyst estimates for CB Financial Services
Hunt For Quiet Price Gaps
CB Financial Services just reminded investors how quickly sentiment can firm when profits and margins align. The real opportunity is spotting solid businesses that could be mispriced before consensus fully catches up.
- Company 1 - 42% below our estimate - help large online platforms handle payments as shoppers and riders favor local digital options.
- Company 2 - 15% below our estimate - build electrical and communications infrastructure for data hubs as hyperscale clients secure long term capacity.
- Company 3 - 31% below our estimate - supply chips and a software stack enterprises adopt when AI training shifts to constant production workloads.
Those are three of them. See all 29 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com