


- StandardAero announced that Air Corsica has selected it to deliver LEAP-1A Performance Restoration Shop Visit and related support services for the airline’s Airbus A320neo fleet, provided from StandardAero’s San Antonio, Texas facility.
- The agreement underscores StandardAero’s effort to build deeper LEAP engine coverage by combining full shop visit capability, component repairs and health monitoring into one integrated service offering for an existing customer relationship that began in 2023.
- We will look at how StandardAero's expanded LEAP-1A support for Air Corsica reframes the broader investment narrative around its engine MRO scale.
Scan beyond StandardAero and spot other maintenance and aerospace plays that could benefit from similar contract momentum with our curated list of 21 high quality undiscovered gems in the sector.
StandardAero Investment Narrative Recap
To own StandardAero, you need to believe it can turn its LEAP and CFM programs from margin drags into profitable work while keeping Component Repair Services on a solid footing. The Air Corsica win supports that thesis by adding LEAP-1A volume and validating the San Antonio hub, but on its own looks incremental rather than transformational.
The key near term catalyst is a clean learning curve on LEAP and CFM56 work so that zero margin programs move toward profitability without snarls in parts or labor. The biggest risk remains supply chain strain in castings and forgings, which could prolong low margin work, tie up contract assets and keep free cash flow conversion under pressure.
The most relevant announcement for this story is StandardAero’s progress building LEAP capability in San Antonio as a CFM LEAP Premier MRO provider. The correlation of the first LEAP test cell in November 2024 and the ramp from quick turn shop visits to full Performance Restoration Shop Visits frames today’s Air Corsica contract as part of a broader capacity build out.
For you, that puts execution front and center. More LEAP work only helps if StandardAero can industrialize repairs efficiently, keep technician training on track through its in house program and avoid bottlenecks that delay inductions. Success would support the LEAP revenue ramp investors are watching, while missteps could keep consolidated margins and earnings growth below expectations.
StandardAero's current revenue forecasts point to about 7.5% yearly top line growth, with analysts projecting revenues of US$7.8b and earnings of US$613.4 million by 2029. This implies an earnings increase of roughly US$289.4 million from current earnings of US$324.0 million.
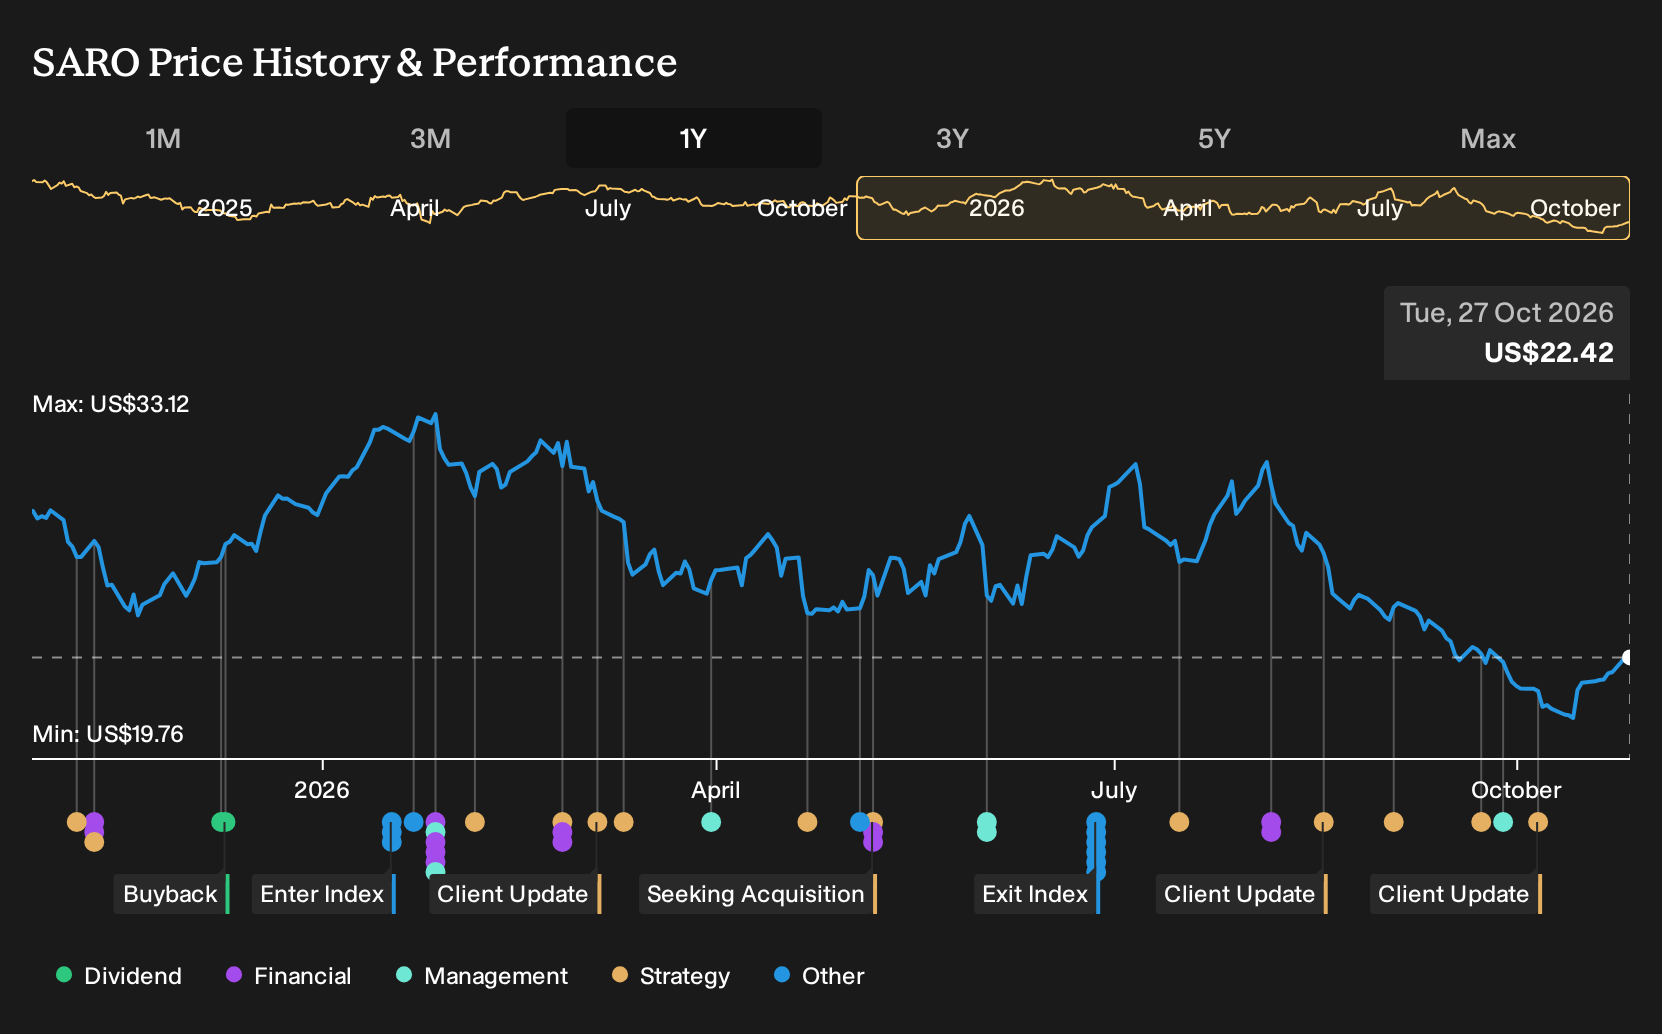
Uncover how StandardAero's fair value indicates a 53% potential upside to its current price that could narrow quickly if execution on LEAP continues to improve.
Exploring Other Perspectives
You might see this Air Corsica contract and focus on LEAP execution risk, yet the most optimistic analysts zoom in on funding firepower instead. Before this news, they were already modeling revenue of US$8.5b and earnings of US$742.2 million by 2029. Use that spread to test your own view of how StandardAero’s story could shift.
Explore 2 other StandardAero fair value estimates, including one that suggests as much as 53% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your StandardAero research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for StandardAero. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate StandardAero's overall financial health at a glance.
Looking For More Ideas Beyond StandardAero?
Once you have a view on StandardAero, it can help to stress test that thesis against other businesses with different balance sheets, cash flow profiles and return drivers using the Simply Wall St Screener.
- For investors who care most about capital strength and staying power, start with a list of solid balance sheet and fundamentals (24 results) that can handle rough patches without leaning too heavily on fresh funding.
- If capital preservation matters more than chasing every swing, focus on a 30 resilient stocks with low risk scores that scores well on stability and avoids the most fragile business models.
- When you want early stage potential backed by hard numbers, scan through a 7 elite penny stocks with strong financials that already show signs of financial discipline instead of just hype.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com