


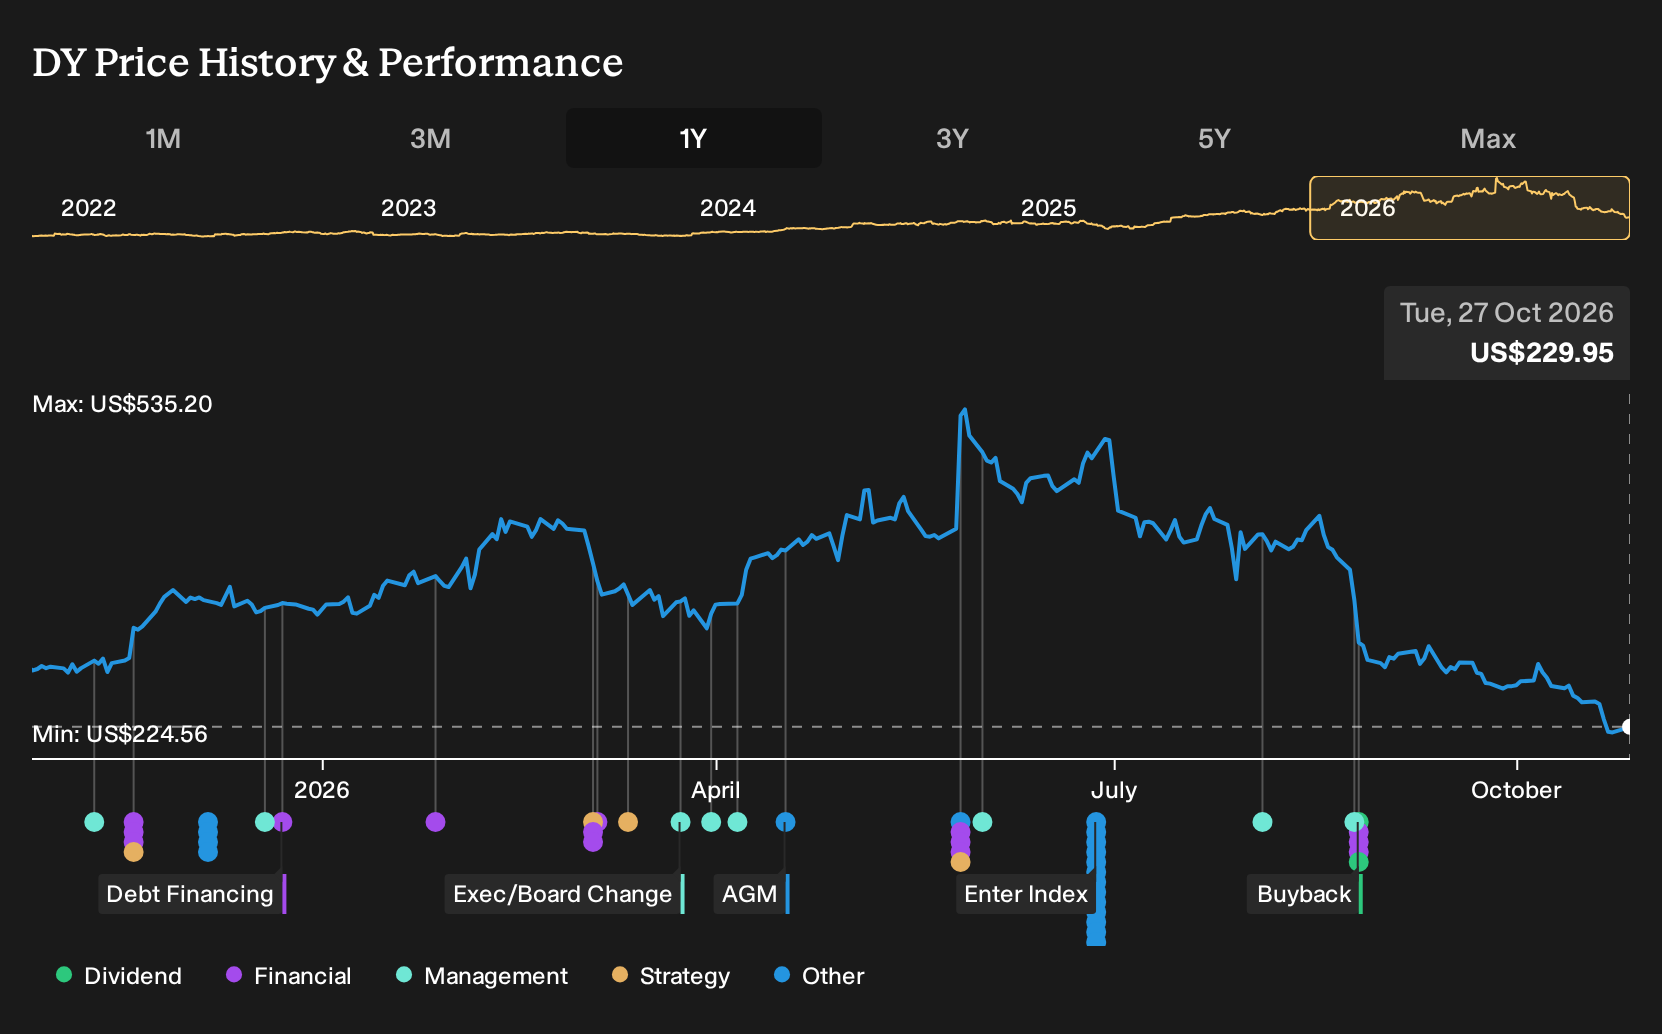
- Dycom Industries has seen a sharp pullback in its share price after a multi year climb, as investors reassess how reliably its current earnings reflect dependence on large telecom and infrastructure contracts with variable timing and work mix.
- The key question now is whether Dycom Industries' earnings base, shaped by a concentrated customer set and long term project pipeline, is durable enough to support the valuation implied by its contract profile and backlog.
- We will now look at how Dycom Industries' investment narrative is affected by fresh concerns around earnings durability and contract timing.
Compare how Dycom Industries stacks up against a curated group of infrastructure focused contractors by scanning the 42 power grid technology and infrastructure stocks for potential alternatives and complements in your portfolio.
Dycom Industries Investment Narrative Recap
To own Dycom Industries here, you need to be comfortable with a story built on long duration fiber and data center programs that convert into steady work rather than perfectly smooth quarterly results. The sharp share pullback has not changed the basic setup. The near term swing factor is how quickly the US$12.2b backlog and more than US$1b of contracted fiber corridors move into active construction.
The biggest operational risk is still customer concentration and project timing. Any pause in fiber to the home build plans, slower BEAD field work, or stretched data center schedules could leave the business absorbing fixed costs on lighter volumes. Labor availability and wage pressure also remain key watchpoints for margins in Communications and Building Systems.
Recent commentary around record quarterly revenue of US$2.01b and nearly 60% first half fiber to the home revenue growth is central to this debate. Those figures show how much Dycom Industries is tied to large scale network rollouts. When work ramps quickly, utilization and earnings can look very strong. When customers rebalance priorities, the reset can be abrupt. This is what the latest pullback is reacting to.
The same update also highlighted adjusted EBITDA margin of 15.7%, strong free cash flow and early BEAD related revenue in the Northeast. For catalysts, investors are effectively watching three things: the pace of converting that US$12.2b backlog, the durability of high teens to low 20s Building Systems margins anchored by data center demand, and how effectively Dycom Industries manages labor and contract mix if customers rephase multi year programs.
Dycom Industries' current analyst narrative points to revenue of US$10.0b and earnings of US$631.4m by 2029, based on assumed yearly revenue growth of 13.3% and an earnings increase of about US$301.8m from current earnings of US$329.6m.
Uncover why Dycom Industries' fair value indicates a 127% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
You can read the Dycom Industries pullback very differently if you focus on BEAD timing. The lowest analysts were already cautious about delays, even while penciling in about US$10.1b of 2029 revenue and US$702.1m of earnings before this news. That is a more pessimistic narrative on timing, not on long term demand. Use this swing to compare several viewpoints and stress test which assumptions feel realistic to you.
Explore 3 other Dycom Industries fair value estimates, including one that suggests it could be worth just $370.92!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Dycom Industries research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Dycom Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Dycom Industries' overall financial health at a glance.
Looking for more investment ideas beyond Dycom Industries?
If the Dycom Industries pullback has you rethinking position sizes or hunting for fresh opportunities, it can help to scan a wider field of potential candidates using the Simply Wall St Screener.
- For investors who want quality on sale, consider starting with a curated set of companies that screen well on both fundamentals and valuation through the 29 high quality undervalued stocks.
- If resilience and balance sheet strength matter most to you, filter for businesses with sturdy finances using the list of solid balance sheet and fundamentals (24 results).
- Income focused investors who care about consistency can scan for yield opportunities screened on payout strength and stability via the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com