


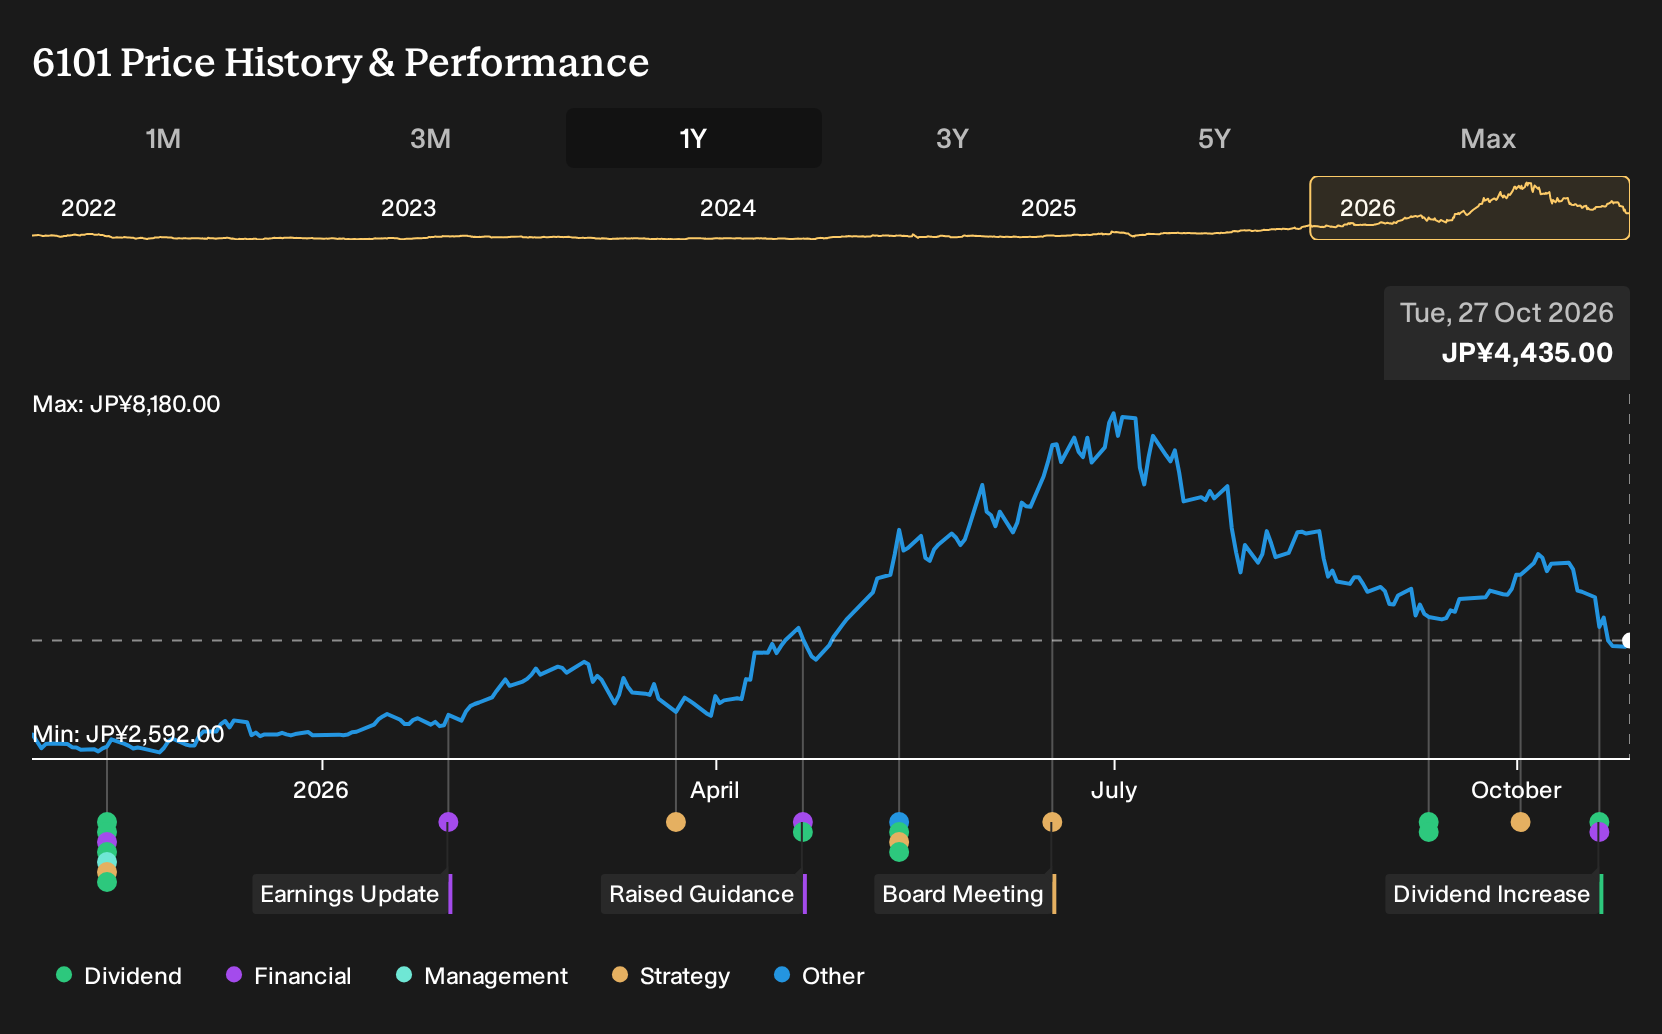
- Tsugami Corporation reported on 20 October 2026 that it revised guidance for the six months to 30 September 2026, now expecting revenue of ¥81,200 million, operating profit of ¥25,200 million and profit attributable to owners of parent of ¥12,300 million, alongside a second quarter dividend forecast of ¥61.00 per share.
- Management linked the higher earnings and dividend guidance to steady execution across regions including China and India, indicating that investors are being offered a clearer view of Tsugami’s current operating strength rather than relying on macro sentiment alone.
- The focus now is on how Tsugami’s upgraded earnings outlook, supported by stronger guidance, may reshape the investment narrative around its execution.
Scan how Tsugami’s upgraded guidance compares with other machinery and industrial plays by reviewing the hand-picked 94 robotics and automation stocks in the same broader theme of automation and precision engineering.
What Is Tsugami's Investment Narrative?
To own Tsugami, you need to believe the precision machine tools cycle still rewards companies that execute cleanly across markets like China and India, manage capital intensive manufacturing with discipline, and keep pricing and mix tight enough to support high quality earnings. The raised earnings and dividend guidance on 20 October 2026 fits that story. It points to operations that are running ahead of what management previously thought likely, and a willingness to return more cash through a higher interim payout.
In the short term, the upgraded outlook and higher JPY 61.00 dividend forecast speak directly to two current catalysts for Tsugami. First, the company is leaning into its record of 53.6% earnings growth over the past year and 16% per year over five years. Second, the stock still carries a history of share price volatility and relies entirely on higher risk borrowing for funding, so the better guidance and payout help but do not fully resolve the core concern that ...
There's only one way to know the right time to buy, sell or hold Tsugami. Head to Simply Wall St's company report for the latest analysis of Tsugami's Fair Value.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Tsugami research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Tsugami. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Tsugami's overall financial health at a glance.
Looking For More Investment Ideas Beyond Tsugami?
Once you have formed a view on Tsugami, it can help to line that up against other opportunities using the Simply Wall St Screener. You get a broader context, and you avoid anchoring only on one industrial story.
- If you want potential value combined with quality fundamentals, start with a curated set of 16 high quality undervalued stocks that share solid cash generation and balance sheet strength.
- For investors who care about resilience first, focus on a 22 resilient stocks with low risk scores that aims to keep downside risk contained while you assess upside potential.
- When the goal is to uncover less crowded opportunities, broaden your watchlist with a 72 high quality undiscovered gems that still screen well on underlying business metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com