


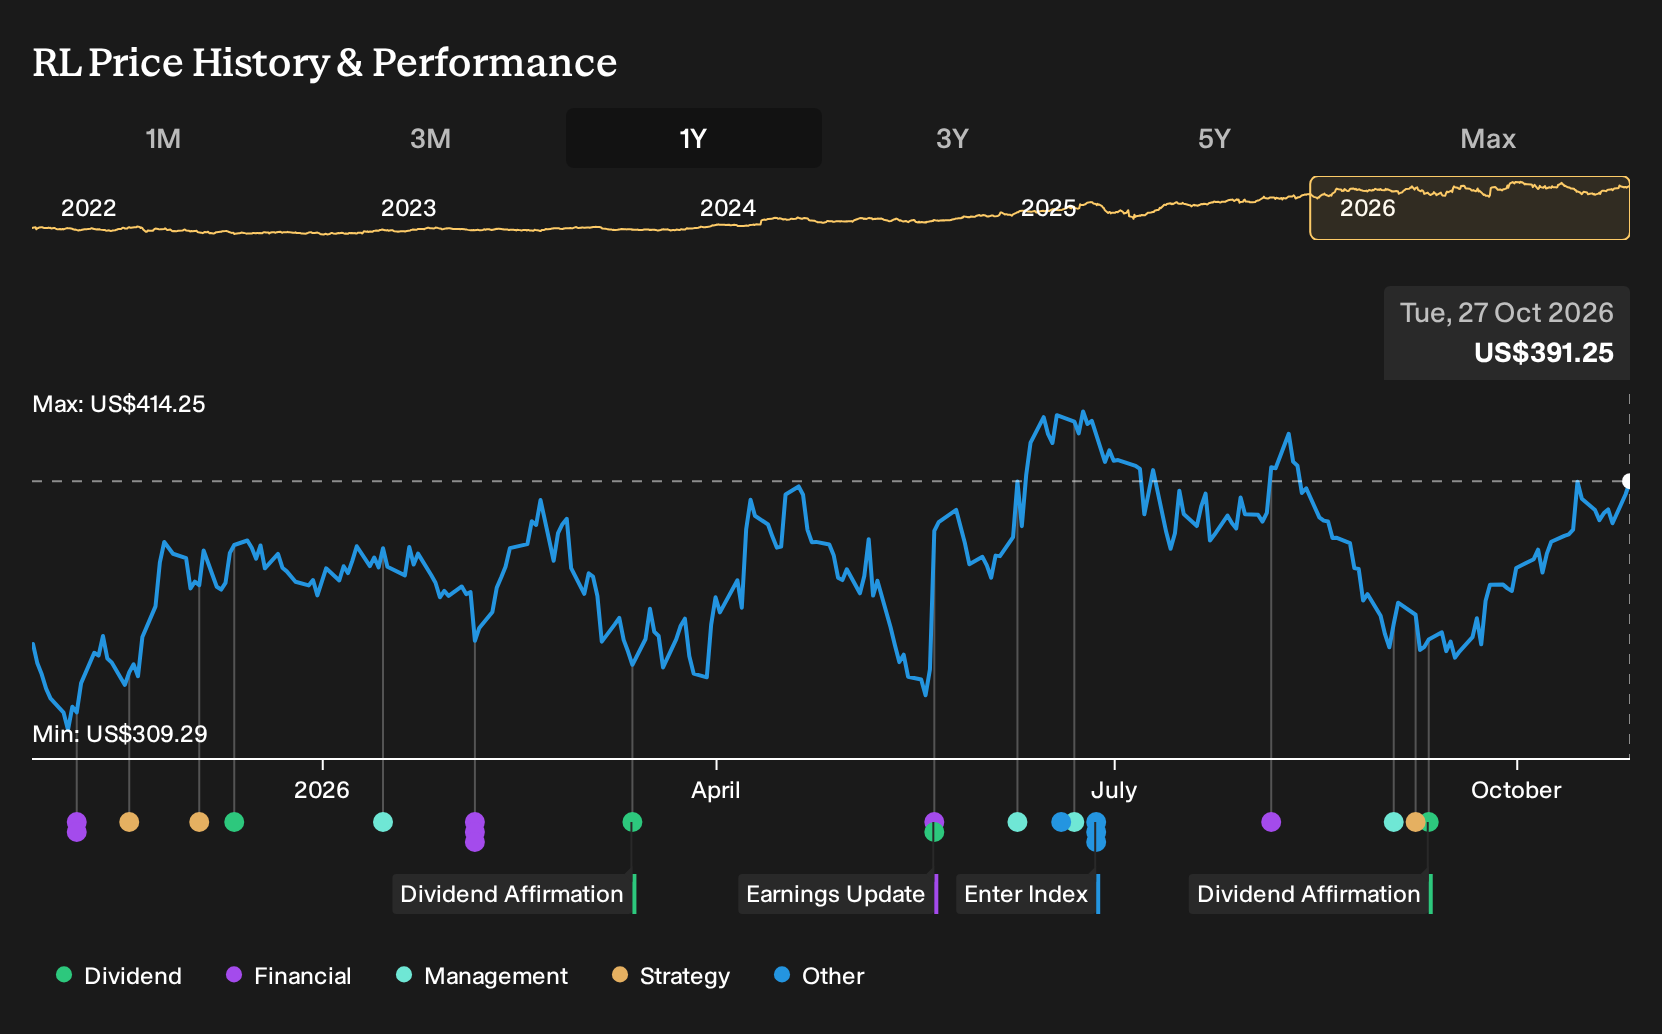
- Ralph Lauren recently attracted fresh attention after an analyst firm highlighted the brand’s progress in elevating its product mix and its plans to report Q2 2027 results on November 5, with forecasts pointing to adjusted EPS of $4.22 and a history of earnings beats.
- The interesting angle is how Ralph Lauren’s focus on full price, younger and higher income shoppers, combined with raised revenue guidance, points directly to the health of its core demand rather than just cost cutting.
- We will look at how Ralph Lauren’s investment narrative is influenced by this earnings momentum and its push toward higher value customers.
Ralph Lauren Investment Narrative Recap
To own Ralph Lauren, you need to believe the brand can keep leaning into higher value customers while holding its line on promotions. That story relies on continued appetite from younger, higher income shoppers and on international and direct to consumer channels doing enough heavy lifting if Europe or wholesale partners soften.
The near term swing factor is execution around the upcoming Q2 2027 print and holiday season, where expectations already bake in earnings momentum. The biggest risk is that consumers push back on higher prices or that more wholesale accounts resemble Harvey Nichols. That outcome would test both margins and the elevation playbook.
The most relevant data point here is the upcoming Q2 2027 earnings on 5 November, where analysts are looking for adjusted EPS of $4.22 after a run of four straight beats. That event puts a spotlight on whether Ralph Lauren can still show healthy demand at full price while keeping inventory and promotions tightly controlled.
Q1 2027 results, where the group raised full year revenue guidance and saw the share price climb 4% on the day, set a relatively high bar for management messaging. Any sign that Europe, wholesale credit risk or consumer pushback on pricing is biting would quickly challenge the current premium P/E and the brand elevation narrative you are underwriting.
What The Analyst Models Mean For Ralph Lauren
Ralph Lauren's current analyst model points to revenues of US$9.7b and earnings of US$1.2b by 2029. This implies 5.0% yearly revenue growth and an earnings increase of about US$217m from current earnings of US$982.9m.
Uncover how Ralph Lauren's fair value indicates a potential 14% upside to its current price before the market fully prices in that gap.
Exploring Other Perspectives
One alternative view fixates on pricing risk. While the Telsey news leans into Ralph Lauren’s full price strength, the most cautious analysts worry discounting creeps back in. They were pencilling in roughly US$9.6b of revenue and about US$1.2b of earnings by 2029, and even that supported a lower 20.2x P/E. Those forecasts and today’s rating shift were set before this week’s headlines. Treat them as moving parts and explore how far your own expectations sit from that more conservative camp.
Explore 3 other Ralph Lauren fair value estimates, including one that suggests as much as 13% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Ralph Lauren research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Ralph Lauren. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ralph Lauren's overall financial health at a glance.
Looking For More Investment Ideas Beyond Ralph Lauren?
Once you have formed a view on Ralph Lauren, it can help to widen the lens and compare it with other businesses that fit your preferred balance of quality, income, and resilience. The Simply Wall St Screener makes that easier by surfacing focused sets of stocks aligned with different goals.
- If you care most about finding companies that look mispriced on fundamentals, start with a curated group of potential value opportunities through the 29 high quality undervalued stocks.
- For investors who prefer steadier cash flows and income potential, consider stocks screened for higher yields and resilience using the 5 dividend fortresses.
- If capital preservation sits near the top of your checklist, filter for businesses with more resilient profiles and lower risk scores via the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com