


Fincantieri (BIT:FCT) is moving its BOOST² program into a new execution phase, shifting advanced robotics, Physical AI, and digital twin tools from pilots into day-to-day shipyard operations across its global network.
Recent trading shows Fincantieri’s share price edging higher in the short term, with a 1-month share price return of 7.47% and a 7-day gain of 3.01%. However, the year-to-date share price return is down 28.31% and the 1-year total shareholder return has declined 44.08%, even after a very large 3-year total shareholder return of about 3.3x and a 5-year total shareholder return of around 2.4x. This context frames the BOOST² rollout as a potential catalyst that investors are weighing against earlier gains and shifting risk perceptions.
Spot emerging shipbuilding and automation stories alongside Fincantieri by scanning our hand picked 94 robotics and automation stocks, which is shaping the next wave of industrial efficiency.Fincantieri’s BOOST² push has arrived just as the share price has pulled back sharply from its multi year gains, while sell side targets and intrinsic estimates remain higher. How far apart is the current price from a reasonable fair value range?
Most Popular Narrative: 45% Undervalued
Fincantieri’s narrative fair value of €22.91 sits well above the last close of €12.66. This puts the BOOST² rollout in a wider re-rating story rather than a short term swing trade.
La sola divisione subacquea (WASS + NextGeo + droni/sistemi integrati) giustifica una valutazione tra 3,6 e 4,5 miliardi di euro.
Considerando la riduzione del debito netto a 756 mln € e la redditività della cantieristica tradizionale, il valore intrinseco del gruppo nevidenzia uno sconto ingiustificato con un upside stimato del 50% rispetto ai prezzi correnti di mercato.
See why 2 investors see Fincantieri as 45% undervalued.
Result: Fair Value of €22.91 (UNDERVALUED)
However, the Fincantieri story could be negatively affected if fixed-price shipyard contracts run into cost inflation or if already busy yards struggle with capacity bottlenecks.
Find out about the key risks to this Fincantieri narrative.
Another View: What Fincantieri’s P/E Ratio Signals
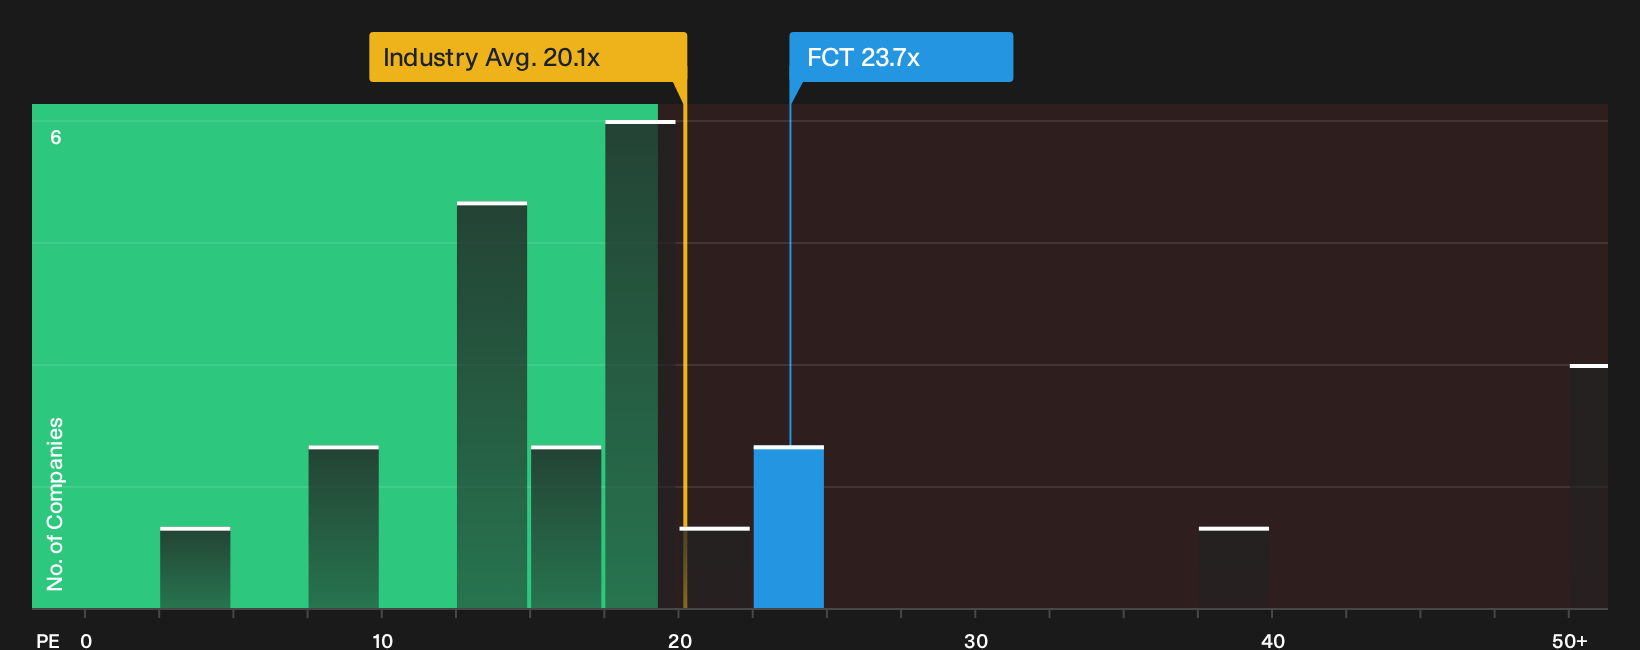
The DCF and narrative work point to upside for Fincantieri, yet the earnings multiple paints a more cautious picture. The shares trade on a P/E of 23.7x, above the European Machinery industry at 20.1x, even though Fincantieri screens as good value against a fair ratio of 31x and a much higher peer average of 62.6x. That gap can look like opportunity to some investors and valuation risk to others, so which side of that trade are you on?
For a closer look at how this earnings multiple stacks up against the market context, including peers and the fair ratio our model points to, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Curious whether the mixed messages here lean more bullish or more cautious for Fincantieri? Act while the data is fresh and weigh both sides of the ledger through 4 key rewards and 1 important warning sign
Looking for more investment ideas beyond Fincantieri?
Do not stop your research with Fincantieri. Cast the net wider and use high quality screeners to surface opportunities that match the way you like to invest.
- Target resilient payers that prioritise income by scanning a group of 224 dividend fortresses with yields that aim to reward patience.
- Hunt for quality at a discount by reviewing a focused set of 195 high quality undervalued stocks that pair fundamentals with pricing that some investors may find appealing.
- Prioritise strength and staying power by filtering for a list of solid balance sheet and fundamentals (207 results) before the crowd catches up.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com