


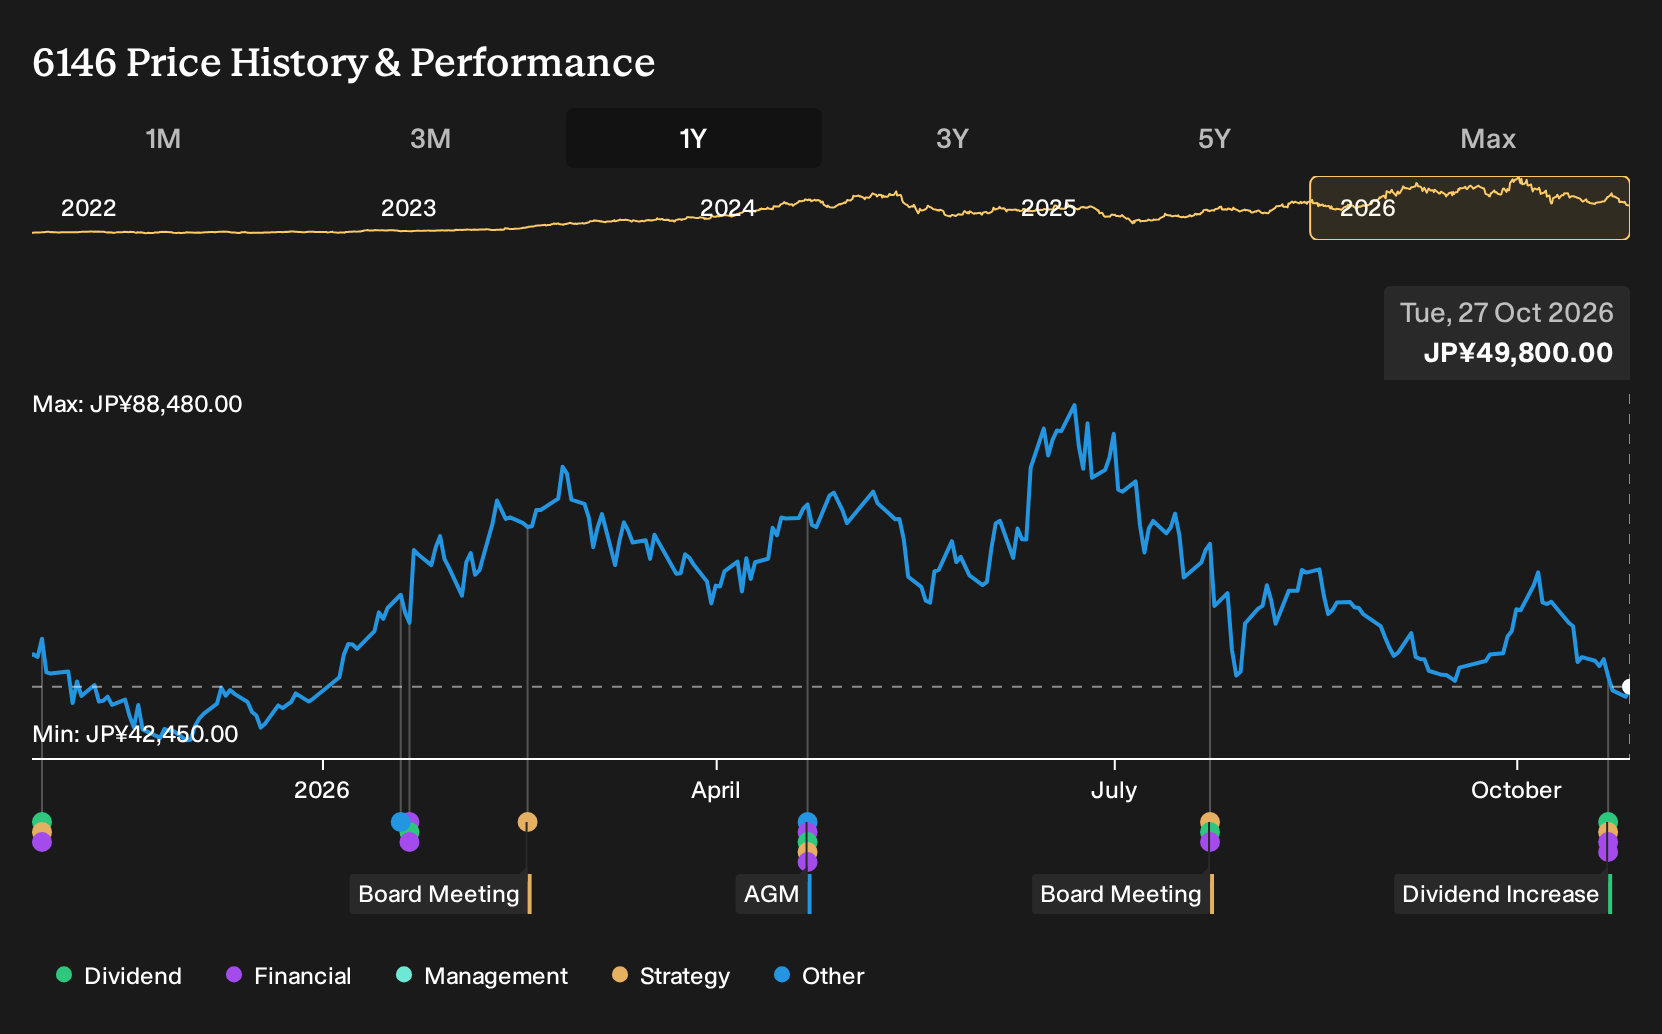
- Disco Corporation reported half-year sales of JPY 257,058 million and net income of JPY 80,366 million, and approved an increased interim dividend of JPY 186 per share for shareholders on record as of September 30, 2026.
- The firm linked the higher dividend to its performance-based payout policy, which ties interim distributions to 25% of consolidated net income for each half-year period, giving investors a direct view of how earnings power feeds into cash returns.
- This article examines how Disco Corporation's investment narrative is influenced by this performance-linked dividend increase and stronger interim profitability.
Compare Scan Disco's latest dividend move with a curated field of similar payout stories by reviewing the 29 dividend fortresses already catching income investors' attention.
What Is Disco's Investment Narrative?
To own Disco, you need to be comfortable with a capital intensive equipment maker whose fortunes are closely tied to semiconductor investment cycles. The revised nine month guidance, with consolidated net sales of ¥389,500 million and net income of ¥121,900 million, signals that current demand for its cutting, grinding, and polishing tools is holding up. The higher interim dividend, explicitly pegged to earnings, reinforces that management is willing to return cash when profitability is strong rather than hoard it.
In the short term, the key swing factor is still customer capex appetite, which Disco itself describes as subject to drastic and rapid shifts. That makes execution on orders, pricing discipline, and capacity planning central, while a rich P/E against the broader JP semiconductor group and a volatile share price add market risk on top of the operational ones.
Yet sitting behind this solid earnings and dividend story is a less obvious vulnerability that only really shows up when you look at ...
There's only one way to know the right time to buy, sell or hold Disco. Head to Simply Wall St's company report for the latest analysis of Disco's Fair Value.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly JPY 25,218 to JPY 77,205 per share, so retail views on Disco differ sharply. Those opinions were formed before the revised nine month guidance and performance linked dividend. Treat this updated outlook as context and explore several contrasting viewpoints before forming your own stance.
Explore another Disco fair value estimate, including one that suggests as much as 49% downside from the current price!
Decide For Yourself
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Disco research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Disco. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Disco's overall financial health at a glance.
Looking For More Ideas Beyond Disco?
If Disco has sharpened your focus on where earnings strength and shareholder returns meet, broaden the opportunity set by running the same test across a wider field of companies using the Simply Wall St Screener.
- For investors who want potential mispricings that line up with solid fundamentals, scan a curated set of 16 high quality undervalued stocks that might warrant a closer look.
- If capital protection is high on your list, concentrate on stability and financial resilience by filtering for 22 resilient stocks with low risk scores that score well on balance sheet and risk checks.
- When you want something off the beaten path, widen your research with 72 high quality undiscovered gems that are already passing strict fundamental filters but are less widely followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com