


What Robert Half’s latest earnings and guidance tell investors
Robert Half (RHI) has put fresh numbers on the table that are catching attention. Third quarter earnings landed higher than a year ago, and management is signaling year-over-year gains again in fourth quarter revenue and earnings per share.
Recent trading has been volatile. Robert Half’s share price is up 53.47% year to date with a 23.96% 7 day share price return ahead of these earnings. The stock fell 6.71% in the latest session as investors digested the new guidance. A 1 year total shareholder return of 56.88% contrasts with a 3 year total shareholder return decline of 34.36% and a 5 year total shareholder return decline of 55.38%, which signals strong short term momentum after a difficult longer period for holders.
See how Robert Half’s rebound compares with other potential opportunities by reviewing our curated 29 high quality undervalued stocks, which highlights companies with solid cash flows and balance sheets alongside potential valuation gaps.
Optimists see Robert Half’s guidance as proof that the earnings trough is behind it. Skeptics see a hot share price and modest growth targets. Which story fits the current valuation better?
Most Popular Narrative: 11% Overvalued
Against a last close of $41.96, the most followed narrative puts Robert Half’s fair value at about $37.89. This frames recent gains as rich compared with those modeled cash flows under a 7.58% discount rate.
Protiviti’s technology consulting business, now roughly one third of segment revenue and delivering record quarterly revenue, is benefiting from client demand for platform and technology modernization, data, cyber and IT infrastructure work. This can help offset weaker risk and compliance work and support segment revenue and operating margin improvement over time.
See why 18 investors see Robert Half as 11% overvalued.
Result: Fair Value of $37.89 (OVERVALUED)
Still, the Robert Half story can change quickly if Protiviti margins stay under pressure or if weak staffing demand keeps earnings compressed for longer.
Find out about the key risks to this Robert Half narrative.
Another View on Robert Half’s value
While the most followed narrative sees Robert Half as about 11% overvalued at $41.96 versus a fair value of $37.89, the Simply Wall St DCF model paints a different picture. On that framework, the shares trade below an estimated future cash flow value of $66.24, which implies a margin of safety instead of excess. Which lens do you trust more when the cash flow story and the market narrative pull in opposite directions?
For a closer look at the moving parts behind that cash flow estimate, including key assumptions on growth, margins and discount rates, Look into how the SWS DCF model arrives at its fair value.
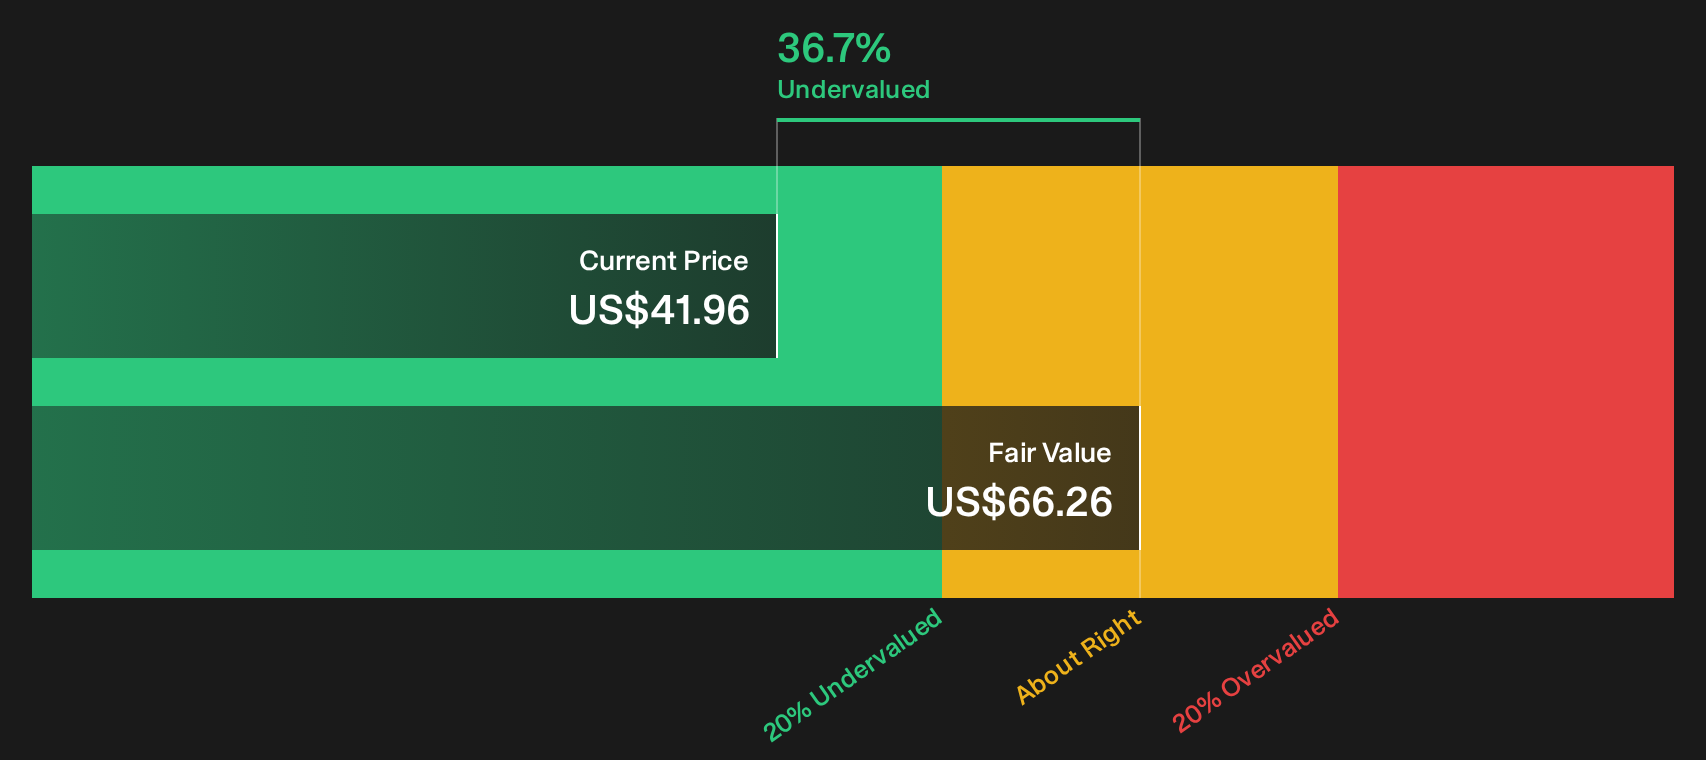
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Robert Half for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed views like these around Robert Half only matter if you put the numbers in context and test them against your own expectations. Take a moment to weigh both the upside potential and the issues that could hold the shares back, then check the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Robert Half?
Robert Half may be front of mind today, but the next opportunity on your list could come from a very different corner of the market.
- Target higher potential payoffs with carefully selected small caps by scanning the 7 elite penny stocks with strong financials that already screen for stronger financial quality.
- Prioritize resilient balance sheets and steady fundamentals by running through the list of solid balance sheet and fundamentals (24 results) that filters for financial strength first.
- Spot opportunities the crowd has not focused on yet by reviewing the 21 high quality undiscovered gems that highlight quality businesses flying under most radars.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com