


What Indutrade’s Latest Earnings Tell You
Indutrade (OM:INDT) gave investors fresh information on 23 October with third quarter and nine month results, as sales and net income for both periods came in above the previous year.
Recent trading tells a mixed story for Indutrade. The share price has climbed 8.28% over the past 90 days and 10.22% year to date, yet the 1 year total shareholder return is slightly negative, while the 3 year figure remains strongly positive.
Scan hand-picked industrials showing similar earnings momentum and financial resilience to Indutrade with our list of solid balance sheet and fundamentals (207 results)
Indutrade appears to be a solid industrial compounder based on recent earnings and a long run of positive 3-year returns, yet the share price has only picked up recently. Is this strength already fully reflected in today’s valuation?
Most Popular Narrative: 8% Undervalued
Indutrade last closed at SEK258.80, while the most followed thesis on the stock places fair value closer to SEK282.25 using a 6.77% discount rate. That gap, together with the recent earnings beat, puts the focus squarely on whether cash flow and the order book can keep supporting that valuation.
High operational cash flow, cash conversion above 130% for multiple quarters and a low and stable net debt to EBITDA ratio, together with an upgraded credit outlook, provide financial capacity for continued M&A and other investments that can influence future revenue growth and earnings.
See why 14 investors see Indutrade as 8% undervalued.
Result: Fair Value of SEK282.25 (UNDERVALUED)
Still, pressure on Technology & Systems Solutions margins and the recent drops in earnings per share in 2025 and Q1 2026 could challenge this Indutrade thesis.
Find out about the key risks to this Indutrade narrative.
Another View: Indutrade Through The P/E Lens
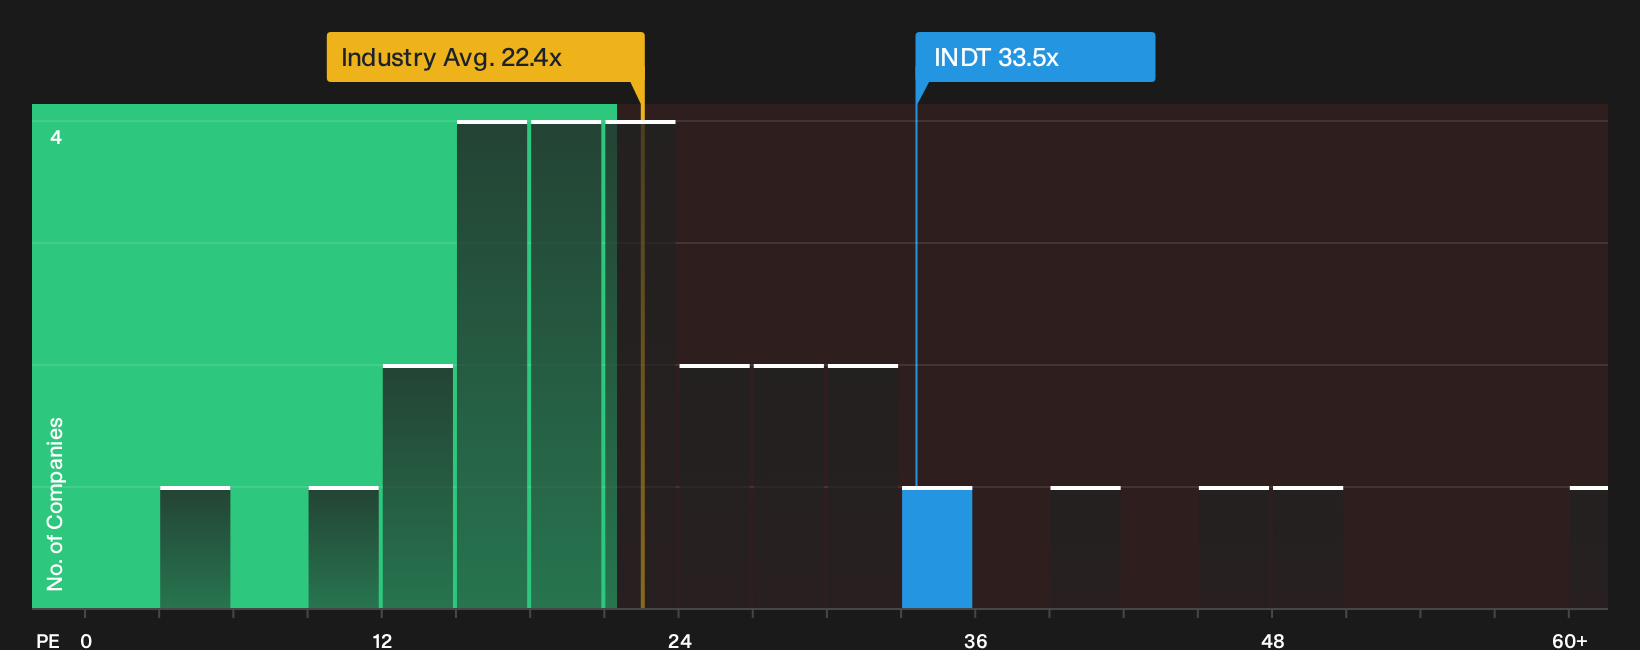
The DCF work points to Indutrade trading below an estimated cash flow value, yet the market’s simple P/E yardstick paints a tighter picture. At 33.5x earnings, the shares sit above a fair ratio of 28.9x, the Swedish Machinery average of 22.1x and a 24.9x peer group.
That kind of premium can signal confidence in Indutrade’s earnings quality, but it also raises the risk that any stumble in profit growth or margins could trigger a sharper reset than the DCF suggests. Which signal do you treat as more important when pricing that risk?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Indutrade story so far. Examine the data yourself, weigh the risks and potential upside, and assess the 3 key rewards.
Looking For More Investment Ideas Beyond Indutrade?
Do not stop your research with Indutrade. Broaden your watchlist now and compare this business against other opportunities that may fit your goals even better.
- Target reliable balance sheets by scanning a list of solid balance sheet and fundamentals (207 results) that highlights companies combining financial strength with steady fundamentals.
- Hunt for potential mispricings by reviewing a 195 high quality undervalued stocks that flags businesses with quality metrics trading below their estimated worth.
- Build your income shortlist by using a 224 dividend fortresses that focuses on stronger yield profiles with an emphasis on resilience.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com