


MACOM Technology Solutions Holdings (MTSI) continues to draw attention after recent share price moves, with the stock last closing at US$255.68. Investors are weighing this semiconductor specialist’s multi-year total returns against more recent pullbacks.
The recent 4.97% one day share price gain comes after a choppy stretch, with the 7 day share price return down 6.36% and the 30 day share price return down 8.21%. At the same time, the year to date share price return of 46.14% and 1 year total shareholder return of 67.48% point to strong longer term momentum that has cooled slightly in the near term as investors reassess MACOM Technology Solutions Holdings’ growth profile and risk appetite.
Compare MACOM Technology Solutions Holdings' recent surge and pullback with a curated group of semiconductor peers in the 55 AI infrastructure stocks to see how other chip players are reacting to similar momentum shifts.
The question is whether MACOM Technology Solutions Holdings at US$255.68 after this surge and pullback is already pricing in its recent progress, or whether patience for a cheaper entry makes more sense based on valuation.
Most Popular Narrative: 15% Undervalued
At a last close of $255.68 against the most followed fair value estimate of $300, the current MACOM Technology Solutions Holdings price sits below that narrative anchor and puts the focus firmly on whether the underlying growth drivers can support that gap.
The secular move to higher data rates in data centers, including 800G and 1.6T, is already translating into record Data Center revenue and strong Q1 2026 growth expectations. This could keep revenue and earnings supported if this demand persists across multiple product cycles.
See why 1 investors see MACOM Technology Solutions Holdings as 15% undervalued.
The central valuation story in that narrative hinges on analysts who sit at the more cautious end of the spectrum yet still arrive at a fair value of $300 using an 11.3% discount rate. Their framework assumes revenue growth of 27.5% a year and profit margins stepping up from 20.7% to 30.7%, with MACOM Technology Solutions Holdings earning $741.0m by around 2029.
This group also assumes the stock would trade on a P/E of 45.1x those projected earnings, which is lower than the current 84.5x but close to the 44.7x benchmark cited for the broader US semiconductor group. In that setup, the upside case does not rely on a premium multiple expanding further; it relies on the business growing into a valuation multiple that is more in line with the sector.
That same narrative flags risk on both execution and macro demand, from data center deployment timing to defense and satellite program schedules, yet still supports a fair value above the current share price. The conclusion is not that the stock is without risk; it is that even a more measured analyst cohort ties their cautious fair value back to assumptions that leave room between $255.68 and $300.
Result: Fair Value of $300 (UNDERVALUED)
Still, the fair value story around MACOM Technology Solutions Holdings can break if heavy data center spending slows or if new fabs and R&D capacity end up underused.
Find out about the key risks to this MACOM Technology Solutions Holdings narrative.
Another View: What MACOM’s P/E Is Telling You
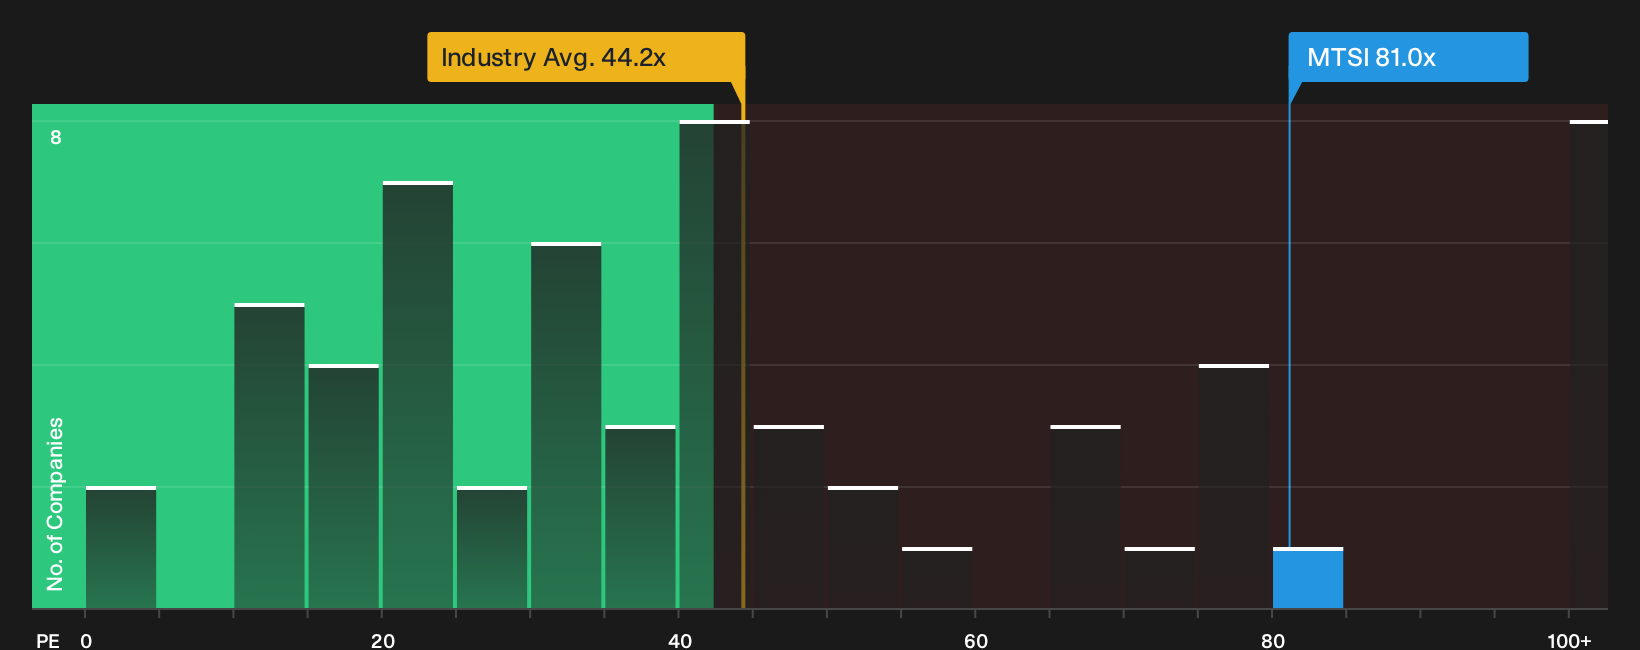
Fair value work around $300 leans on long range forecasts. The current P/E of 81x tells a different story when set against the US semiconductor sector at 44.2x and a fair ratio of 39.1x, which points to richer pricing and less room for mishaps if growth expectations ease.
That gap leaves a simple question for MACOM Technology Solutions Holdings investors. Is this premium a comfort or a concern at $255.68, knowing the valuation could drift closer to the fair ratio if sentiment cools?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed tone in this MACOM Technology Solutions Holdings story leaves you on the fence, consider taking prompt action to weigh both sides and build your own view using the 3 key rewards and 2 important warning signs.
Looking for more MACOM Technology Solutions Holdings sized ideas?
Do not stop your research at MACOM Technology Solutions Holdings. Broaden your watchlist with focused stock ideas sourced from curated Simply Wall Street screeners built around clear fundamentals.
- Target quality at a discount by reviewing a curated 29 high quality undervalued stocks that filters for strong fundamentals and support from both earnings and balance sheets.
- Prioritise resilience by working through a 30 resilient stocks with low risk scores that highlights companies with sturdier profiles when conditions or sentiment become less forgiving.
- Get ahead of the crowd by scanning a 21 high quality undiscovered gems that surfaces under-followed businesses with solid numbers before attention fully arrives.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com