


Innodata has delivered a very large 3 year share price gain, even as the stock has recently given back ground and come under fresh scrutiny. With the price at US$44.74 after sharp short term declines and an investigation related to workforce reductions, the open question is whether that level is supported by the company’s earnings power.
- Innodata is up roughly 7x over the past 3 years, which puts a lot of weight on the idea that its profit stream can ultimately justify such a move.
- Recent layoffs in India and the Philippines and a new AI data partnership may reshape both Innodata’s cost base and future revenue mix, which can feed directly into how durable its earnings profile looks.
- There is a second opinion on Innodata worth weighing. See what analysts think Innodata's shares could be worth.
The issue now is whether Innodata’s current valuation is adequately explained by what the business is earning today and what those earnings suggest about its longer term potential.
If you want to test the same earnings question across a broader set of AI related plays rather than just Innodata, compare it against 38 AI small caps.
Is Innodata Getting Expensive on Earnings?
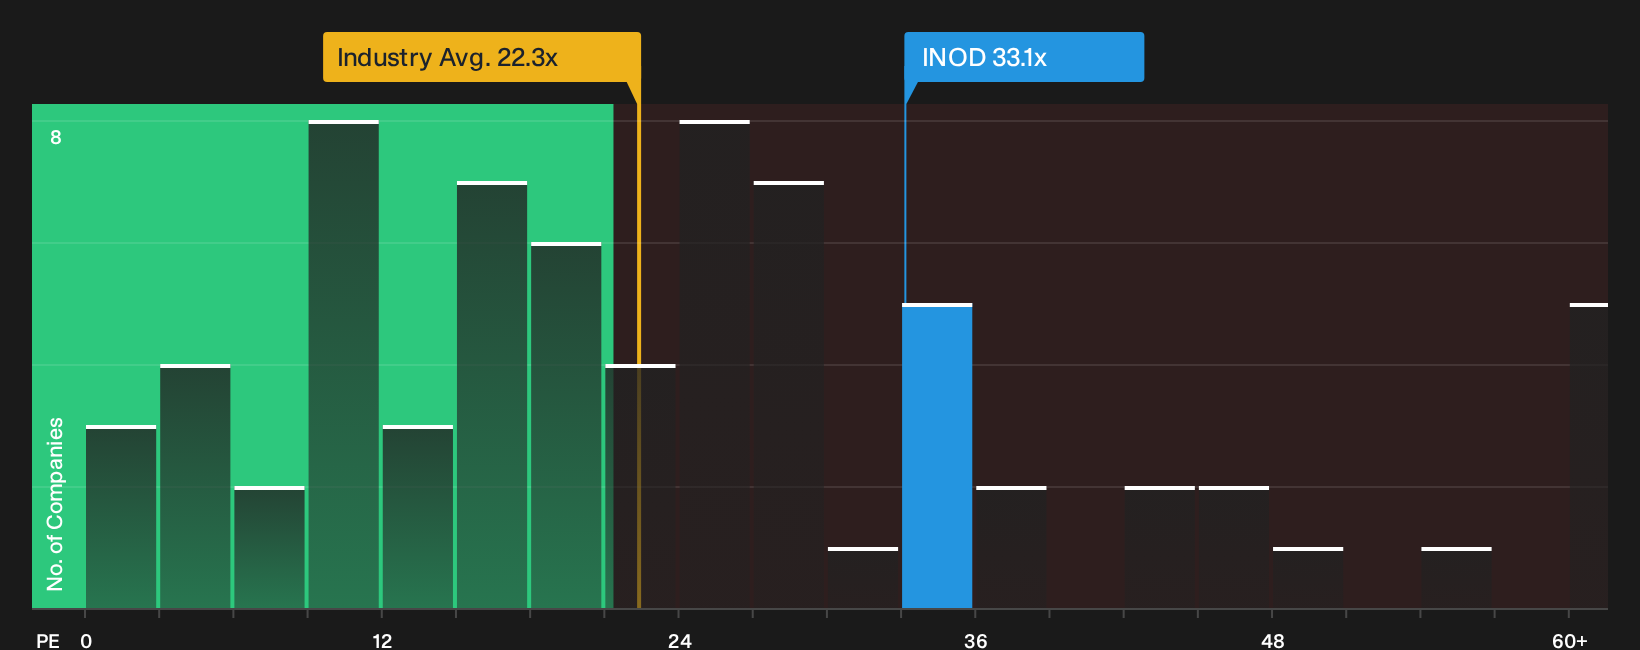
The P/E ratio suits Innodata because the market is very focused on what investors are paying for each dollar of current earnings. On this yardstick, the stock trades around 33.1x earnings, which is well above the Professional Services industry average of about 22.3x and also higher than the peer group near 20.8x. That puts a premium on the shares relative to many similar businesses.
Based on a tailored fair multiple that factors in Innodata’s sector, profitability profile and risk, the current P/E screens as overvalued rather than just punchy. Despite the recent investigation into workforce reductions and disclosures, the market is still assigning a valuation that prices in stronger earnings power than the benchmark would suggest. For anyone considering the stock, the key question is whether Innodata’s profit trajectory can grow into that richer P/E, or whether this premium leaves less room for error in the story. Explore the numbers behind Innodata's P/E valuation.
The Innodata Narrative: What Would Justify Today's Price?
Innodata’s valuation puzzle highlights the role of Simply Wall St Narratives. These are structured scenarios on the Community page that explain what would need to be true for growth, margins and earnings for the current share price to look either stretched or conservative. Each thesis links its numbers to a clear view on how Innodata's expansion, profitability and risk profile might evolve, giving you something specific to track as fresh information becomes available.
One of the top community narratives on Innodata: 64% undervalued
"The main thing that has to go right is Innodata continuing to shift its mix toward proprietary datasets, evaluation platforms, and diversified Big Tech, federal, and enterprise work..."
Discover why this Narrative puts Innodata at 64% undervalued.
Innodata’s share price is only one piece of the decision
Before deciding how Innodata fits into your portfolio, it is worth checking who is actually steering the business and how their pay packages line up with shareholder outcomes. See who runs Innodata and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com