


- SoundHound AI recently drew attention ahead of its November 5, 2026 earnings release, with analysts expecting higher revenue alongside lower earnings per share, putting the firm’s operating efficiency and cost structure under closer scrutiny.
- The key question now is how SoundHound AI’s heavy R&D spend, acquisition related costs, and timing of large enterprise deals are affecting the path toward more sustainable margins.
- We will now look at how SoundHound AI's investment narrative could be affected by strong revenue expectations contrasted with weaker projected EPS.
SoundHound AI Investment Narrative Recap
To own SoundHound AI, you need to believe its heavier R&D and acquisition related spending eventually supports a larger base of voice AI contracts across autos, restaurants, and broader enterprise. The near term catalyst is the November 5 earnings call, where clarity on how rising costs track against that revenue ramp will matter more than any headline EPS miss.
The biggest operational risk right now is that expenses keep climbing faster than sales from those lumpy enterprise deals, which could extend the company’s loss making period. If the upcoming update only confirms higher revenue with still weak per share results, the core long term thesis is not necessarily broken, but patience gets tested.
The most relevant recent development is the earnings preview itself, which points to much higher revenue but lower EPS year over year for SoundHound AI. That gap puts a spotlight on integration of acquired operations and whether management is starting to squeeze better gross profit out of the existing contract base.
For catalysts, investors are watching how this earnings report frames the trade off between funding Polaris and agentic AI capabilities and narrowing losses. If guidance or commentary signals more disciplined operating costs while keeping expectations for 30% plus revenue growth intact, it reinforces the idea that the current spending pattern is a step toward sustainable margins rather than away from them.
SoundHound AI's narrative projects US$463.8 million revenue and US$54.4 million earnings by 2029. This projection is based on 31.7% yearly revenue growth and an earnings improvement of about US$191.2 million from a loss of US$136.8 million today.
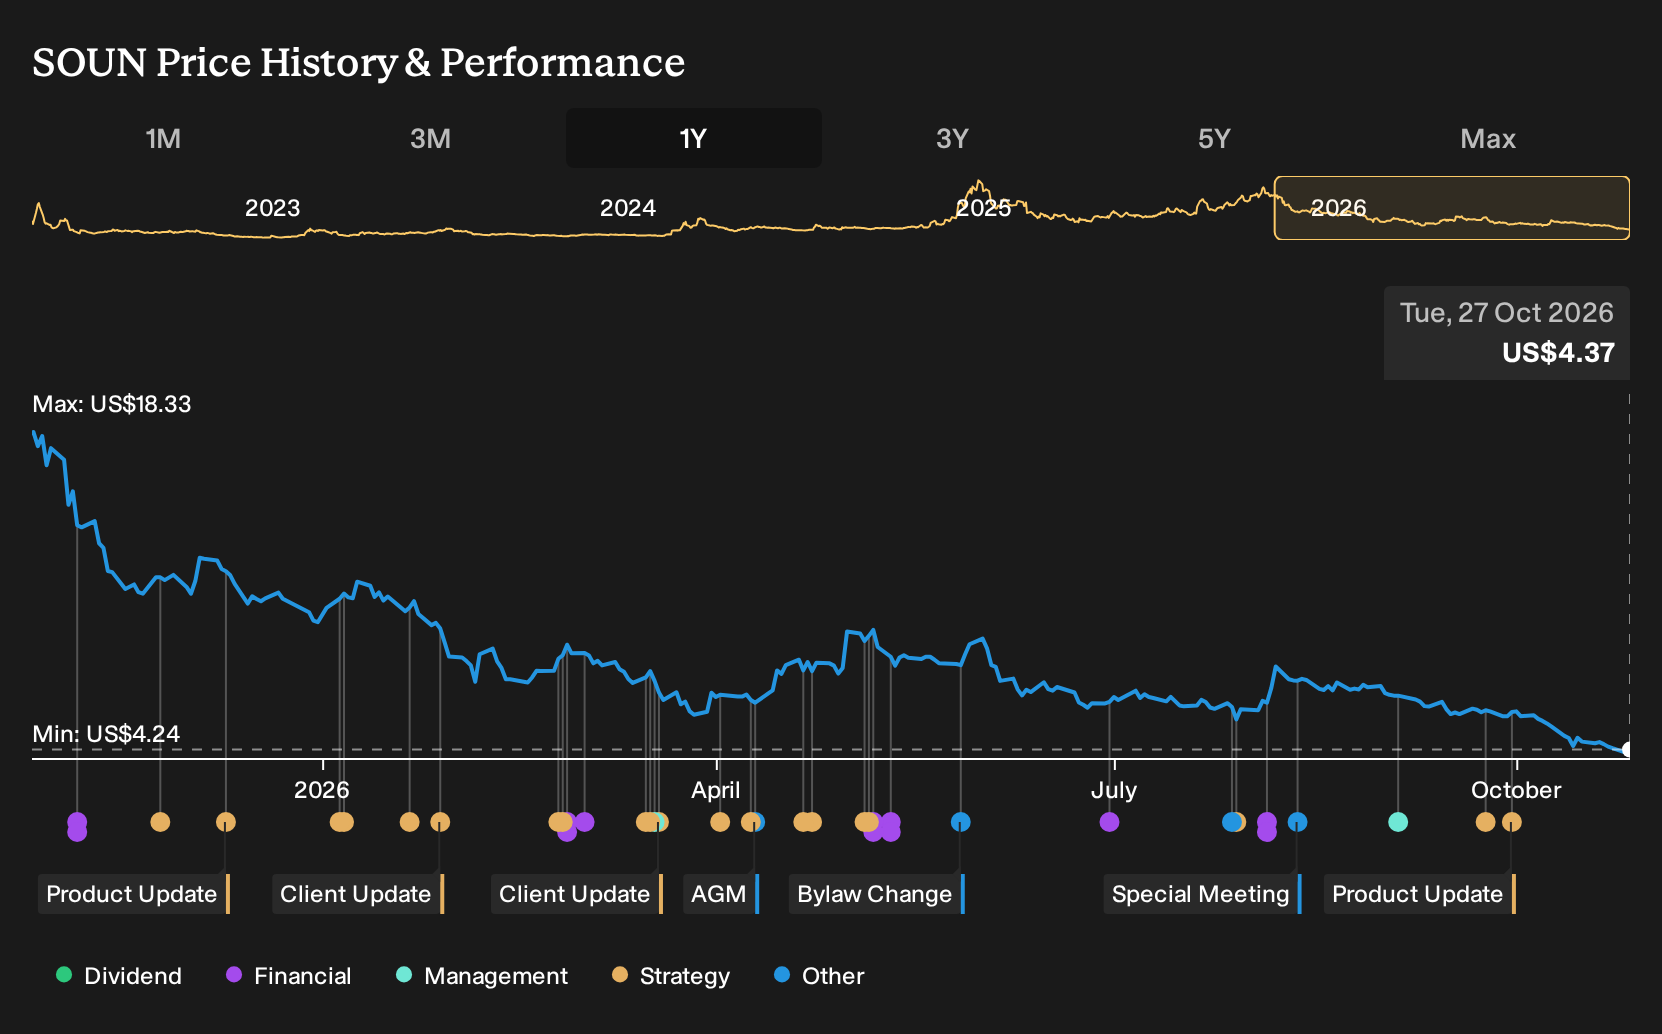
Uncover why SoundHound AI's fair value indicates a 188% potential upside to its current price, which could narrow quickly if sentiment turns.
Exploring Other Perspectives
One optimistic angle on SoundHound AI focuses on the OASYS agentic platform as a potential accelerator, with the most bullish analysts modeling about 35.6% annual revenue growth and roughly US$59.5 million in earnings by 2029. Those projections were set before this earnings preview, so you may see those upbeat expectations shift as new details land.
Explore 5 other SoundHound AI fair value estimates, including one that suggests as much as 101798% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your SoundHound AI research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for SoundHound AI. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate SoundHound AI's overall financial health at a glance.
Looking For More Ideas Beyond SoundHound AI?
If the SoundHound AI story has sharpened your thinking about risk, reward, and time horizon, you can use that same lens across a wider watchlist. The Simply Wall St Screener can help you quickly surface candidates that better fit your comfort level on profitability, volatility, and balance sheet strength.
- For investors who care most about valuation support, consider starting with a 29 high quality undervalued stocks, which may pair solid fundamentals with prices that sit below many model estimates.
- If income and resilience matter more to you than rapid growth, look at companies in the 5 dividend fortresses that prioritize steady cash returns to shareholders.
- When capital preservation and shock resistance sit at the top of your checklist, filter for a 30 resilient stocks with low risk scores that score well on balance sheet quality and earnings stability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com