


Vulcan Materials has delivered a solid multi‑year gain for shareholders. However, the recent share price path raises a fresh question about whether the current valuation lines up with the cash the business is expected to generate. With the stock recently around US$262.50 and sentiment influenced by sector headlines, the real issue is what those moves imply for its long term cash flows.
- Over the past 5 years, Vulcan Materials has produced a return of 40.1%, which puts a meaningful spotlight on whether that performance is supported by the cash the company can produce in the future.
- Recent coverage around Vulcan Materials has highlighted management reaffirming its 2026 adjusted EBITDA outlook, which can shape expectations for how quickly operating profits may convert into cash over the coming years.
- If you'd rather focus on earnings, this one's for you. See why Vulcan Materials's 30.4x P/E tells a different valuation story.
For investors, the debate is whether Vulcan Materials' current share price is justified by its cash flows when viewed through a Discounted Cash Flow (DCF) lens.
If you want more ideas built around cash generation, a focused stock screen is a useful second step besides Vulcan Materials. You can start with the 29 high quality undervalued stocks.
Does Vulcan Materials Look Fairly Valued on Cash Flow?
The Discounted Cash Flow (DCF) model here focuses on how much cash Vulcan Materials can return to shareholders over time. Latest twelve month free cash flow is about $1.05b, and the projections used in the 2 Stage Free Cash Flow to Equity model assume that this cash generation grows from that base over the coming decade rather than shrinking.
Based on that set of cash flow estimates, the DCF outcome suggests an intrinsic value broadly in line with the current share price of $262.50. Vulcan Materials recently reaffirmed its 2026 adjusted EBITDA outlook, and that steady guidance helps explain why the market price and the DCF result are so close. For investors who want to see the detailed assumptions and how sensitive the conclusion is to different growth or discount rates, the full model is here. Find out what Vulcan Materials could be worth using our Discounted Cash Flow (DCF) estimate.
The Vulcan Materials Narrative: What Would Justify Today's Price?
Narratives for Vulcan Materials pick up where the DCF discussion leaves off and explain which growth, margin and earnings paths would need to hold for the stock to be worth materially more or less than today’s price on Simply Wall St's Community page. Each narrative turns that idea of fair value into a thesis about Vulcan Materials' business that can be tracked over time, rather than treated as a static snapshot.
The community is split on Vulcan Materials, with one camp seeing more upside left in the cash story and the other arguing the current price already bakes in a bullish outcome.
Bull case: 16% undervalued
"The current narrative that Vulcan Materials is undervalued implies that the share price does not fully reflect its cash generation, return on invested capital, and balance sheet capacity to fund growth and shareholder returns..."
Discover why this Narrative puts Vulcan Materials at 16% undervalued.
Bear case: 6% overvalued
"Bearish analysts expect higher energy costs, weak residential demand and potential public funding pressure to weigh on Vulcan Materials’ volumes, pricing headroom and operational flexibility over the coming years..."
Explore why this Narrative puts Vulcan Materials at 6% overvalued.
The share price is only one piece of the Vulcan Materials puzzle
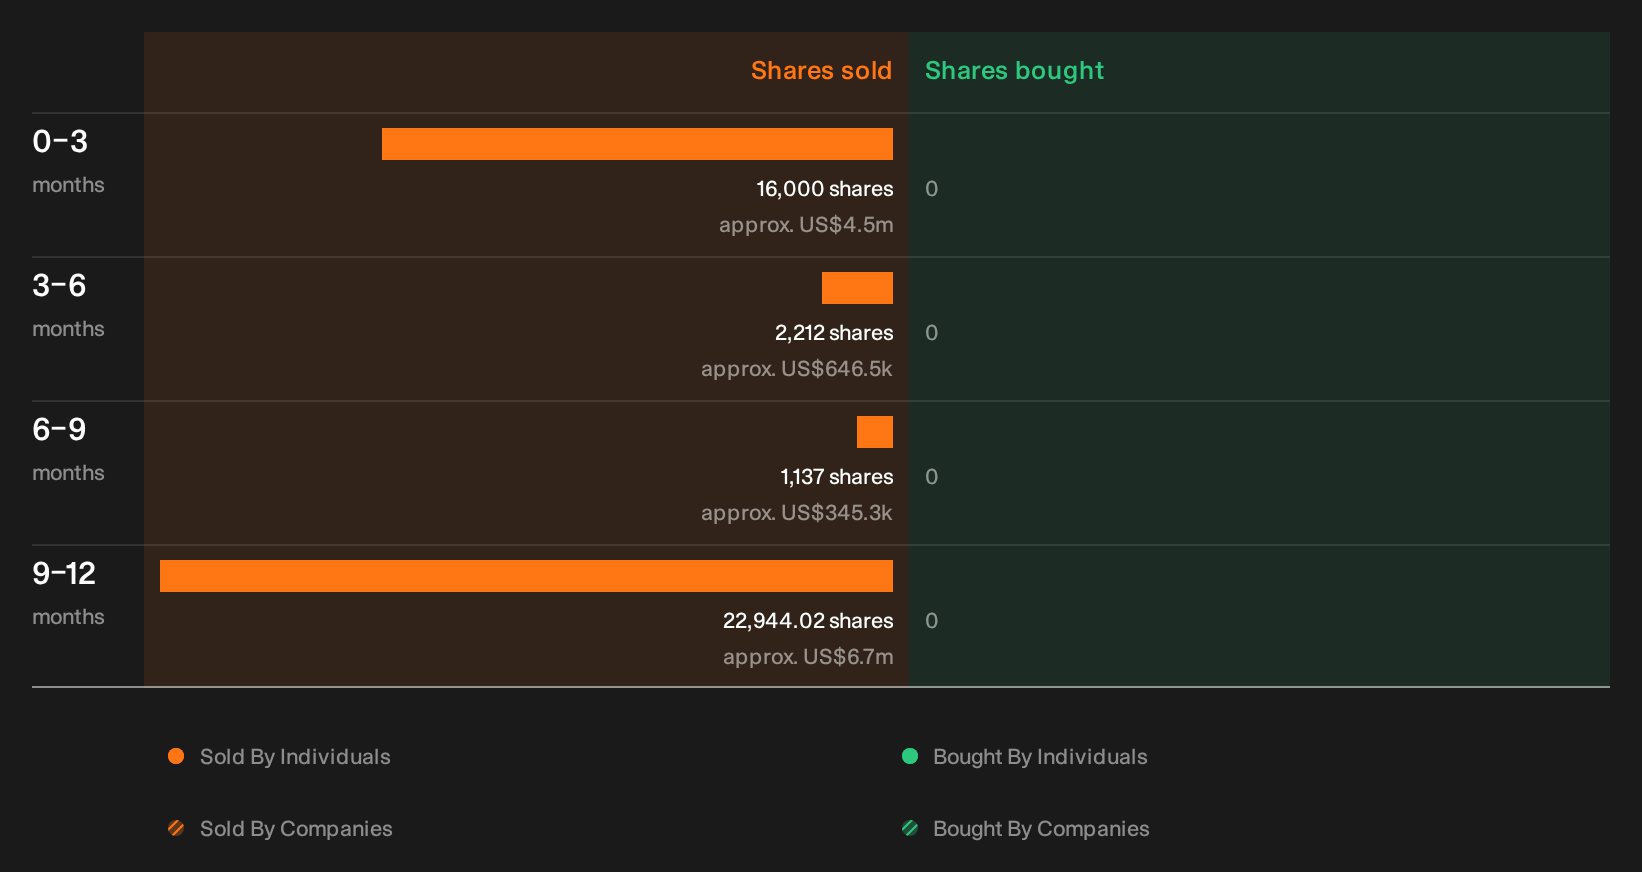
Before you form a view on Vulcan Materials, it is worth checking what insiders have been doing with their own holdings, including who has sold, how much, and what that might signal. See the recent insider selling flagged for Vulcan Materials.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com