


US Foods Holding has produced a powerful share price story in recent years, so the live question now is whether the current valuation is supported by the cash it can generate. With the stock recently closing at US$102.57, investors are asking if that price is in line with what its future cash flows may justify.
- Over the past 5 years, US Foods Holding has returned 186.7%, which puts a lot of weight on whether its cash generation can keep backing up that kind of share price performance.
- The business model relies heavily on converting relatively low-margin food distribution operations into steady operating cash flow. As a result, small shifts in costs or pricing power can meaningfully affect the cash that is ultimately available to shareholders.
- If you'd rather focus on earnings, this one's for you. See why US Foods Holding's 30.5x P/E tells a different valuation story.
The issue now is whether that recent share price level is aligned with the intrinsic value suggested by its cash flows.
If you are weighing whether US Foods Holding's cash flows justify its recent run, it can help to compare it with a wider group of companies from a focused screen such as 29 high quality undervalued stocks.
Is US Foods Holding Still Cheap on Cash Flow?
The Discounted Cash Flow (DCF) model here weighs what US Foods Holding might return to shareholders in future, then brings those cash flows back to today’s dollars. Latest twelve month free cash flow sits around $977.8 million, which is a sizeable pool for a distributor working on tight margins. Projected cash flows in the model use a growing profile rather than a shrinking one, with estimates extending into the 2030s based on both analyst inputs and gradual growth assumptions.
On those projections, the DCF output suggests US Foods Holding’s estimated intrinsic value is substantially above the current share price of US$102.57. That gap reflects a view that the company can keep converting its distribution footprint into meaningful cash generation over time, even though each individual year’s growth rate may shift around. For anyone comparing the traded price with the cash it is expected to throw off, the full set of assumptions and outcomes is worth reviewing in detail. Find out what US Foods Holding could be worth using our Discounted Cash Flow (DCF) estimate.
The US Foods Holding Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for US Foods Holding pick up where the DCF puzzle leaves off by spelling out which paths for growth, margins and earnings would need to play out for the stock to be worth materially more or less than today’s price on the Community page. Where a single ratio or valuation model gives one headline figure, these scenarios outline the future that figure relies on, so you can later check whether the business is actually tracking that path.
Bulls and bears on US Foods Holding are looking at the same cash engine yet reaching very different conclusions on how much is already priced in.
Bull case: 12% undervalued
"US Foods Holding's accelerated investment in digital platforms and supply chain automation, such as the MOXe platform and Descartes routing, has now expanded into AI enabled tools for pricing, routing, labor planning, and sales support..."
Discover why this Narrative puts US Foods Holding at 12% undervalued.
Bear case: 22% overvalued
"Rising fuel costs, only partially offset by surcharges that recover about 30% to 40% of fuel increases and subject to a timing lag, combined with a larger truck fleet to support Pronto and Pronto Next Day expansion, could keep distribution costs structurally higher and weigh on net margins and EBITDA per case..."
Explore why this Narrative puts US Foods Holding at 22% overvalued.
One more piece of the US Foods Holding puzzle
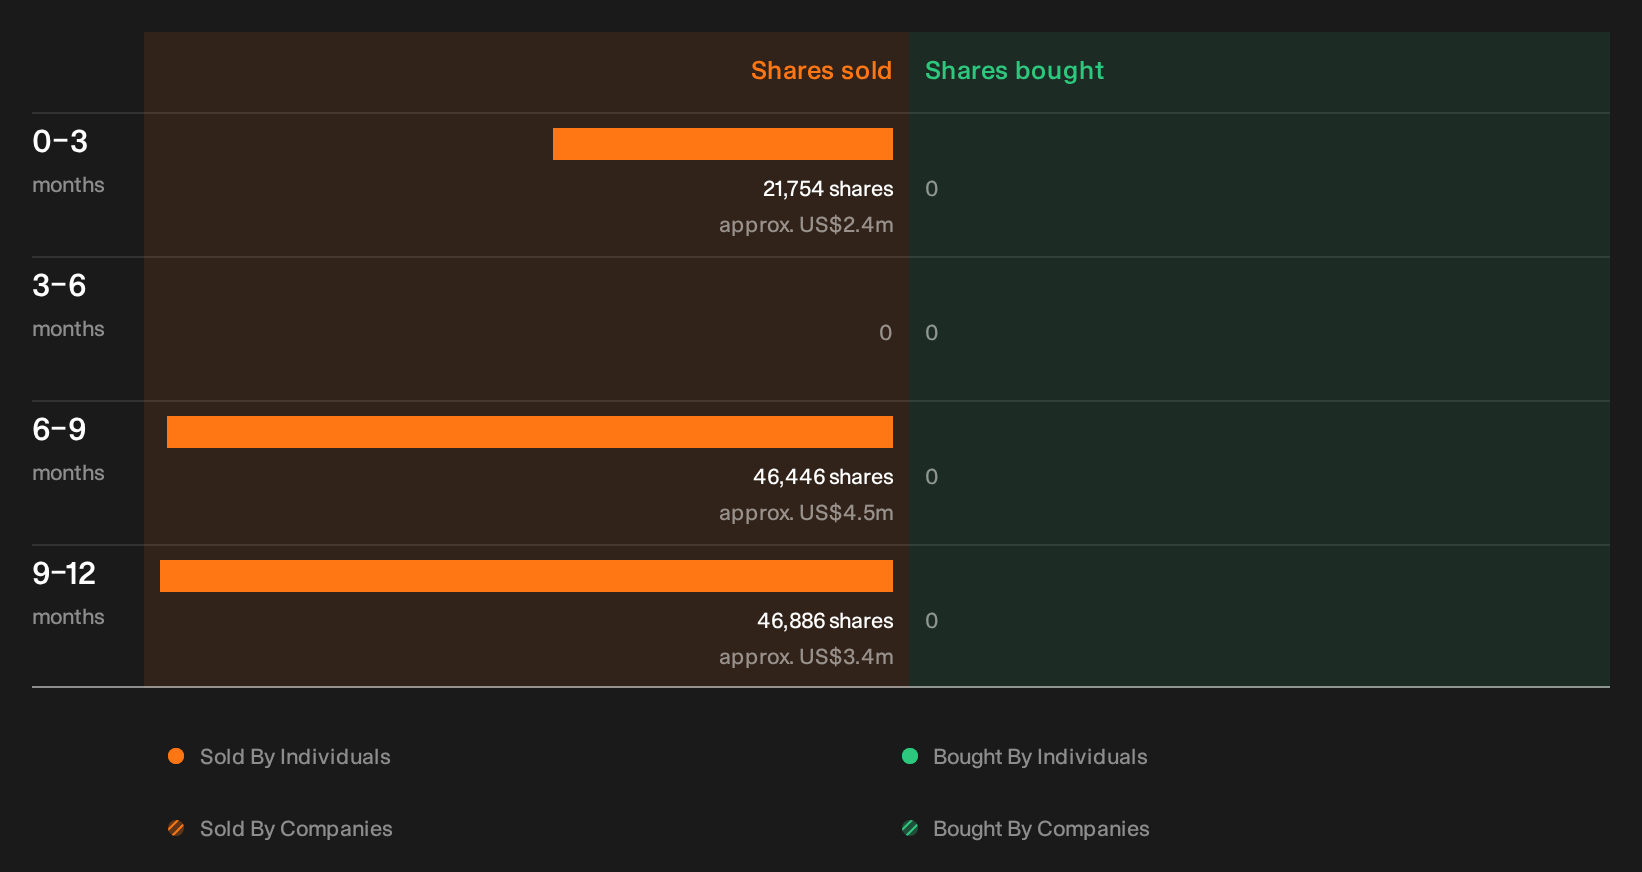
Before you decide how US Foods Holding fits into your watchlist, it is worth checking what company insiders have been doing with their own shares, who has been selling and by how much. See the recent insider selling flagged for US Foods Holding.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com