


Fujiya just posted its Q3 2026 scorecard, and the headline is all about pressure on profitability, not a collapse in demand. The stock closed at ¥2,428 on 28 October, after a choppy month where the price slipped roughly 4% even as trailing twelve month earnings stayed positive and the P/E hovered near 53x. That is a rich multiple for a confectionery player whose net margin over the past year sat around 1%. Today’s cautious share reaction looks less like panic and more like investors finally confronting how tight that margin squeeze has become.
Like Fujiya’s brands but uneasy about a 1% net margin backing a 53x P/E? Check out the list of solid balance sheet and fundamentals stocks (23 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): ¥28,249 million vs. ¥27,282 million (up about 3.5%)
- Net Income (Excl. Extra Items, Q3 2026 vs Q3 2025): ¥130 million vs. ¥71 million (up about 83%)
- Basic EPS (Q3 2026 vs Q3 2025): ¥5.04 per share vs. ¥2.75 per share (up about 83%)
- Trailing 12-Month Net Margin (latest vs prior year): 1.0% vs. 1.6% (margin has compressed over the year)
Fujiya’s net margin slipped to 1% as its P/E stayed rich. Ask Charlie what makes Fujiya worth a 53x P/E.
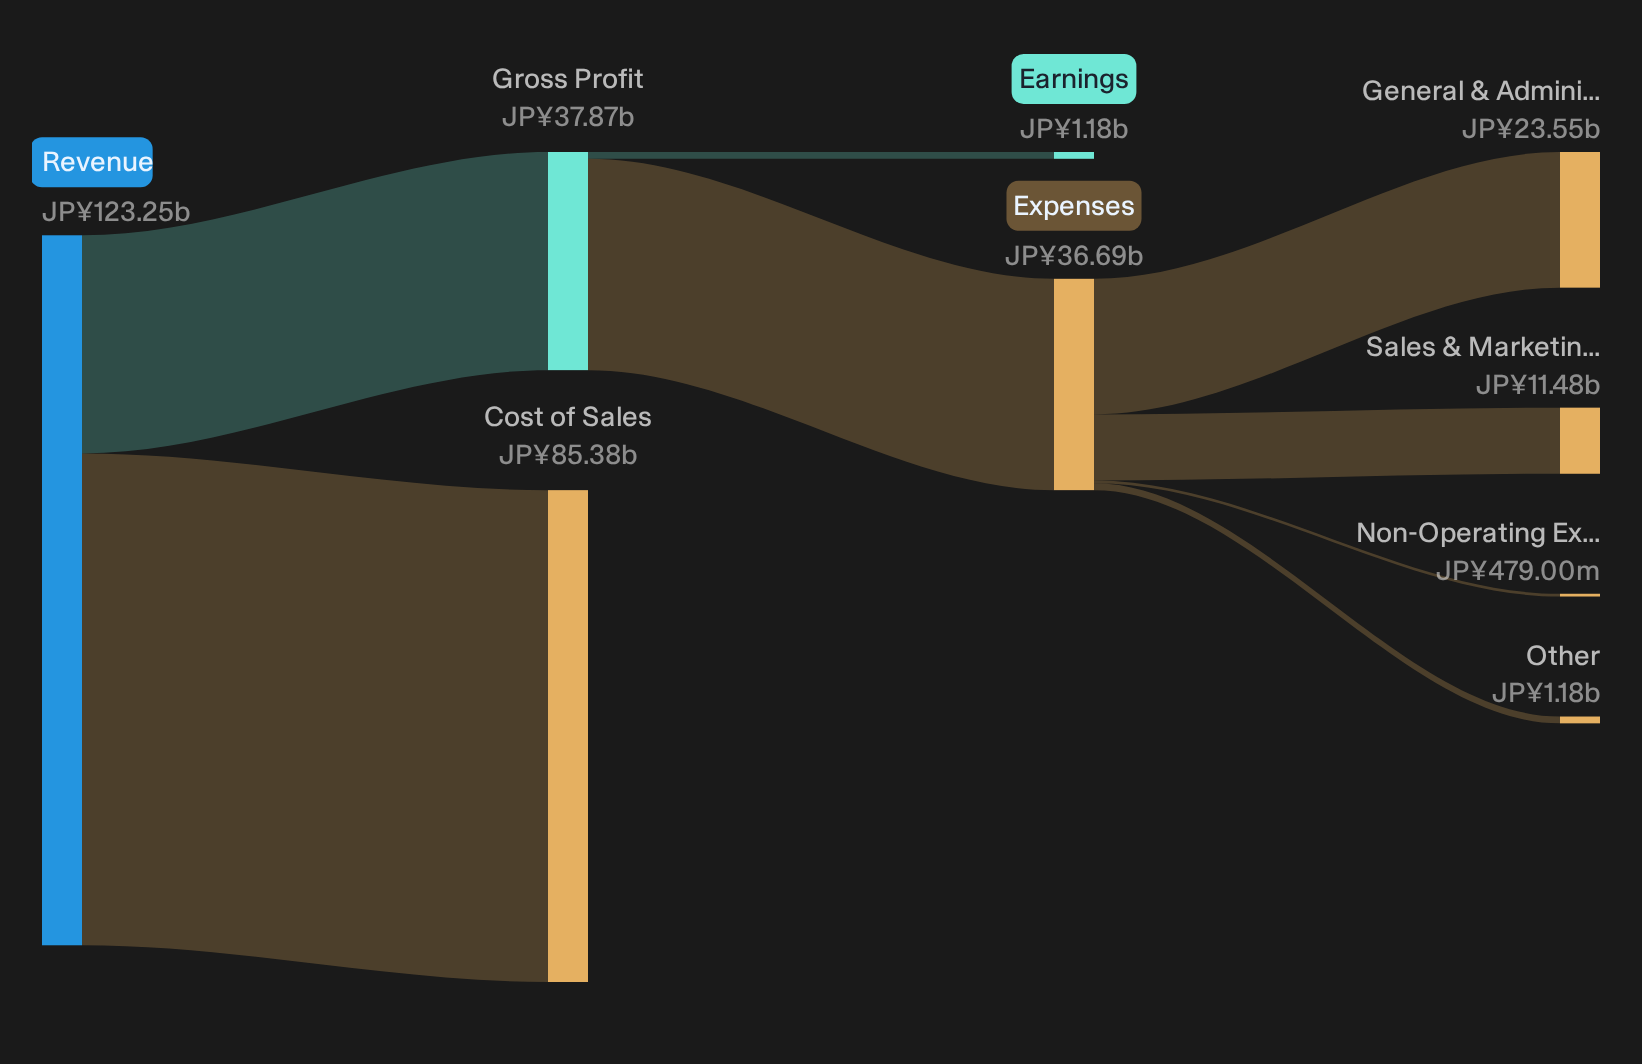
Fujiya earnings: where the bullish story still holds
For a defensive consumer brand like Fujiya, the headline looks constructive. Revenue in Q3 2026 was ¥28,249 million compared with ¥27,282 million a year earlier, so demand for sweets and snacks still leans resilient rather than shrinking. Core profitability also moved the right way. Net income excluding extras reached ¥130 million versus ¥71 million, and basic EPS rose to ¥5.04 from ¥2.75. For anyone leaning on the heritage brand and everyday consumption story, these figures keep that thesis alive.
Margin squeeze keeps the Fujiya bear case alive
The tension sits in the margin line. Over the last twelve months, Fujiya’s net margin moved from 1.6% to 1.0%, even with better quarterly earnings. That combination suggests cost pressure or mix issues are still biting. Recent share performance, with the price down across 7, 30 and 90 days, also lines up with investors questioning how much profit the brand strength can really support. The business is not breaking, but the weaker profitability trend gives plenty of ammunition to cautious holders.
After five years of declining earnings and a thinner 1% net margin, it is worth asking whether Fujiya’s issues are cyclical or structural. Scan the independent risk analysis for Fujiya which shows 2 important warning signsHunt Stronger Balance Sheets Quietly
Fujiya’s squeezed margins and rich P/E show how thin protection can feel when profitability tightens. The real opportunity is finding stocks that could be low debt before the market corrects them.
- Company 1 - 36% below our estimate - uses AI tools to deepen hiring automation and improve marketing matches as clients shift spend into higher value software.
- Company 2 - 18% below our estimate - expands its sales force so more elevator owners adopt long term maintenance and modernization contracts in its network.
- Company 3 - 50% below our estimate - channels heavier AI and cloud spending into a unified security platform that draws customers toward recurring subscription bundles.
Three companies from the same screener. Open every one of the 23 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com