


Avarda Bank’s fresh capital move and earnings backdrop
Avarda Bank (OM:AVARDA) just issued SEK 250 million of Additional Tier 1 bonds and confirmed early redemption of older AT1 debt, alongside a recent quarterly report showing higher net interest income and net profit versus last year.
Avarda Bank’s latest Additional Tier 1 issue lands alongside a share price that has climbed 6.64% over the past month and 14.47% over 90 days, while the 1 year total shareholder return of 22.16% sits against a very large 3 year total shareholder return of roughly 4.7x. This suggests that investors are still pricing in stronger earnings power and a capital structure that supports further growth in the lending and payments franchise.
Scan how Avarda Bank’s funding move compares with other lenders by reviewing our curated list of solid balance sheet and fundamentals (207 results).
Avarda Bank now trades at a double discount, both to analyst targets and to one estimate of fair value, even after this fresh AT1 issue and earnings update. Is the market’s caution still warranted?
Price-to-earnings of 17x for Avarda Bank: Is it justified?
Avarda Bank changes hands at a P/E of 17x, which puts the current SEK212 share price above both its peer average and one estimate of a fairer earnings multiple.
The P/E ratio compares what investors are paying for each unit of earnings. For a lender like Avarda Bank, it reflects how the market weighs its 23.1% Return on Equity, high quality earnings, and an earnings profile that has grown 15.9% over the past year against risk factors such as a 4.3% bad loans ratio and an unstable dividend record.
On these numbers, the market is assigning a richer valuation than the peer average P/E of 12.5x and the estimated fair P/E of 15.1x. That points to investors paying a premium multiple that is materially above both direct banking peers and the level the fair ratio suggests the valuation could move toward if sentiment normalises.
Explore the SWS fair ratio for Avarda Bank.
Result: Price-to-earnings of 17x (OVERVALUED)
Still, a 4.3% bad loans ratio and a low value score of 2 could unsettle confidence in Avarda Bank if credit quality or sentiment weakens.
Find out about the key risks to this Avarda Bank narrative.
Another view on Avarda Bank’s valuation
The earnings multiple paints Avarda Bank as expensive, yet the SWS DCF model points in the opposite direction. At SEK212, the shares sit around 35% below an estimated future cash flow value of SEK327.46, which frames the same business as undervalued on cash flow terms.
The gap between a premium P/E and a discounted cash flow outcome raises a simple question for you as an investor: Which signal deserves more weight for a lender with high Return on Equity and meaningful bad loans risk, the price on today’s earnings or the longer term cash generation story?
Look into how the SWS DCF model arrives at its fair value.
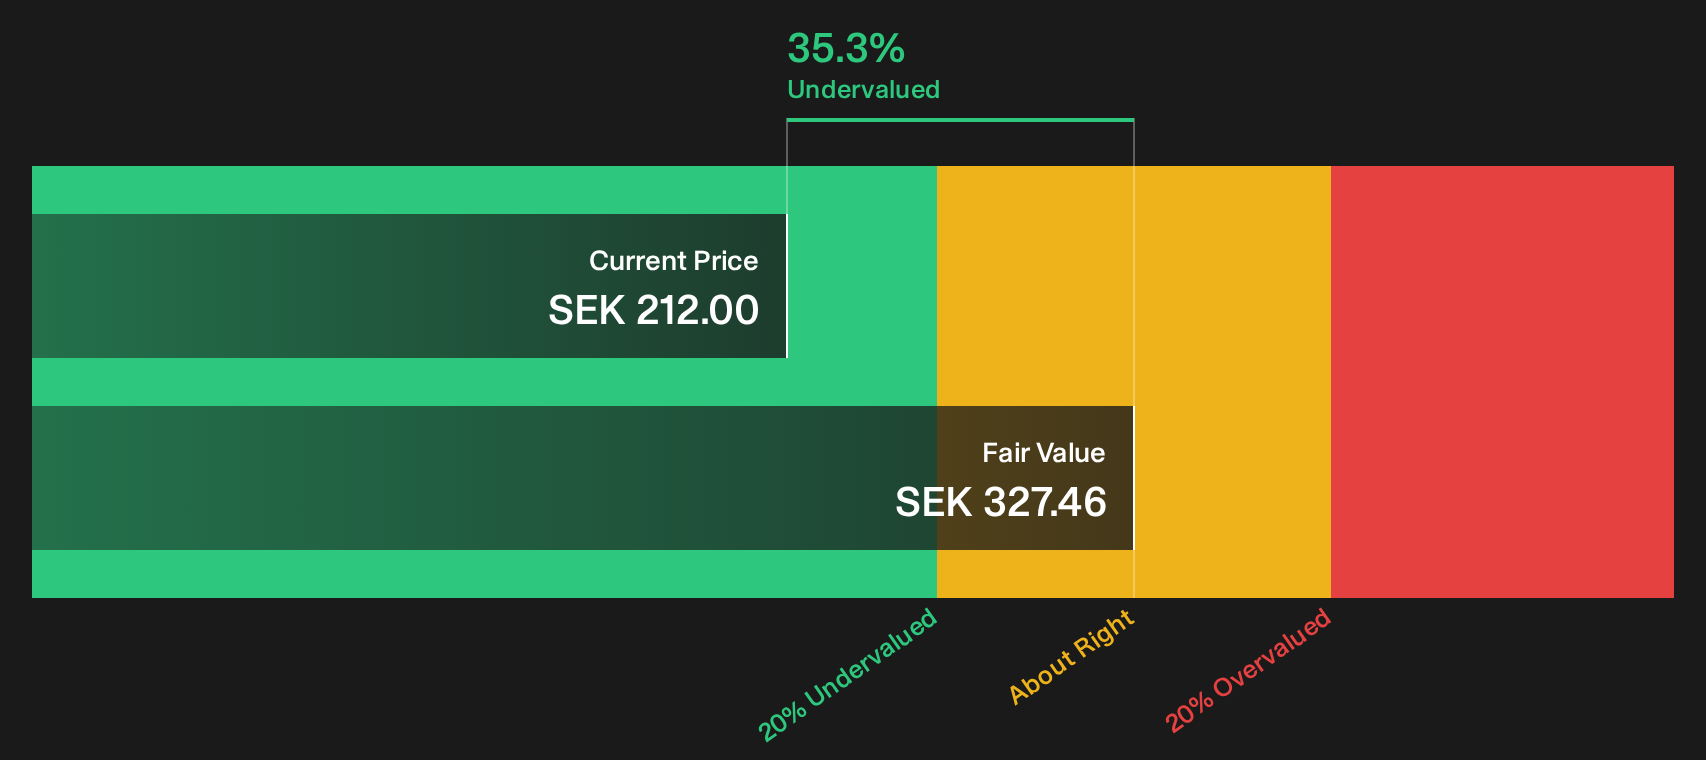
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Avarda Bank for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 195 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Avarda Bank’s value and risk profile call for your own judgment. Consider acting promptly, reviewing the numbers carefully, and weighing the company’s 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Avarda Bank?
Do not stop with Avarda Bank. Put these tools to work so you keep spotting opportunities instead of watching them pass by on the chart.
- Target strong fundamentals and steady balance sheets by scanning a list of solid balance sheet and fundamentals (207 results) that focuses on financial strength and resilience.
- Hunt for quality at a discount with a 195 high quality undervalued stocks that filters for robust businesses priced below one assessment of their worth.
- Build a potential income stream by reviewing a 224 dividend fortresses that highlights higher yielding companies with the potential to support regular payouts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com