


EU and Canadian leaders are floating a deeper trade and critical raw materials alliance, and that could quietly reshape where capital flows next. Investors watching this possible “associate membership” shift see both new openings and fresh policy risk around the supply chains that feed energy transition and advanced manufacturing. This article walks through 3 stocks from the screener that appear positively exposed to that story.
The three stocks below only skim the surface of what this theme could mean for critical raw materials exposure tied to EU–Canada trade, since the full screen surfaced 22 more companies with equally compelling narratives that are not covered in this article. To identify and analyze those additional potential suppliers with your own filters and conviction, head straight into the Critical Raw Materials Suppliers Linked to EU–Canada Trade screener.
Imerys (ENXTPA:NK)
Imerys is a Paris headquartered minerals supplier that links critical raw materials to real world uses, a potentially useful position as EU and Canadian trade talks focus on secure inputs for batteries, construction and advanced manufacturing.
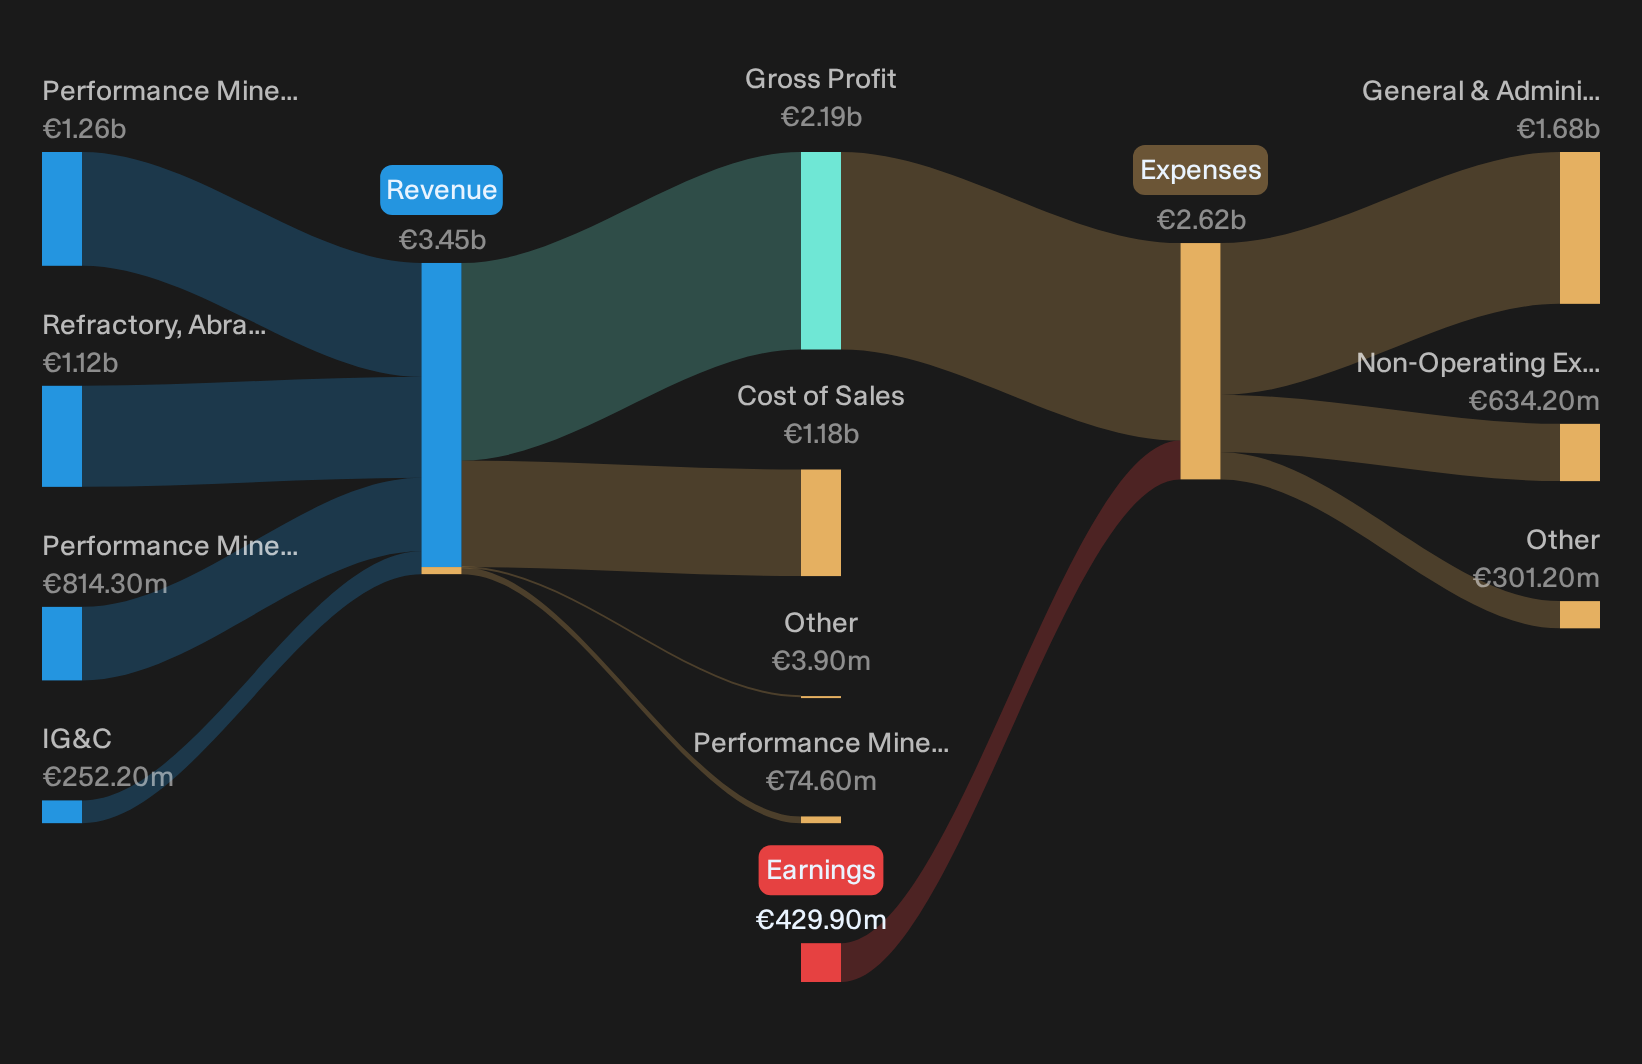
Imerys supplies specialty minerals across industries, from ceramics and building materials to energy transition markets like batteries and mobile energy. Revenue is anchored in Performance Minerals, with about €1.3b from PM EMEA & APAC and €814 million from PM Americas, alongside €1.1b from Refractory, Abrasives & Construction. With a market value close to €1.9b, it sits in the mid cap bracket for European materials tied to critical raw inputs.
For investors watching EU and Canada supply chain discussions, Imerys offers a minerals processing platform that could plug Canadian critical raw materials into European value chains if trade integration deepens.
"Ongoing efficiency programs such as Horizon and I Cube, which are targeting annual run rate savings of €50m to €60m versus the 2025 cost base with €70m already booked by June 2026, create room for further restructuring of underperforming units and could feed directly into higher group EBITDA margins as more of the savings drop below the line."
What happens to those margin ambitions if a single pressure point on project discipline or capital allocation shifts is what really matters here.
If that capital discipline question is front of mind, read the full narrative for Imerys to see how efficiency savings, portfolio shifts and risk factors really interact.
Labrador Iron Ore Royalty (TSX:LIF)
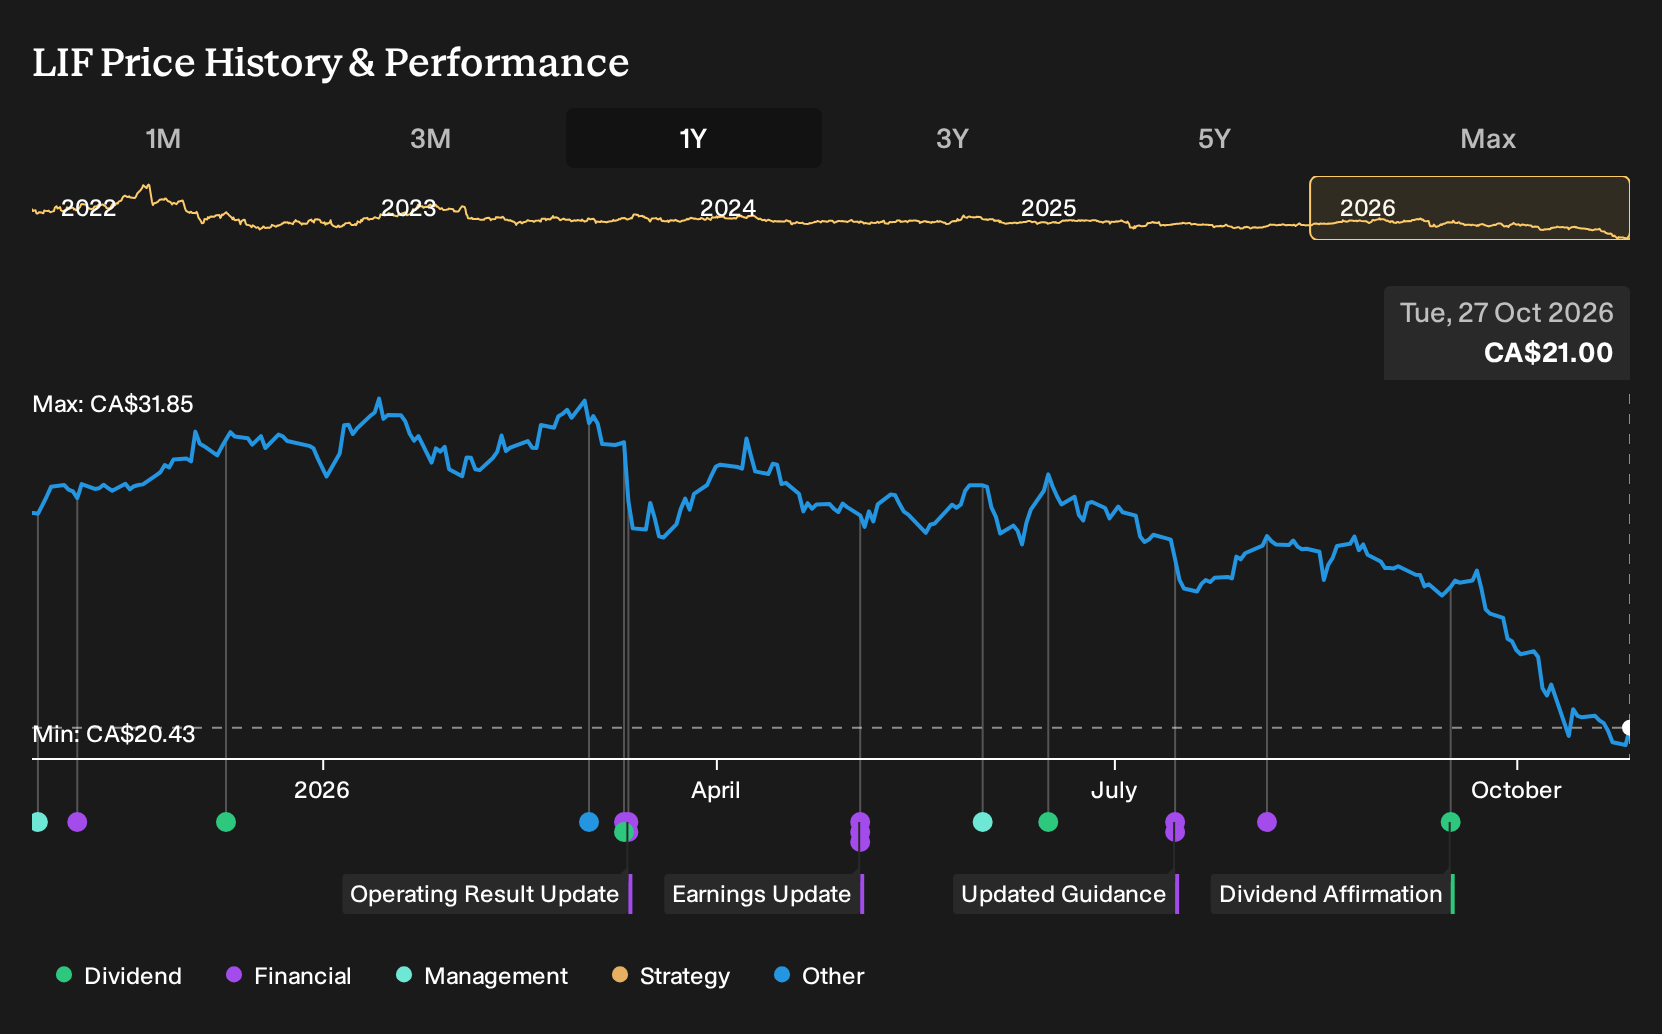
Labrador Iron Ore Royalty gives you exposure to Canadian iron ore through its 15.1% stake in Iron Ore Company of Canada, directly linked to raw materials that may matter for future EU–Canada trade flows. It generated about CA$153 million from iron and steel related activity in Canada, and the stock is valued at roughly CA$1.3b.
For investors tracking critical raw materials, Labrador Iron Ore Royalty is a pure play on Canadian iron ore that feeds steel, infrastructure and industrial demand that could intersect with deeper EU–Canada supply chains. High margins and a substantial dividend yield make the business interesting, although the appeal of that income stream rests on how one pressure in the iron ore cycle resolves.
That iron ore cycle question makes it worth a closer look at the 3 key rewards and 1 important major warning sign to see what might accelerate or pressure that payout profile.
Neo Performance Materials (TSX:NEO)
Neo Performance Materials plugs directly into the EU–Canada critical raw materials story through its rare earth and magnet products, with Magnequench and Rare Metals contributing about $239 million and $242 million of segment revenue alongside $129 million from Chemicals & Oxides, and a market value near CA$1.1b.
Neo Performance Materials is where the EU–Canada critical raw materials theme becomes very tangible for investors looking at magnets and rare earths rather than just ore in the ground.
"A major development in 2026 is the operational status of its new sintered magnet facility in Narva, Estonia, designed to supply the EV market and positioning Neo as a critical partner for European automakers striving to meet EU local content requirements under the CRMA."
What that focus on higher value magnets ultimately does to pricing power and cash generation depends on how one tight feedstock constraint plays out.
If that feedstock bottleneck is what you keep coming back to, the full narrative for Neo Performance Materials shows how Neo Performance Materials could still accelerate its magnet economics and cash profile.

Seeking Alternatives Beyond Raw Materials?
Fresh ideas move first. By the time momentum is flying, early entry points can be gone. Scan these under the radar lists before the crowd and act now.
- Spot cash rich operators before the story spreads by running your filters through the list of solid balance sheet and fundamentals (207 results).
- Track income focused opportunities while yields stay elevated by scanning the 224 dividend fortresses.
- Ride the build out of next generation infrastructure by reviewing the 42 power grid technology and infrastructure stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com