


As global markets navigate the complexities of AI investment concerns and rising oil prices, small-cap stocks have shown resilience, with the Russell 2000 Index leading major benchmarks by advancing 2.00%. In this environment of shifting market leadership and value-oriented stock performance, identifying potentially undervalued small caps can be crucial for investors looking to capitalize on emerging opportunities.
Top 10 Undervalued Small Caps With Insider Buying Globally
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| Q Technology (Group) | 3.2x | 0.2x | 48.57% | ★★★★★☆ |
| Charter Hall Long WALE REIT | 8.6x | 12.1x | 39.95% | ★★★★★☆ |
| China Aircraft Leasing Group Holdings | 6.7x | 0.9x | 41.34% | ★★★★★☆ |
| Diversified Royalty | 25.1x | 9.9x | 47.21% | ★★★★☆☆ |
| Nexus Industrial REIT | 10.1x | 3.0x | 9.31% | ★★★★☆☆ |
| Australian Finance Group | 8.0x | 0.3x | 11.75% | ★★★★☆☆ |
| Clover | 15.9x | 1.7x | 48.21% | ★★★☆☆☆ |
| Citicore Energy REIT | 12.8x | 9.7x | 29.18% | ★★★☆☆☆ |
| FINEOS Corporation Holdings | 100.5x | 2.9x | 48.89% | ★★★☆☆☆ |
| AB Dynamics | NA | 1.7x | 22.16% | ★★★☆☆☆ |
Let's explore several standout options from the results in the screener.
Domino's Pizza Enterprises (ASX:DMP)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Domino's Pizza Enterprises operates a network of franchise and corporate-owned pizza restaurants across multiple countries, with a focus on delivering quality pizza and related products, and has a market cap of approximately A$5.67 billion.
Operations: Domino's Pizza Enterprises generates revenue primarily from its restaurant operations, with a recent figure of A$2.05 billion. The company incurs significant costs of goods sold (COGS), amounting to A$1.39 billion, which impacts its profitability. The gross profit margin has shown fluctuations, recently recorded at 31.88%. Operating expenses also play a substantial role in the financial structure, with notable allocations towards sales and marketing and general administrative expenses.
PE: -15.0x
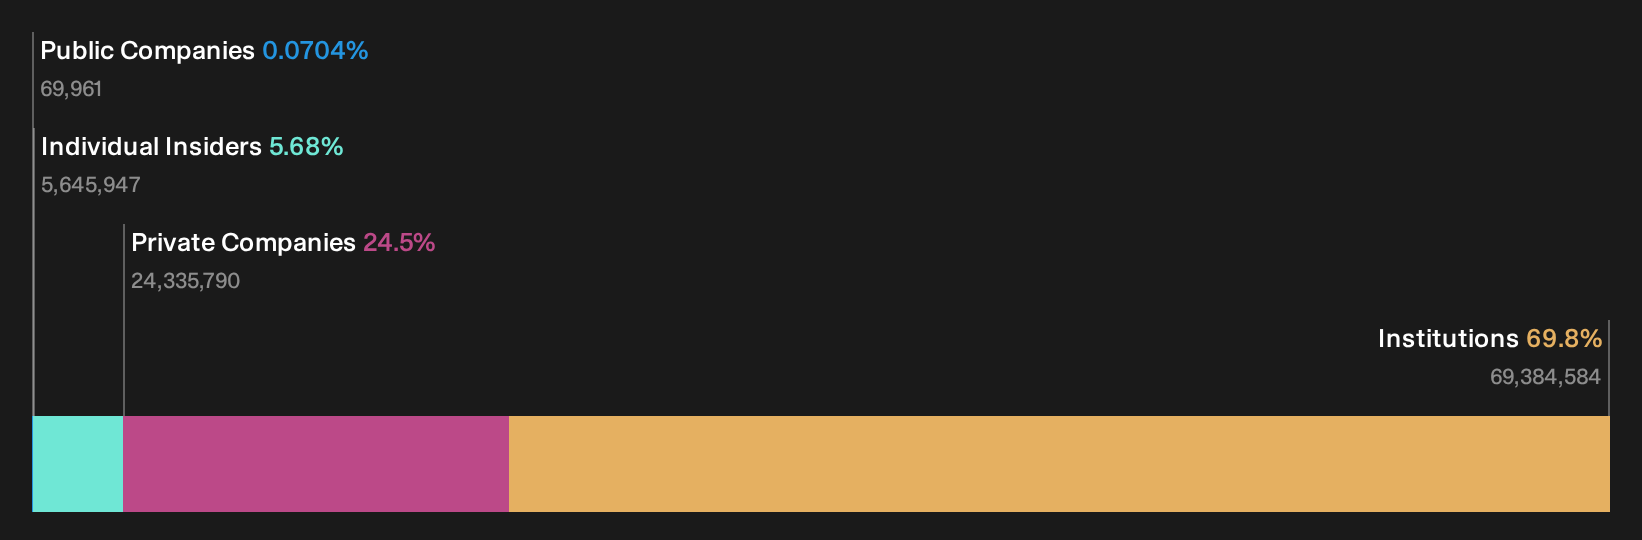
Domino's Pizza Enterprises, a smaller market player, recently faced challenges with a net loss of A$134 million for the year ending June 2026, compared to a minor loss previously. Despite this setback, insider confidence is evident as Jack Cowin purchased 170,000 shares worth approximately A$3.05 million between July and October 2026. Although dropped from the FTSE All-World Index in September 2026, earnings are projected to grow by 43% annually. The company relies on external borrowing for funding but continues dividend payouts with an increased dividend announced in August 2026.
- Get an in-depth perspective on Domino's Pizza Enterprises' performance by reading our valuation report here.
Learn about Domino's Pizza Enterprises' historical performance.
Asia United Bank (PSE:AUB)
Simply Wall St Value Rating: ★★★★☆☆
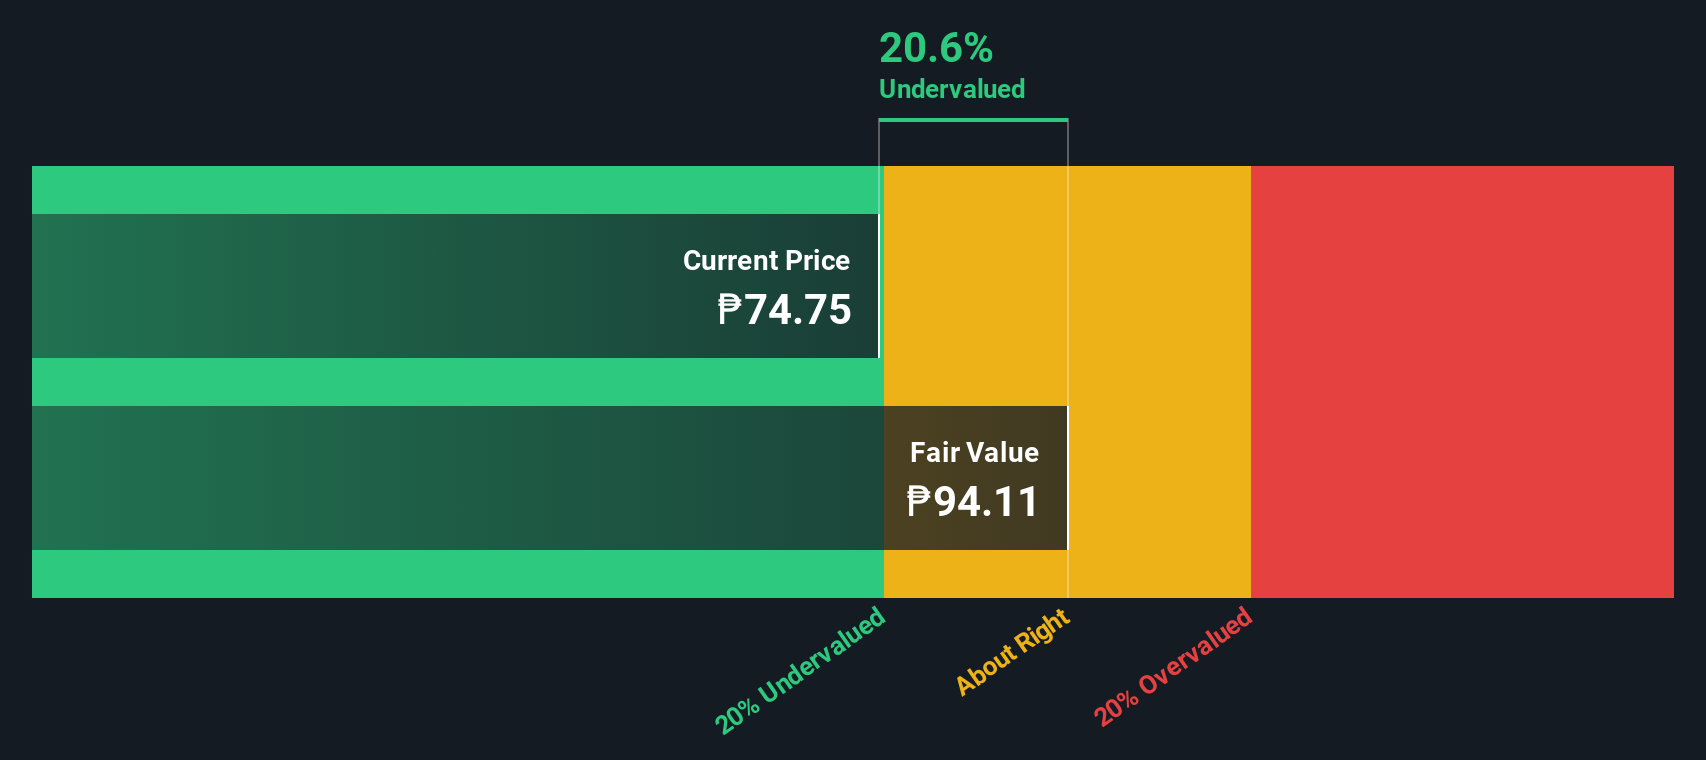
Overview: Asia United Bank is a Philippine-based financial institution that provides a range of banking services including commercial and consumer banking, treasury operations, and branch-based services, with a market capitalization of ₱26.33 billion.
Operations: The primary revenue streams for Asia United Bank are derived from branches, commercial banking, treasury operations, and consumer banking. The bank's net income margin has shown a notable upward trend, reaching 56.02% as of March 31, 2025. Operating expenses are predominantly comprised of general and administrative costs.
PE: 4.9x
Asia United Bank, a smaller player in the financial sector, is drawing attention with its recent strategic moves and insider confidence. In August 2026, they approved a significant increase in authorized capital stock from PHP 14.7 billion to PHP 72.5 billion, aligning with expansion goals. Insider activity showed Ann Lorenzo purchasing 9,500 shares for approximately PHP 477,850 in October 2026, indicating belief in the bank's potential. Earnings reports reveal steady growth with net income reaching PHP 2.99 billion for Q2 and improved earnings per share from continuing operations at PHP 2.07 compared to last year’s figures.
A & W Food Services of Canada (TSX:AW)
Simply Wall St Value Rating: ★★☆☆☆☆
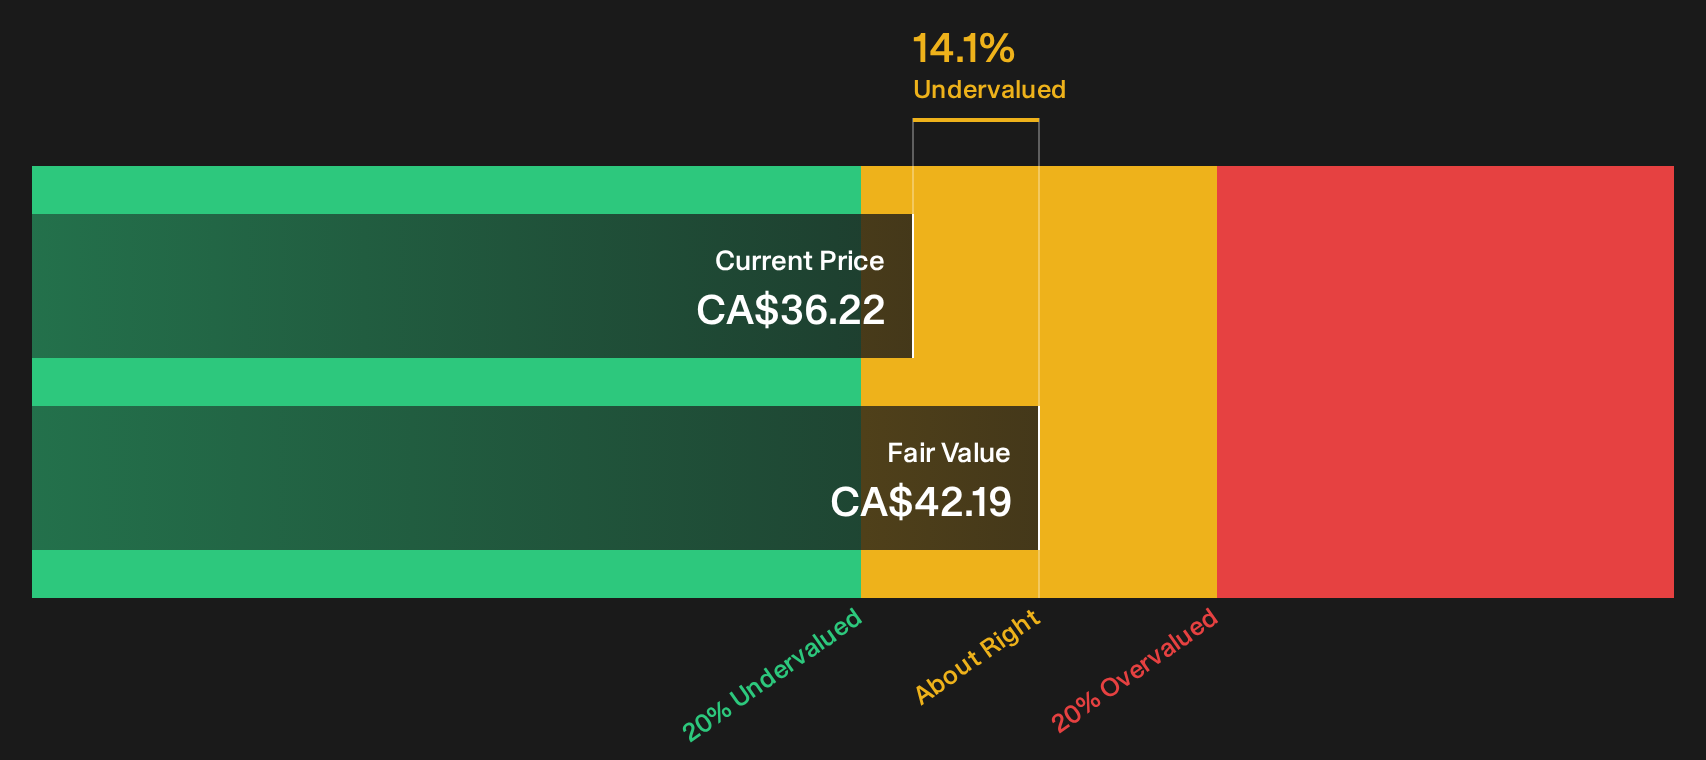
Overview: A & W Food Services of Canada is engaged in developing and franchising quick-service restaurants, with a focus on the Canadian market, and has a market cap of approximately CA$1.41 billion.
Operations: The company generates revenue primarily from developing and franchising quick-service restaurants, with recent figures reaching CA$302.47 million. Over the observed periods, the gross profit margin has demonstrated variability, peaking at 48.81% in late 2025. Operating expenses have fluctuated but generally remain a significant portion of the cost structure, impacting net income margins which have shown variation as well.
PE: 15.1x
A&W Food Services of Canada, a smaller company in the restaurant industry, recently reported third-quarter revenue of C$79.26 million, up from C$71.21 million last year, with net income rising to C$19.19 million from C$17.12 million. Despite high debt levels and reliance on external borrowing for funding, earnings are projected to grow annually by 6.84%. Insider confidence is reflected in strategic leadership changes with Catherine Anderson's promotion aimed at expanding restaurant operations nationwide as part of their growth strategy starting November 2026.
Key Takeaways
- Explore the 116 names from our Undervalued Global Small Caps With Insider Buying screener here.
- Got skin in the game with these stocks? Elevate how you manage them by using Simply Wall St's portfolio, where intuitive tools await to help optimize your investment outcomes.
- Elevate your portfolio with Simply Wall St, the ultimate app for investors seeking global market coverage.
Ready For A Different Approach?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com