


- Avis Budget Group has extended its Avis First premium rental service to London Heathrow and Paris Charles de Gaulle, adding concierge-led, app-only vehicle delivery and return to two of Europe’s busiest airports.
- This move deepens Avis Budget Group’s push into higher touch, premium rentals that rely on app-based coordination, curated low-mileage fleets and fuel-on-return pricing, which together reshape its operating mix toward service intensity rather than pure volume.
- We will look at how Avis Budget Group's investment narrative is influenced by Avis First’s expansion into Heathrow and Charles de Gaulle.
Scan how Avis Budget Group’s premium push compares with other travel and mobility operators by reviewing our curated list of 21 high quality undiscovered gems.
Avis Budget Group Investment Narrative Recap
To own Avis Budget Group, you need to believe that a tighter, higher value rental mix and better use of technology can turn a currently loss making business into something more resilient. The extension of Avis First into Heathrow and Charles de Gaulle supports that thesis on paper, although the impact on near term earnings is likely modest compared to group wide fleet and pricing decisions.
The more immediate swing factor remains how effectively management manages recall related downtime and costs while operating with high net leverage of 7.4x. Any further hit to utilization or cash flow would matter more in the short run than incremental premium locations, especially with interest coverage already flagged as a weak point.
The most relevant recent development for this news is the broader rollout of Avis First, which analysts already linked to higher revenue per day and better margins at a 36 location scale. Heathrow and Charles de Gaulle add volume to that experiment and give the premium service exposure to major international traffic flows and more demanding corporate travelers.
For catalysts, the question is whether premium, app only rentals plus tighter fleets and connected car initiatives can offset recall costs, legal spend and higher interest outlays. Execution risk is real, particularly with a relatively new management team and ongoing class actions, so the premium expansion reads as an operational proof point rather than a solved equation.
Avis Budget Group Forecasts Behind the Premium Push
Avis Budget Group's narrative projects US$12.1b revenue and US$592.8m earnings by 2029. This implies 1.2% yearly revenue growth and an earnings swing of about US$1.23b from a current loss of US$636.0m to the 2029 consensus figure.
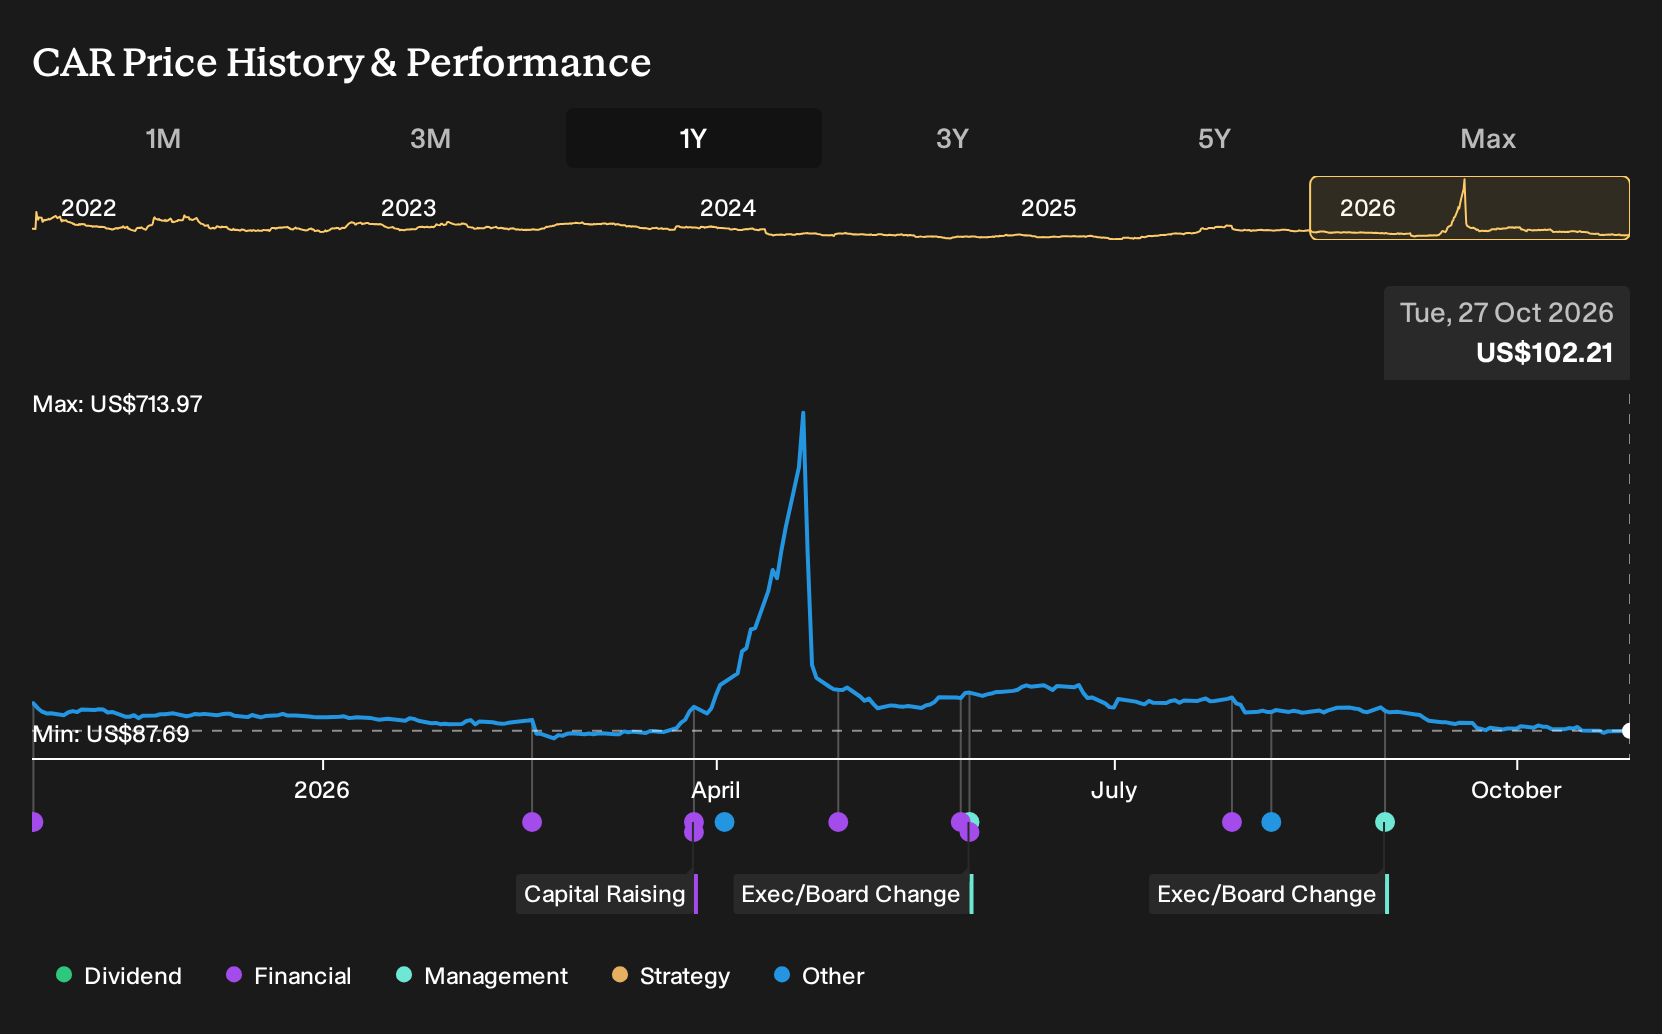
Uncover why Avis Budget Group's fair value indicates a 20% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Bullish analysts focus on one thing for Avis Budget Group: they see premium services like Avis First as the swing factor. Before this Heathrow and Paris expansion, the most optimistic forecasts already pencilled in US$12.5b revenue and US$666.4m earnings by 2029. That is far above the consensus view, and these fresh developments could still reshape both narratives.
Explore 2 other Avis Budget Group fair value estimates, including one that suggests potential upside of as much as 236% from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Avis Budget Group research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Avis Budget Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Avis Budget Group's overall financial health at a glance.
Looking for more investment ideas beyond Avis Budget Group?
If the Avis Budget Group story has sharpened your thinking but you want a wider watchlist, a structured screener can help you sort through opportunities quickly by quality, risk profile, and balance sheet strength.
- For investors who care about quality at a reasonable entry point, scan a curated set of opportunities through the 29 high quality undervalued stocks.
- If capital preservation comes first for you, focus on businesses that score well on stability and risk controls using the 30 resilient stocks with low risk scores.
- When financial resilience is near the top of your checklist, filter for companies with cleaner leverage metrics and liquidity using the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com