


War-driven bottlenecks in the Strait of Hormuz, higher U.K. inflation at 3.5% and talk of fresh Bank of England rate hikes are reshuffling the odds for domestically focused shares. Some British stocks could see their cash flows squeezed, while others may benefit from resilient demand and a more cautious budget. This article walks through 3 UK Domestic-Focused Defensive Equities from our screener that appear better positioned given this backdrop.
The three stocks highlighted below are only a starting sample, and the full screen surfaced 7 more domestically focused companies with equally compelling stories that are not covered here. To identify and analyze the highest conviction defensive ideas for your own watchlist, head straight into the UK Domestic-Focused Defensive Equities screener.
Tristel (AIM:TSTL)
Tristel supplies infection prevention products that plug directly into the UK healthcare system. This aligns with the defensive theme where hospitals and clinics tend to keep spending even when other sectors pull back.
Tristel focuses on infection prevention, with around £45 million from hospital medical device decontamination and about £4.7 million from hospital environmental surface disinfection, alongside smaller other income, and carries a market value near £196 million.
"Strategically, the company’s regulatory progress and expansion into large overseas markets, including the United States following FDA approval, could open a significant new revenue opportunity over the coming years."
What matters from here is how one quiet shift in its earnings mix shapes investor confidence in those defensive cash flows.
That shift in mix is the real story, and the full narrative for Tristel lays out how Tristel’s overseas push, pricing power and risks could be decoupling from headline U.K. pressures.

Admiral Group (LSE:ADM)
Admiral Group is a UK-centred personal lines insurer that fits the domestic defensive theme through recurring motor and household premiums. Most revenue comes from UK Insurance at about £4.4b, alongside £689 million from European Insurance and £110 million from Other, supporting a roughly £11.6b market value.
For investors hunting resilient, home-market cash flows, Admiral Group offers a straightforward story built on car and home cover that most households treat as non-negotiable, even when inflation is biting and rates are rising.
"Investors expect Admiral Group's investment in advanced data platforms, machine learning and generative AI to support disciplined underwriting and drive further benefits to underwriting margins and earnings as these tools are rolled out more widely."
The real test now is how one less visible pressure on its motor book shapes pricing power and keeps those defensive margins intact.
If that pressure point has your attention, the full narrative for Admiral Group shows how Admiral Group’s data engine, capital discipline and pricing levers could be quietly reshaping the story.

Nichols (AIM:NICL)
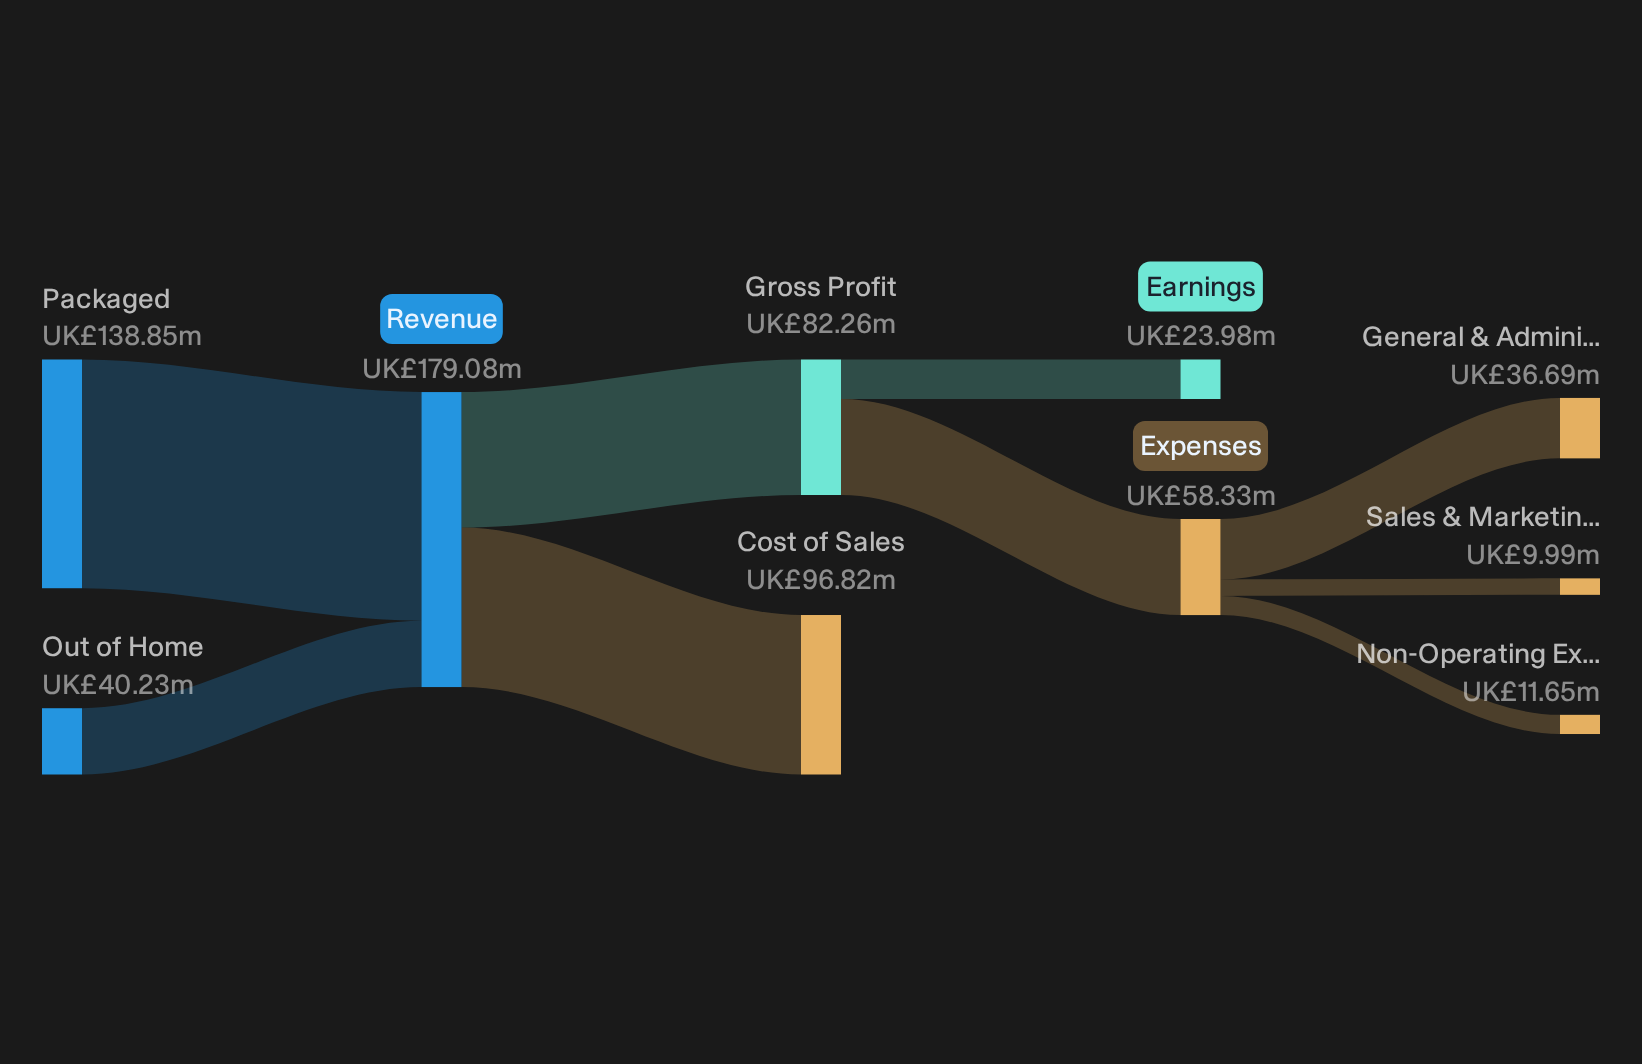
Nichols is a UK headquartered soft drinks group that fits the domestic defensive theme through everyday staples on supermarket shelves and in leisure venues. The business generated about £138.8 million from Packaged drinks and £40.2 million from Out of Home, and carries a market value near £395 million.
Nichols gives you exposure to a familiar basket of squashes, fizzy drinks and frozen treats that are bought frequently, often out of habit. This is exactly the sort of behaviour this defensive screen is looking to capture.
"Expansion of Ramadan themed activity in the Middle East, where Nichols reports value growth ahead of the wider market, can support further premiumisation of cordial and concentrate formats and lift revenue and earnings from that region."
What really matters is how one quiet shift in where Nichols earns its highest quality profits influences pricing power, margins and investor patience.
That profit mix is the real pivot, and the full narrative for Nichols maps how Nichols’ overseas momentum, pricing muscle and brand strength could be masking a much richer earnings story.
Seeking Alternatives Before Everyone Else?
Fresh ideas can move fast. By the time a breakout is obvious, the first wave of momentum may already be flying. Scan these under the radar for now picks and act now.
- Spot cash generative businesses before sentiment catches up by running the 10 high quality undervalued stocks while pricing dislocations still matter and expectations remain muted.
- Ride real cash flows in AI instead of hype by filtering for the 39 profitable AI stocks that aren't just burning cash before valuations get fully caught by late arrivals.
- Screen for income opportunities while yields are elevated by using the 5 dividend fortresses before payout trends change and prices adjust.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com