


- Everforth, Inc. announced a new partnership with WisdomAI, Inc. that adds Agentic Analytics, conversational business intelligence, and Live Apps to Everforth’s AI analytics services for its Fortune 1000 customer base.
- This agreement gives Everforth a way to connect fragmented enterprise data to WisdomAI’s governed context and metrics layer, which could influence how clients weigh Everforth’s consulting led AI pitch against rival IT service providers.
- We will now look at how Everforth's investment narrative could be affected by deeper AI analytics access through WisdomAI.
Scan how Everforth’s AI push compares with other enterprise-focused plays by reviewing the hand picked 55 AI infrastructure stocks that could also be positioned for rising data and analytics demand.
Everforth Investment Narrative Recap
To own Everforth, you need to believe its pivot toward higher value consulting, AI and cloud work can turn a 2.1% net margin into something more resilient, while managing debt that is not well covered by operating cash flow. The WisdomAI partnership fits that story by deepening AI analytics offerings, but does not remove balance sheet or execution risk.
In the near term, the main catalyst is how Q3 2026 results on 28 October line up with expectations for steady revenue and earnings after a year of earnings pressure and one off losses. The biggest risk is that large AI and modernization projects take longer to convert from backlog and partnerships into consistent profit.
The WisdomAI announcement matters most because it plugs directly into Everforth’s existing AI and data focused consulting pipeline, including prior wins like SUNet 2.0 and Defense Health Agency work. Those contracts already lean on complex data, cloud and cybersecurity needs, which are exactly where governed analytics and conversational intelligence can be applied.
What investors should watch now is whether this AI partnership shows up in consulting bookings, federal awards catching up to billings, and any commentary on pricing for higher complexity projects during the Q3 call. If management can tie WisdomAI powered solutions to larger, repeatable offerings with partners such as Microsoft or Databricks, it could influence how durable the current margin and earnings forecasts look.
Everforth’s Long Range Assumptions And Valuation Setup
Everforth’s AI heavy consulting story now sits on top of a set of fairly specific analyst assumptions that give you a sense of how much needs to go right for the WisdomAI deal and other initiatives to matter financially.
On the top line, the consensus view points to Everforth’s revenue rising by 2.4% each year over the next three years, paired with an uplift in net margin from 2.1% today to 3.5% by around 2029. That combination frames the kind of mix shift the company is trying to achieve as more work tilts toward complex data, cloud and AI projects rather than lower margin staffing.
Earnings expectations are more detailed. Analysts are looking for profit to reach US$149.0 million by about 2029, compared with US$83.0 million today, with forecasts spread widely between US$120.1 million on the low end and US$222.8 million at the top. The gap between the bullish and bearish cases underlines how uncertain the earnings impact of AI led contracts, cost programs and federal timing still is.
The current analyst framework assumes that by 2029 Everforth would be generating US$4.3 billion of revenue and US$149.0 million of earnings and trading on a P/E of 11.3x, versus 18.9x today and a US IT industry P/E reference point of 21.7x. That setup effectively bakes in some improvement in profit quality and scale, while also assuming investors would pay a lower multiple than they do now.
Everforth's narrative projects US$4.3 billion revenue and US$149.0 million earnings by 2029. This implies 2.4% yearly revenue growth and an earnings increase of about US$66.0 million from US$83.0 million today.
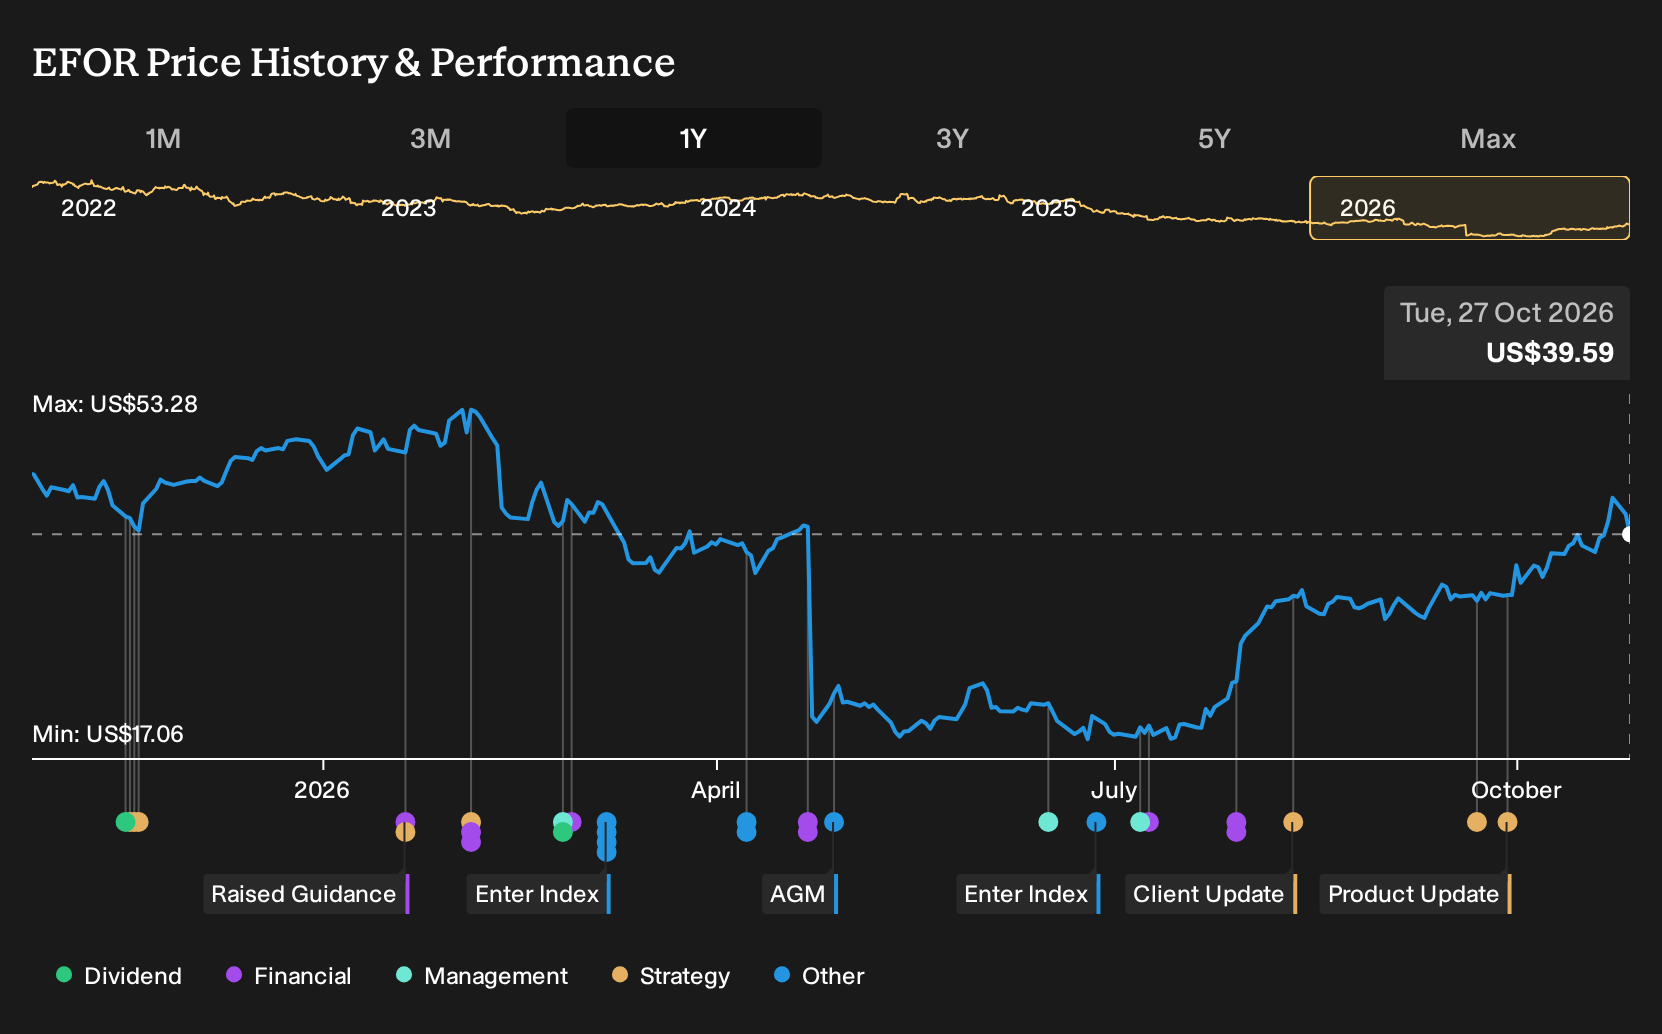
For readers tracking the stock directly, the current share price of US$38.36 sits above the consensus target of US$32.67, which is 17.4% lower. Analysts are effectively saying the market already prices in better operations, including higher margin AI consulting and cleaner execution on contracts like SUNet 2.0, than their base case models support.
That disconnect matters when you think about how much incremental benefit the WisdomAI partnership needs to deliver. If Everforth eventually reports bookings, margins or federal catch up that align more with the bullish earnings band closer to US$222.8 million, today’s valuation debate looks different from a scenario where profit trends stay pinned nearer the cautious US$120.1 million case.
Uncover why Everforth's fair value indicates a 17% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
You now have two very different stories on Everforth. The bullish camp was modelling roughly US$4.4b of revenue and US$222.4 million of earnings by 2029 before this WisdomAI news, far above the cautious US$4.3b and US$149.0 million baseline. If you compare both, you can judge how this fresh AI deal might shift those views.
Explore another Everforth fair value estimate, including one that suggests potential upside of up to 93% from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Everforth research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Everforth. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Everforth's overall financial health at a glance.
Looking For More Investment Ideas Beyond Everforth?
If Everforth’s AI story has you thinking about portfolio gaps, it can help to line it up against other companies with different strengths, balance sheets, and income profiles. The Simply Wall St screener sets let you quickly filter for traits that match your own risk tolerance and return goals instead of relying only on one stock’s narrative.
- For readers who want potential value upside with quality fundamentals, start by comparing Everforth against a broader 29 high quality undervalued stocks that already clear basic balance sheet and cash flow checks.
- If capital preservation sits higher on your priority list than chasing maximum gains, consider a basket of 30 resilient stocks with low risk scores that screen well on volatility, financial strength, and risk scores.
- Those looking for less crowded opportunities can scan a curated pool of 21 high quality undiscovered gems that pair solid fundamentals with relatively lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com