


- CTS Corporation reported third quarter 2026 sales of US$149.58 million and net income of US$17.76 million, with both basic and diluted earnings per share from continuing operations higher than a year earlier.
- The business also raised its full year 2026 sales guidance range to between US$580 million and US$590 million, which indicates management confidence in current demand and execution despite recent cost and end market pressures highlighted by analysts.
- The focus now shifts to how CTS Corporation’s higher full year sales guidance might reshape the existing investment narrative built around margin mix.
CTS Investment Narrative Recap
To stay invested in CTS, you need to be comfortable with a story built around steady execution rather than step change growth. The thesis leans on a mix shift toward medical, industrial, aerospace and defense customers, and the ability to keep gross margins supported while transportation demand and input costs remain swing factors.
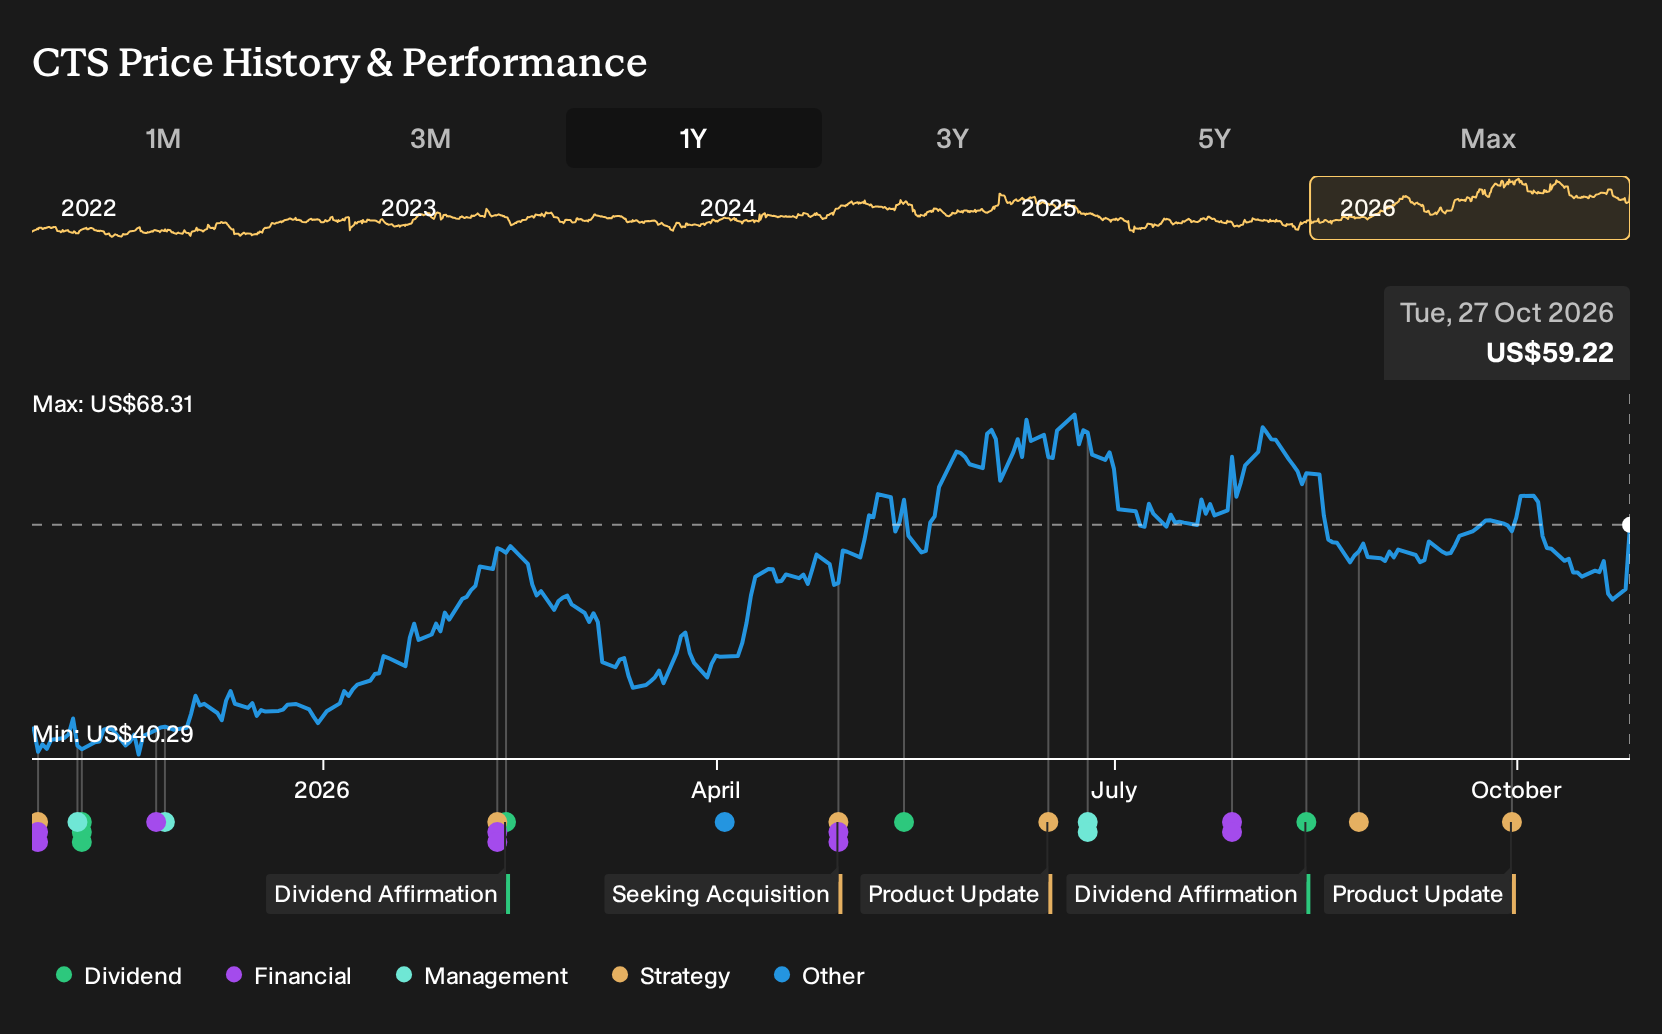
The latest quarter, with US$149.58 million in sales and US$17.76 million in net income, and the higher 2026 sales guidance, point to operating momentum in the near term. For now, the key catalyst remains continued margin resilience. The main risk is that transportation softness and raw material costs start to eat into those margins.
The most relevant update right now is CTS lifting its 2026 sales outlook to US$580 million to US$590 million. Management tied that to current market conditions, so you are effectively watching whether order flow in higher margin segments can stay firm enough to support this tighter, higher range.
If that guidance holds, it supports the idea that recent investments in sensors, actuators and diversified end markets are translating into ongoing demand. If it needs to be cut, the concern would be that transportation headwinds or cost pressures are proving harder to offset, which would put more scrutiny on execution and pricing power in CTS’s core franchises.
What The CTS Forecasts Are Asking You To Believe
CTS' narrative projects US$653.5 million revenue and US$98.3 million earnings by 2029. This implies 5.0% yearly revenue growth and an earnings increase of about 41% from US$69.8 million today.
Uncover why CTS' fair value indicates a 19% potential upside to its current price before that discount gap closes.
Exploring Other Perspectives
Fair value estimates for CTS in the Simply Wall St Community span from about US$70.67 to US$84.97 across 2 separate views, so you are seeing very different expectations sitting under the same ticker. Set that against transportation softness, cost pressure risks and recent guidance, and you get sharply diverging judgments on future execution. Expect wide disagreement. Explore those alternate takes before firming up your own stance.
Explore another CTS fair value estimate, including one that suggests as much as 43% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your CTS research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for CTS. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CTS' overall financial health at a glance.
Looking For More Ideas Beyond CTS?
If you want to stress test your CTS view against what else is out there, it helps to line it up against other companies with clear fundamentals and different risk profiles. The Simply Wall St Screener lets you do that quickly by filtering for quality, balance sheet strength, and income potential in a structured way.
- If you are hunting for mispriced quality, start by scanning a focused set of 29 high quality undervalued stocks that combine solid fundamentals with room for sentiment to catch up.
- If capital preservation ranks high for you, compare CTS with a curated group of 30 resilient stocks with low risk scores that score well on financial strength and earnings stability.
- If you want to lean on income rather than price moves alone, weigh CTS against a field of 5 dividend fortresses that aim to pair higher yields with more resilient cash generation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com