


- Computacenter reported FY25 adjusted diluted EPS growth of 9.5% with gross invoiced income growth of 32% in constant currency and later raised its FY26 profit outlook to adjusted PBT of at least £425 million, supported by a record committed product order backlog that reached £12.6 billion by the end of the third quarter of 2026.
- The surge in Computacenter's backlog, which climbed to £12.6 billion and was heavily influenced by hyperscale and AI compute demand in North America and the U.K., highlights how critical large cloud and AI infrastructure buyers have become to the group's technology sourcing and services pipeline.
- We now examine how Computacenter's upgraded profit outlook, anchored by a hyperscaler-driven AI order book, reshapes its investment narrative.
Scan beyond Computacenter's AI build out and see how other suppliers to this spending wave stack up with our curated 55 AI infrastructure stocks
What Is Computacenter's Investment Narrative?
The big picture for a shareholder in Computacenter is about believing this IT services group can keep turning hyperscaler hardware demand into repeat services work without overextending itself. The fresh FY26 adjusted PBT outlook of at least £425 million, backed by a £12.6b order backlog, points to strong visibility on near term activity. That order book also brings execution questions. Delivery, integration and support need to keep up with a surge in AI compute rollouts across North America and the U.K., or customer satisfaction and pricing power can come under pressure.
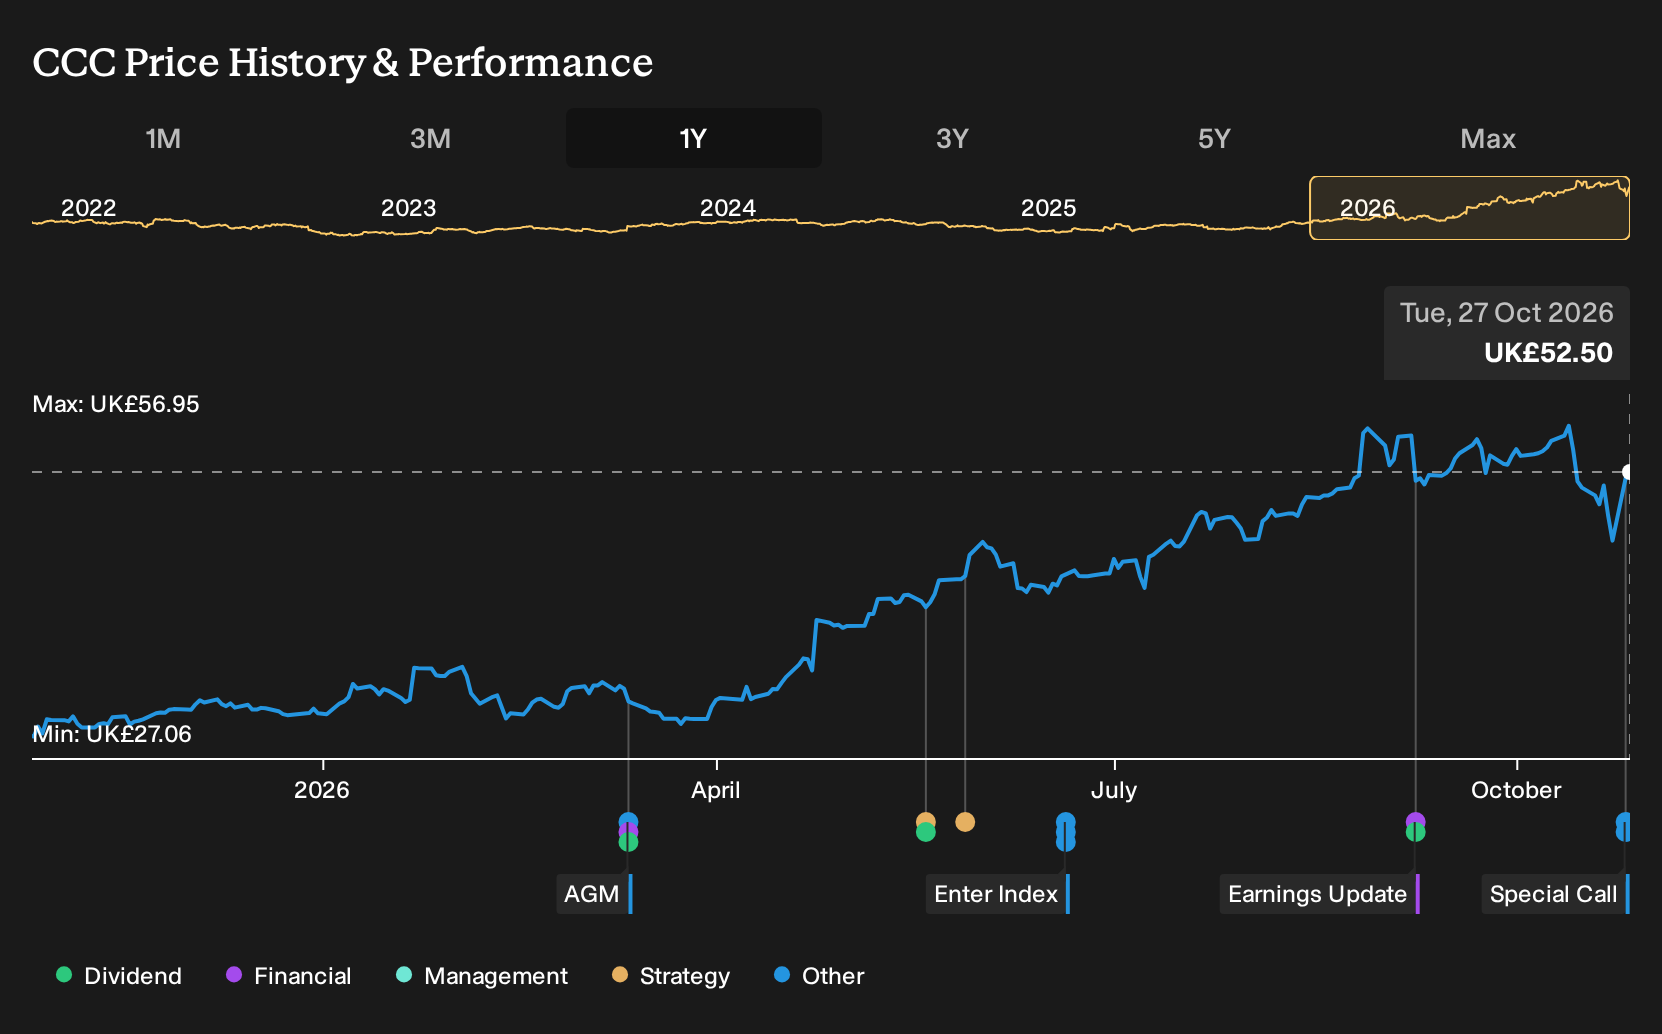
In the short term, the key catalysts are whether that hyperscaler heavy pipeline converts into revenue and cash on the timetable management expects, and whether professional services keep tracking higher alongside technology sourcing. Capital needs matter here, because large AI infrastructure contracts can be working capital hungry if inventory and receivables build faster than cash inflows. Valuation is less extreme given the pullback over the past month, and the stock still sits below some analyst targets, but the share price already reflects strong execution and growth forecasts around 12% earnings expansion per year.
Yet there is a less obvious pressure point inside this AI backlog story that could change the appeal of Computacenter shares if ...
There's only one way to know the right time to buy, sell or hold Computacenter. Head to Simply Wall St's company report for the latest analysis of Computacenter's Fair Value.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster tightly between £62.67 and £63.19 per share, which shows how closely those contributors group their expectations for Computacenter. Those views were formed before the upgraded profit outlook and record £12.6b backlog, so use them as a starting point and compare several fresh perspectives.
Explore another Computacenter fair value estimate, including one that suggests it could be worth just £62.67.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Computacenter research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Computacenter. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Computacenter's overall financial health at a glance.
Looking For More Investment Ideas Beyond Computacenter?
Once you have formed a view on Computacenter, it can help to compare that thesis with other opportunities that match your preferred balance of risk, quality and income potential. The Simply Wall St Screener surfaces groups of companies that share similar financial traits so you can quickly build a wider watchlist that fits your style.
- For investors hunting for companies that appear mispriced relative to their fundamentals, scan through our 10 high quality undervalued stocks and see which ones warrant a closer look.
- If resilience and balance sheet strength are high on your checklist, filter for businesses in the list of solid balance sheet and fundamentals (10 results) to spot those with more robust financial footing.
- When you want growth potential with a twist of scarcity value, sort through the 5 high quality undiscovered gems and see which ideas deserve a spot on your radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com