


- BlackBerry has added legal and investment executive David Chaikof to its Board, expanding it to nine directors, eight of whom are independent, while continuing to push QNX software deeper into industrial automation and robotics for factories and warehouses.
- The combination of a long time external counsel joining the board and a stronger focus on software defined factories highlights how BlackBerry is tying governance expertise directly to its push into higher complexity, safety critical software markets.
- Attention now turns to how BlackBerry's investment narrative might shift as this board appointment supports its push into industrial automation software.
Scan beyond BlackBerry and line up other factory focused automation plays using our hand picked list of 94 robotics and automation stocks.
BlackBerry Investment Narrative Recap
To own BlackBerry today, you need to believe its mix of QNX safety software and Secure Communications can keep turning into higher quality earnings, not just headlines around new verticals like industrial automation and robotics. The key near term swing factor is execution on software defined factory wins and converting its QNX backlog into predictable revenue.
The biggest operational risk sits in execution complexity. BlackBerry is stretching QNX further into safety critical roles in factories and humanoid robotics while also running a Secure Communications segment that depends on recurring government and enterprise contracts. The new director appointment supports governance but does not materially change that near term risk reward balance.
The most relevant recent development is BlackBerry leaning harder into industrial automation and robotics, funded by cash flow from its Secure Communications arm and supported by a record QNX royalty backlog. That shift links directly to what David Chaikof brings: deep M&A and governance experience in complex, regulated software arenas.
For catalysts, investors are watching whether QNX can convert warehouse and factory wins into recurring royalties while Secure Communications maintains contract momentum with governments. The board refresh, including Chaikof, may help oversight around capital allocation and any future partnerships in these areas, but operational delivery on deployments and safety certifications remains the real test.
What The Current BlackBerry Forecasts Assume
BlackBerry's narrative projects $807.3 million in revenue and $170.7 million in earnings by 2029. This reflects analysts factoring in 9.6% yearly revenue growth and an earnings increase of about $90.3 million from $80.4 million today.
Uncover why BlackBerry's fair value indicates a 5% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
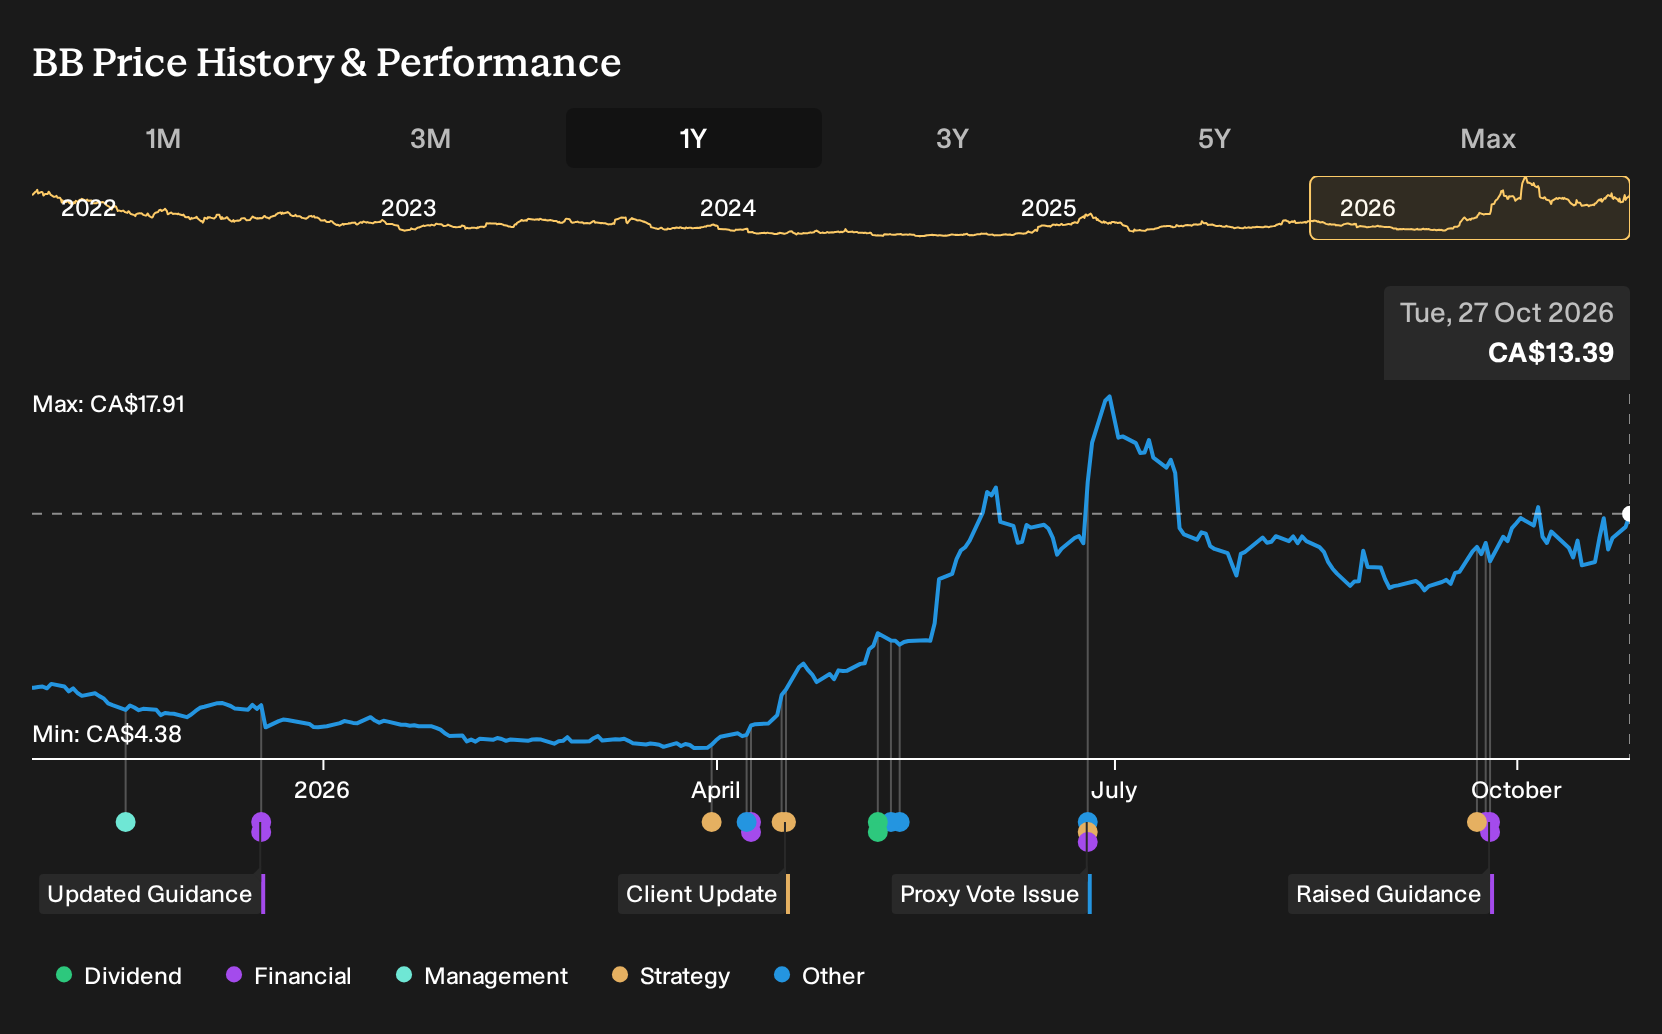
You might see this BlackBerry board move through a very different lens if you focus on the bearish catalyst around higher QNX and M&A spending. The most cautious analysts were pencilling in $832.6 million of revenue and $162.7 million of earnings for 2029 before this news, and their lower CA$9.32 target shows how sharply opinions can diverge. Treat this appointment as a reason to compare those more pessimistic forecasts with your own view on how governance, spending and industrial automation plans may interact from here.
Explore 3 other BlackBerry fair value estimates, including one that suggests as much as 5% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your BlackBerry research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for BlackBerry. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate BlackBerry's overall financial health at a glance.
Looking for more ideas beyond BlackBerry?
If you want to pressure test your BlackBerry thesis, one of the quickest ways is to compare it with other opportunities that share the same qualities you care about, whether that is value, balance sheet strength, or lower risk profiles.
- For investors who want quality at a sensible entry point, compare BlackBerry against our curated group of 3 high quality undervalued stocks that combine fundamentals with pricing that may appeal to value focused portfolios.
- If capital preservation and resilience matter most to you, broaden your watchlist with a 8 resilient stocks with low risk scores that scores well on our internal risk checks.
- When you care about financial robustness first and returns second, weigh BlackBerry alongside a list of solid balance sheet and fundamentals (7 results) to see how its capital structure compares with financially sturdy peers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com