


Plexus (PLXS) is back in focus as the electronic manufacturing services group prepares to release its Q4 2026 earnings today after the market close, an update that is closely watched following its prior revenue beat.
Plexus has ridden a strong upswing this year, with a year to date share price return of 51.28% and a 1 year total shareholder return of 60.28%. However, the 30 day share price return declined 12.47%, hinting that momentum has cooled ahead of today's Q4 update.
Compare Plexus with a hand picked pool of peers by scanning the list of solid balance sheet and fundamentals (24 results) that may also draw attention around earnings season.
The share price surge over the past year and the recent pullback pull investors in two directions. Is Plexus still priced for upside, or have most of the easy gains already been captured in this run, making valuation the real test now?
Most Popular Narrative: 24% Undervalued
The most widely followed Plexus narrative anchors fair value at $304.60, above the last close of $230.29. This puts execution risk and cash conversion in sharp focus ahead of tonight's Q4 release.
The main factor that has to go right is that Plexus converts its record funnel and new program wins in sectors like aerospace, defense, industrial automation and data center power into sustained revenue growth, while maintaining non-GAAP operating margins above 6% and disciplined cash cycle performance.
The bullish case relies heavily on converting a record qualified manufacturing funnel, expanding capacity in Malaysia and maintaining a best in five years cash cycle.
See why 2 investors see Plexus as 24% undervalued.
Result: Fair Value of $304.60 (UNDERVALUED)
Still, heavy insider selling, together with the risk of softer program wins or slower funnel conversion, could quickly challenge the Plexus undervaluation story.
Find out about the key risks to this Plexus narrative.
Another View On Plexus Valuation
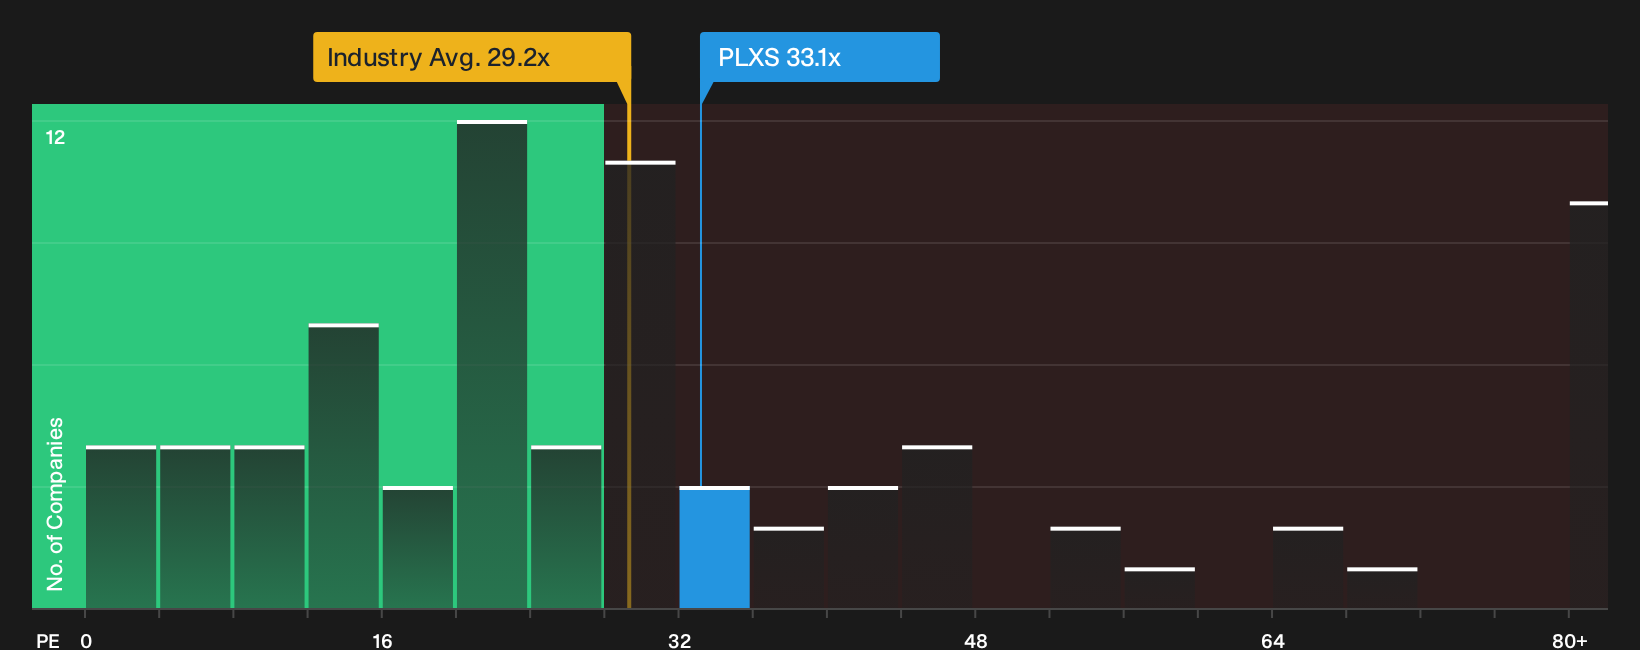
The first narrative leans on analyst targets that frame Plexus as 24% undervalued. A different lens looks at the current P/E of 33.1x versus a fair ratio of 28.5x, the US Electronic industry on 28.7x and peers on 56.5x. That mix suggests investors face both a valuation cushion and premium risk. Which signal matters more to you right now?
To pressure test this P/E story against detailed assumptions and cash flow scenarios, take a look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment on Plexus may feel mixed after such a strong run and a recent pullback, so move fast, inspect the data and shape your own stance. To understand why some investors are still optimistic, start with the 4 key rewards.
Looking For More Investment Ideas Beyond Plexus?
If Plexus has you thinking about what else might be hiding in plain sight, use screeners to quickly surface other opportunities that could fit your playbook.
- Target quality at a discount and scan a curated set of companies trading below their estimated worth with the 29 high quality undervalued stocks.
- Prioritise resilience over drama and review a focused group of businesses with stronger balance sheets using the list of solid balance sheet and fundamentals (24 results).
- Hunt for early stage potential and filter through a tighter pool of smaller, under the radar candidates via the 7 elite penny stocks with strong financials.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com