


Dallas, Texas-based Copart, Inc. (CPRT) provides online auctions and vehicle remarketing services in the United States and internationally. The company has a market cap of $27 billion and offers a range of services to process and sell vehicles over the internet through its virtual bidding, third-generation internet auction-style sales technology. CPRT is expected to release its Q1 2027 earnings soon.
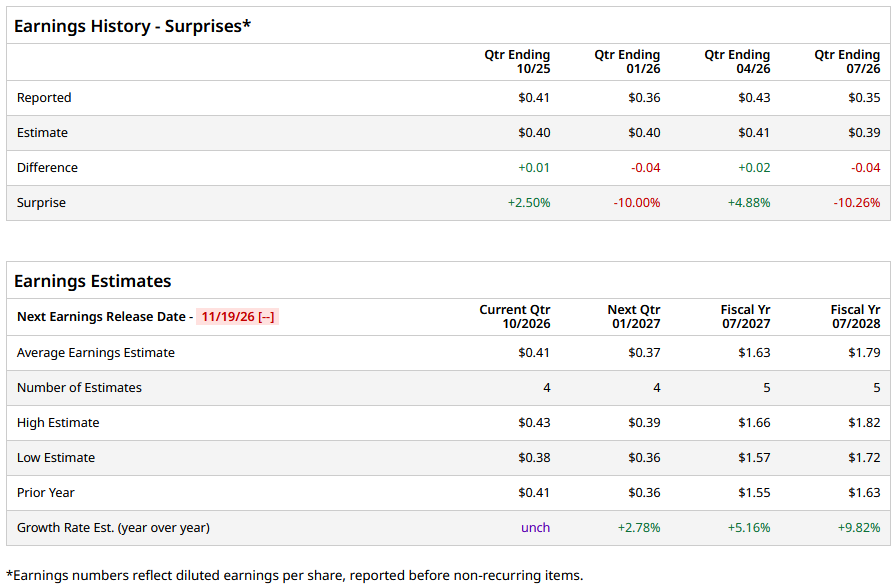
Ahead of the event, analysts expect the company’s EPS to be $0.41 on a diluted basis, unchanged from the year-ago quarter. The company has exceeded Wall Street’s EPS estimates in two of its last four quarters, while missing on two other occasions.
For fiscal 2027, analysts project the company’s EPS to be $1.63, up 5.2% from $1.55 in fiscal 2026. Moreover, its EPS is expected to rise by roughly 9.8% year over year (YoY) to $1.79 in fiscal 2028.
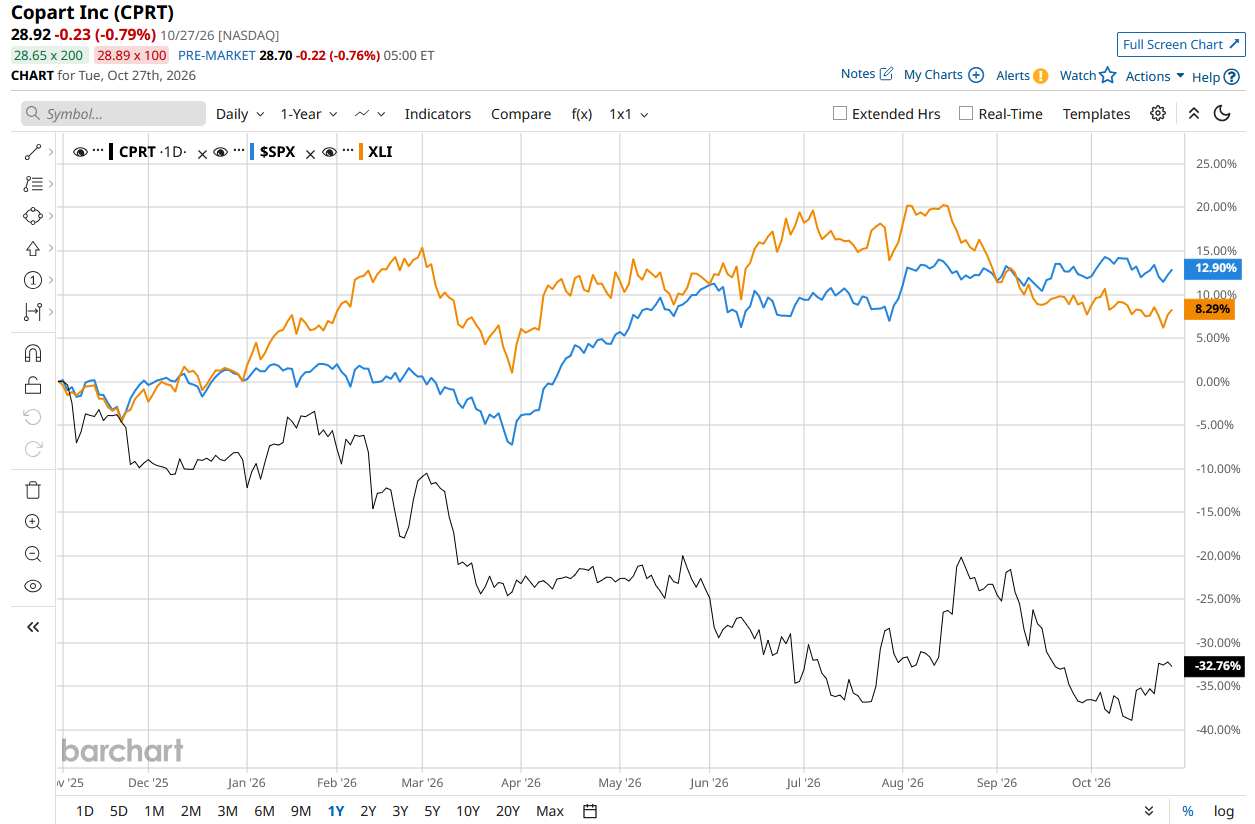
Shares of Copart have declined 34.5% over the past 52 weeks, underperforming the S&P 500 Index’s ($SPX) 12.3% rise and the State Street Industrial Select Sector SPDR ETF’s (XLI) 7.8% rise during the same time frame.
On Sept. 10, CPRT stock fell 4% following the release of its seemingly better-than-expected Q4 2026 earnings. The company’s revenue for the quarter amounted to $1.2 billion, surpassing the Street’s estimates. However, its adjusted EPS came in at $0.35, missing Wall Street’s forecasts. Additionally, the company’s operating margin came in at 32%, also down from the previous year’s quarter, along with its free cash flow margin, indicating issues regarding profitability.
Analysts’ consensus opinion on the stock is moderately bullish, with a “Moderate Buy” rating overall. Of the 12 analysts covering the stock, seven recommend a “Strong Buy,” four suggest a “Hold,” and one recommends a “Strong Sell.” CPRT’s average analyst price target is $41.50, indicating an upside of 43.5% from the current level.
On the date of publication, Aritra Gangopadhyay did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.