


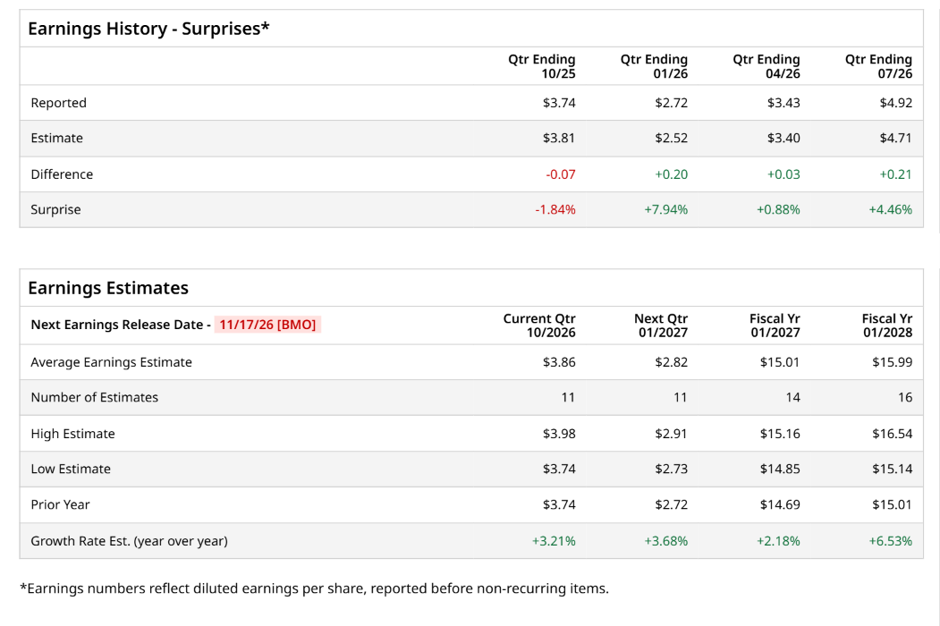
Atlanta, Georgia-based The Home Depot, Inc. (HD) operates as a home improvement retailer. Valued at $318.6 billion by market cap, the company offers a wide range of building materials, home improvement, lawn, and garden products, as well as provides DYI ideas, installation, repair, and other services. The world's largest home improvement specialty retailer is expected to announce its fiscal third-quarter earnings for 2026 before the market opens on Tuesday, Nov. 17.
Ahead of the event, analysts expect Home Depot to report a profit of $3.86 per share on a diluted basis, up 3.2% from $3.74 per share in the year-ago quarter. The company beat the consensus estimates in three of the last four quarters while missing the forecast on another occasion.
For the full year, analysts expect Home Depot to report EPS of $15.01, up 2.2% from $14.69 in fiscal 2026. Its EPS is expected to rise 6.5% year over year to $15.99 in fiscal 2028.
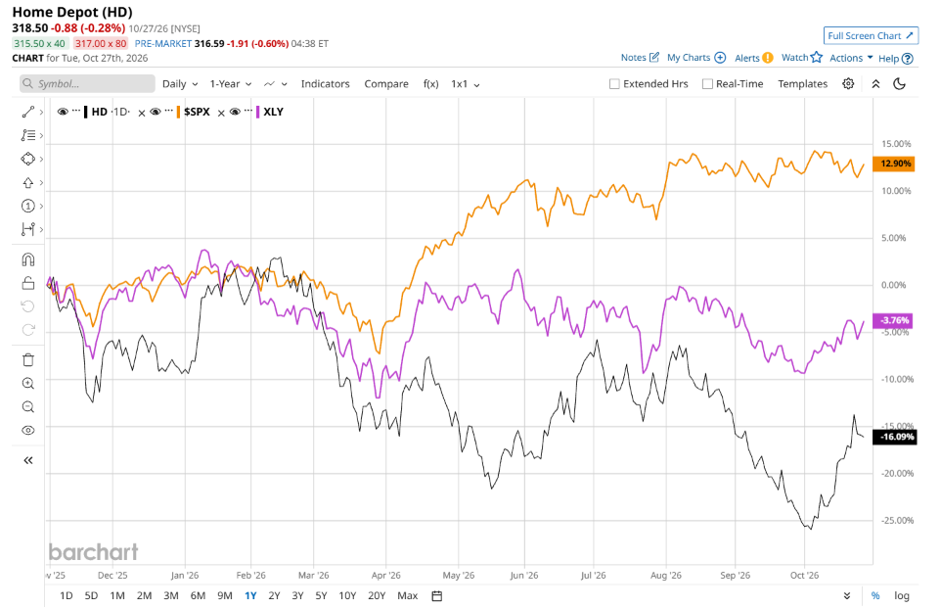
HD stock has underperformed the S&P 500 Index’s ($SPX) 12.3% gains over the past 52 weeks, with shares down 17.3% during this period. Similarly, it underperformed the State Street Consumer Discretionary Select Sector SPDR ETF’s (XLY) 4.2% losses over the same time frame.
Home Depot’s recent quarter highlighted a bifurcated consumer landscape. While shoppers remained willing to fund smaller-scale repair and maintenance tasks, affordability pressures and high mortgage rates severely constrained larger, discretionary renovations. Consequently, overall gains were tempered by a prolonged slump in the housing market and management’s caution that choppy demand for big-ticket projects will likely persist amid elevated home prices and broader economic uncertainty.
Analysts’ consensus opinion on HD stock is reasonably bullish, with a “Moderate Buy” rating overall. Out of 35 analysts covering the stock, 21 advise a “Strong Buy” rating, one suggests a “Moderate Buy,” 12 give a “Hold,” and one recommends a “Strong Sell.” HD’s average analyst price target is $375.24, indicating a potential upside of 17.8% from the current levels.
On the date of publication, Neha Panjwani did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.