


Luckin Coffee has delivered a very strong 112.3% share price gain over the past 5 years, yet the stock has declined over the past year, which puts fresh focus on what investors are really paying for its earnings today. With the price closing at US$31.85 most recently, the key issue is how much of the business performance is already embedded in that tag.
- A 112.3% return over 5 years means long term holders have seen their position more than double, so the market has already priced in a lot of expectations that now need to be weighed against current earnings power.
- The business model relies heavily on turning store level volume into sustainable profitability, which can influence how reliable current earnings are as a guide to what shareholders might reasonably expect in future cash generation.
- Your read on Luckin Coffee is one view; the desks covering it have another. See what analysts think Luckin Coffee's shares could be worth.
The issue now is whether Luckin Coffee's recent share price, after that mix of long term gains and shorter term declines, is justified by the earnings the company currently produces.
To see how Luckin Coffee's earnings based valuation compares with others facing similar scrutiny, line it up against companies in the 29 high quality undervalued stocks.
Is Luckin Coffee Still Cheap on Earnings?
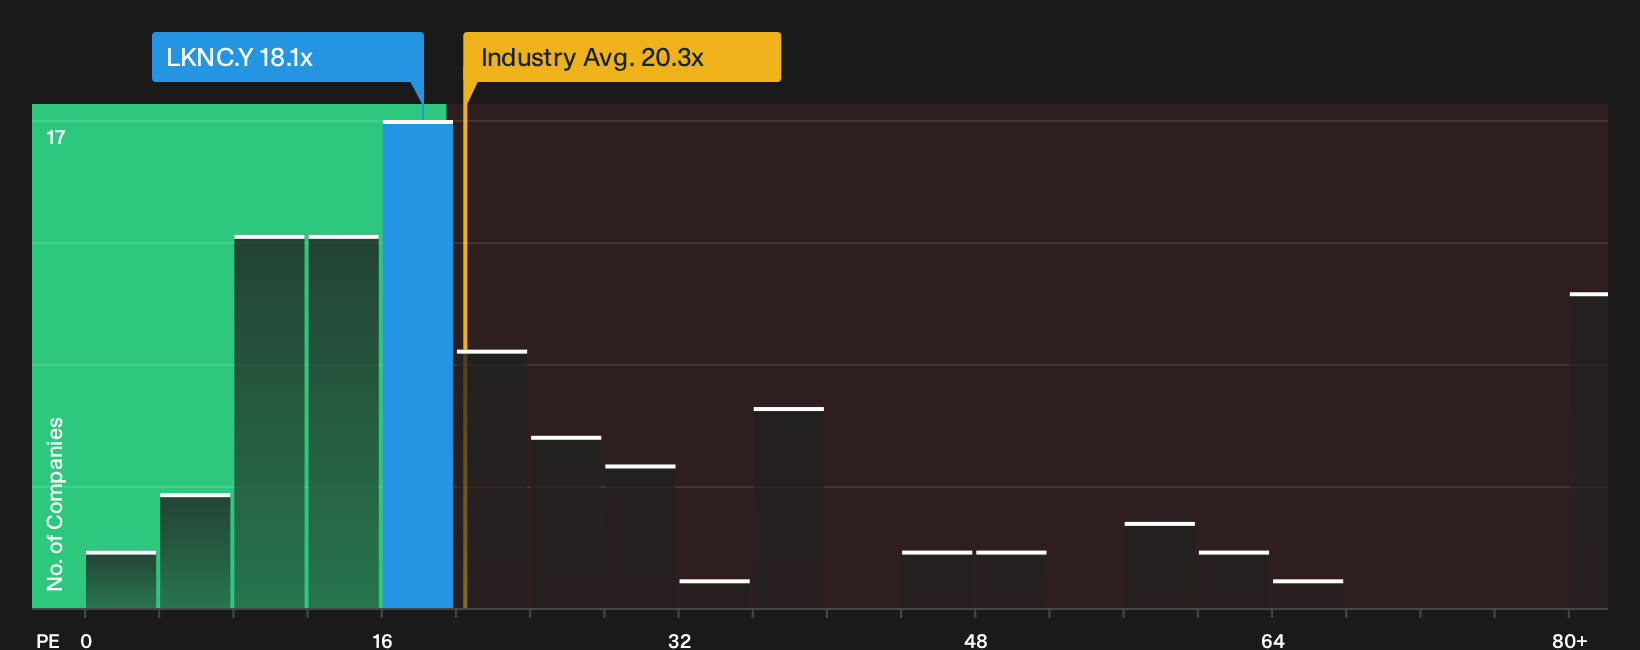
The P/E ratio gives a clear view of what investors are paying for each unit of Luckin Coffee earnings. At about 18.1x, the stock trades below the Hospitality industry average of roughly 20.3x and well below the peer group near 49.2x. That implies a relatively modest price on the profits the business is generating today compared with similar consumer-facing companies.
The valuation model that blends Luckin Coffee growth profile, profitability, size and risk points to a higher P/E as a tailored reference point, which means the current 18.1x sits on the cheaper side of that range. For anyone weighing the recent share price pullback against the earlier multi year gain, this gap suggests the market is not assigning a premium multiple to the existing earnings stream. Explore the numbers behind Luckin Coffee's P/E valuation.
The Luckin Coffee Narrative: What Would Justify Today's Price?
Narratives on Luckin Coffee pick up where the P/E discussion leaves off. They spell out which paths for future growth, margins and earnings would need to play out for today’s valuation to look either stretched or conservative. Where a single ratio or model outputs one figure, these scenario threads unpack the future that figure relies on so you can watch how actual performance lines up with those expectations over time on Simply Wall St’s Community page.
One of the top community narratives on Luckin Coffee: 35% undervalued
"The main factor that has to go right is that Luckin Coffee converts its rapid footprint growth and heavy spending into durable store-level productivity and margins…"
Discover why this Narrative puts Luckin Coffee at 35% undervalued.
One more angle on Luckin Coffee that could change how you read today’s price
Everything so far has focused on what Luckin Coffee earns today, yet analyst projections for where profits might be a few years from now give a different reference point to compare with the current multiple. Explore where analysts expect Luckin Coffee to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com