


Huaneng Power International just dropped its Q3 2026 scorecard, and the story is profits, not headlines. Basic earnings per share printed at ¥0.08 on revenue of ¥58.9b, a steady result in a year when margins have already narrowed and the trailing P/E sits above sector peers. The share price closed today at HK$5.84, roughly flat over the past week and lower over three months. That muted reaction signals investors are still wrestling with one question: Is this profit squeeze a temporary bruise, or the market finally questioning how much to pay for this utility heavyweight?
If you appreciate the steady revenue at Huaneng Power International but are concerned about margin pressure and a higher P/E ratio, consider comparing it with other utilities and income-focused investments in our list of solid balance sheet and fundamentals stocks (207 results)
Q3 2026 Earnings Summary
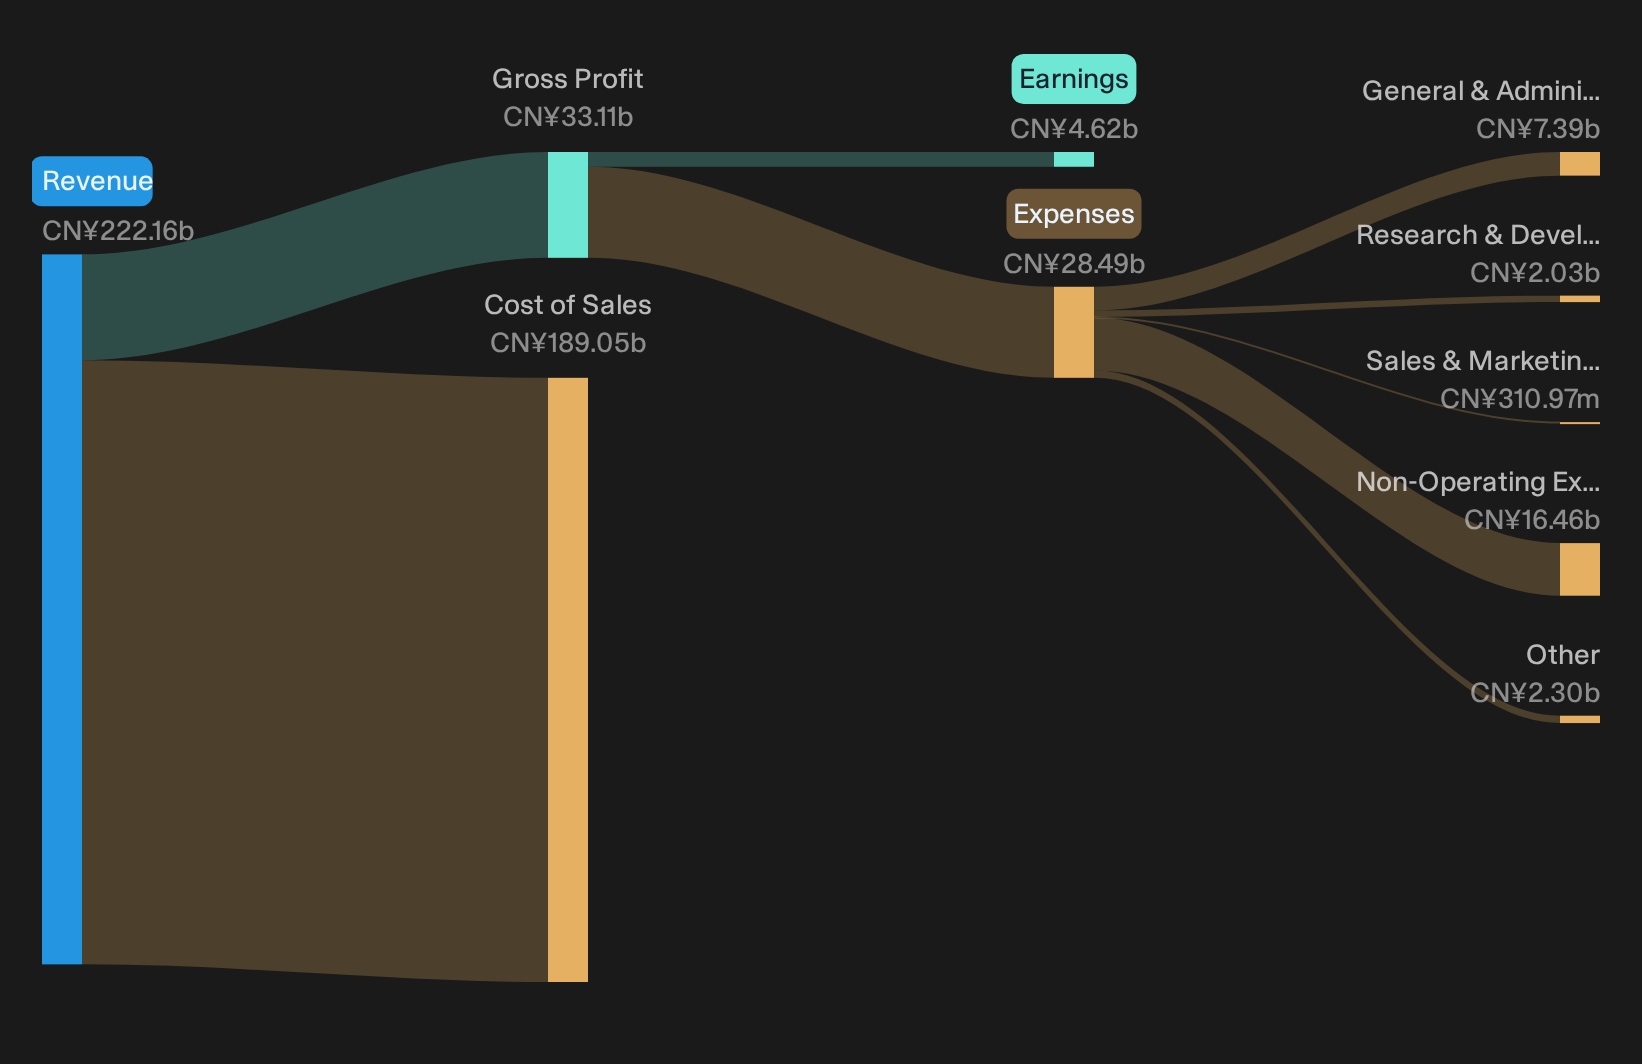
- Revenue (Q3 2026 vs Q3 2025): ¥58,939.6m vs. ¥60,942.8m (a decrease of about 3.3%)
- Net Income (Excl. Extra Items, Q3 2026 vs Q3 2025): ¥2,347.8m vs. ¥6,992.7m (a decline of about 66.4%)
- Basic EPS (Q3 2026 vs Q3 2025): ¥0.0816 vs. ¥0.2967 (a decrease of about 72.5%)
- Trailing Net Profit Margin (Last 12 Months vs Prior Year): 2.1% vs. 5% (a compression of 2.9 percentage points)
Dividend per share rose even as profit fell almost 30%. Ask Charlie what Huaneng Power’s bigger dividend says about 2026.
Huaneng Power International’s Storage And Gas Thesis Under Pressure
The bullish pitch around Huaneng Power International rests on newer assets picking up the slack as older profit engines tire.
"Bullish analysts expect Huaneng Power International to turn its growing low carbon and gas portfolio, including battery storage and higher margin gas units, into a more valuable share of the business over time."
H1 2026 did show building blocks for that claim. Gas fired net profit reached ¥707m and battery storage capacity moved into operation, with more under construction. At the same time, group revenue fell 4.6% and net profit attributable to shareholders dropped 28.9% in H1. This was followed by a 66.4% Q3 net income decline. Storage and gas are progressing, yet so far they are not large enough to offset the profit squeeze visible in recent results.
One Narrative disagrees with today's price. → See where this Narrative says Huaneng Power International should trade.
Bear Case Finds Support In Weaker Earnings Mix
The bearish story argues that Huaneng Power International risks prolonged earnings pressure as low carbon projects and overseas units fail to carry their weight.
"Although Huaneng Power International reports low carbon clean energy already above 42% of controlled capacity with more than 10 GW of projects under construction, the recent declines in wind and photovoltaic net profit alongside loss making solar farms suggest that new additions could keep diluting revenue per megawatt and pressure earnings if tariff and curtailment headwinds persist into future output."
H1 wind profit falling 20.5% and PV profit dropping 35.8%, followed by a 66.4% Q3 net income decline, show that renewables are not yet easing margin strain. Overseas contribution from Tuas Power also faced higher carbon taxes, weaker FX and higher gas costs, which lines up with the concern around softer international returns. Fuel cost jumps in Q2 and lower domestic tariffs reinforce the idea that multiple profit levers all moved in an unfavorable direction in this period, so the cautionary thesis finds clear support in the latest print.
Hunt For Mispriced Earnings Power
Huaneng Power International illustrates how a profit squeeze can keep sentiment mixed even after headline results. The real opportunity could be in stocks where fundamentals and valuation drift apart before closer analysis adjusts expectations.
- Company 1 - 21% below our estimate - expand electrical distribution into higher margin services as customers upgrade infrastructure for data centers and automation projects.
- Company 2 - 25% below our estimate - supply photonic gear as chipmakers restart capacity projects and biophotonics orders recover from a slow investment cycle.
- Company 3 - 26% below our estimate - scale injectable therapies for weight loss and diabetes as payors and patients shift spending toward these treatments.
Those are three of them. See every one of the 195 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com