


Q3 earnings put Triumph Financial in focus
Triumph Financial (TFIN) moved into the spotlight after reporting third quarter 2026 results, with net interest income of US$103.13 million and net income of US$13.43 million from continuing operations.
The Q3 release lands after a choppy stretch for Triumph Financial’s stock, with the share price up 4.13% over the past month but down 15.68% over the last quarter. The 1 year total shareholder return of 8.97% suggests momentum has been rebuilding more gradually.
Scan other hand picked financials showing solid earnings profiles and cleaner balance sheets alongside Triumph Financial using the list of solid balance sheet and fundamentals (24 results).
Analysts see Triumph Financial trading below their price targets, while the market still prices in a fair amount of caution after the recent slide. Does that gap reflect opportunity or real concern about the valuation?
Most Popular Narrative: 15% Undervalued
On the most followed view, Triumph Financial is priced below an estimated fair value of $75, while the last close sits at $63.99. That gap rests on the idea that higher margin fee and data revenue can matter more than the banking headwinds investors see today.
The continued mix shift from traditional banking toward higher margin fintech and intelligence offerings, which are expected to represent a greater share of Triumph Financial’s revenue base, supports a higher contribution from fee income and potentially stronger returns on assets.
Expansion of Triumph Financial’s data and decision support tools such as the Intelligence offerings and RFP Manager, built on a large brokered freight dataset, provides opportunities to grow subscription and analytics revenue and support a second leg of earnings contribution beyond core financial services.
See why 2 investors see Triumph Financial as 15% undervalued.
Result: Fair Value of $75 (UNDERVALUED)
Still, Triumph Financial remains heavily tied to freight cycles, and flat Intelligence revenue so far leaves the second earnings leg more exposed if trucking conditions soften.
Find out about the key risks to this Triumph Financial narrative.
Another View: Triumph Financial Looks Pricey On Earnings
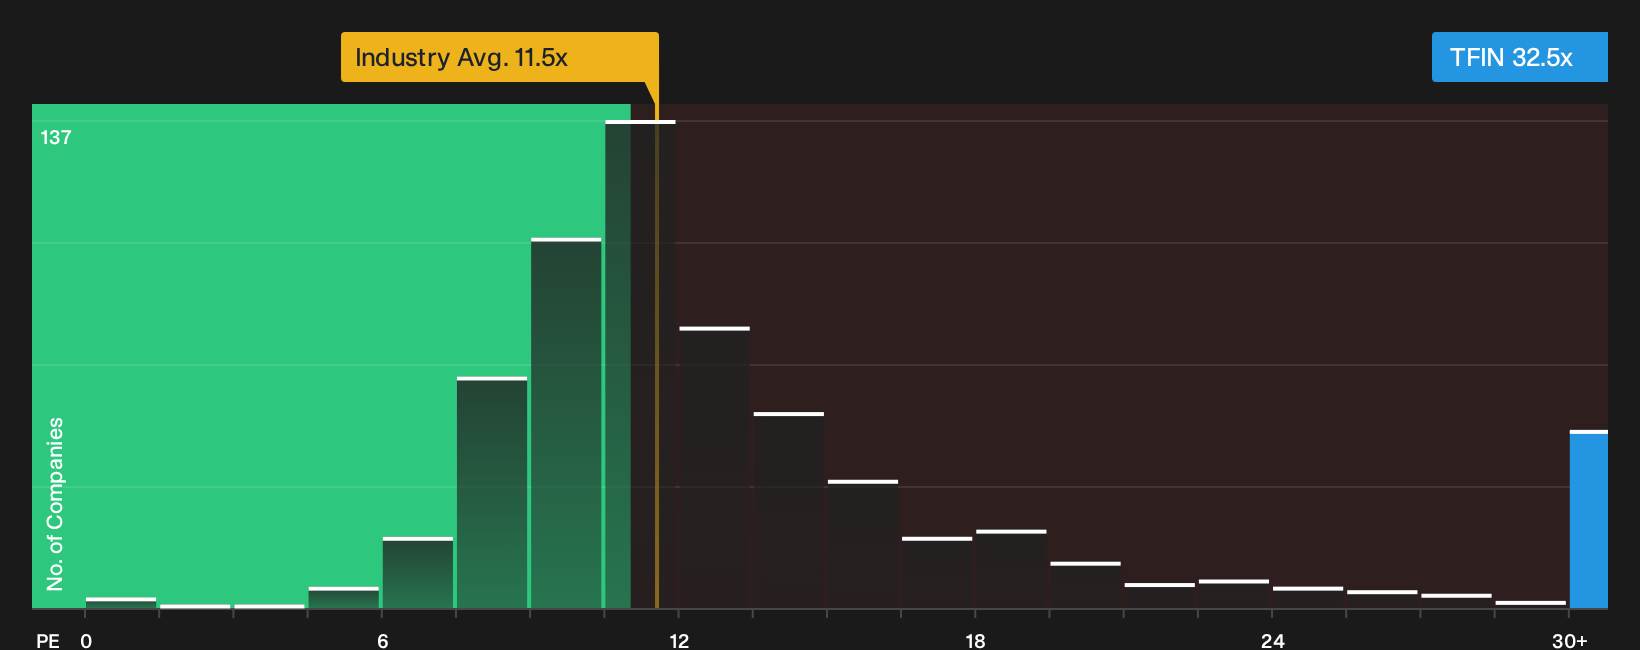
The fair value narrative pegs Triumph Financial at $75, yet the current P/E of 32.5x is almost triple the US Banks average of 11.5x and well above the peer group at 11.6x. The fair ratio of 18.8x also sits far lower. Is the market paying too much for the growth story?
For a closer look at how that earnings premium compares to sector norms and the fair ratio the market could move toward, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages on Triumph Financial’s valuation can feel confusing. Move quickly on your own homework, weigh both sides of the debate, and take a closer look at the 2 key rewards and 3 important warning signs.
Looking for more Triumph Financial sized ideas?
If Triumph Financial has your attention, do not stop there. Broaden your watchlist today so you are not chasing opportunities after they move.
- Target stronger value opportunities by scanning companies that look mispriced on quality and fundamentals using the 29 high quality undervalued stocks.
- Prioritise resilience by reviewing a curated 30 resilient stocks with low risk scores that may suit investors who care about steadier profiles.
- Hunt for tomorrow’s potential standouts by checking a 21 high quality undiscovered gems that many investors may not be watching yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com