


- Centerra Gold recently secured new exploration options in Québec and increased attention on its stake in Azimut Exploration, expanding its potential project pipeline in a key Canadian mining region.
- The Québec exploration options and Azimut position give Centerra Gold another way to source future resources, which may matter if existing mines face shorter lives, tighter capital budgets, or shifting metallurgy over time.
- We will now look at how Centerra Gold's Québec exploration push could reshape the existing investment narrative built around its current mines.
Scan beyond Centerra Gold and its Québec push by comparing it with other hand picked 35 elite gold producer stocks that could react differently to the same commodity and exploration headlines.
Centerra Gold Investment Narrative Recap
To own Centerra Gold, you need to be comfortable with a miner that leans heavily on cash flow from Mount Milligan and Öksüt to fund a wider copper, gold, and molybdenum portfolio, while analysts still see earnings and revenue easing over the next few years. The key near term swing factor is how reliably those core sites stick to plan and sustain current profitability.
The largest immediate risk is pressure on margins if costs rise faster than expected or realised metal prices soften, given analysts are already assuming some margin compression. Québec exploration and the Azimut stake do not change that near term picture in a material way, because they sit earlier in the life cycle.
The Québec options and Azimut interest are the clearest recent developments tied to this story. They feed directly into management’s effort to build a North American exploration pipeline alongside work in Ontario and British Columbia, which is intended to support future projects rather than near term production.
For you, the relevance sits in timing and execution. If Centerra Gold converts this Québec exposure into defined resources that complement projects like Goldfield and Kemess, it could help offset the analyst view that revenue and earnings will decline, although the work required to get from early stage ground to producing assets remains significant.
What The Québec Exploration Push Sits On Top Of
Centerra Gold is layering its Québec options on a financial outlook that already bakes in lower production and profitability, at least according to current analyst models. Those forecasts matter for how much patience the market may have for early stage exploration in a region that can take years to translate into operating mines.
Consensus work today points to a shrinking top line rather than expansion. Analysts are assuming revenue will decline by 8.4% a year over the next three years, with profit margins easing from 36.9% to 31.8% over that window as the core mines mature and cost pressures and mix changes are factored in.
Earnings follow the same pattern. Profit today is quoted at $636.5 million and is projected at $421.1 million by 2029, which implies an earnings drop of about $215 million over that period instead of growth, even before layering in what Québec might add over a longer horizon.
On those assumptions, the same 2029 framework ties revenue of roughly $1.3 billion to that $421.1 million profit figure. This gives a sense of the balance between expected sales and bottom line outcomes in the models. Analysts are effectively pointing to 2029 as the reference year that anchors both their earnings and revenue views.
Centerra Gold's current Québec exploration options and the Azimut position sit on top of this backdrop of forecast revenue of $1.3 billion and earnings of $421.1 million by 2029, alongside an assumed 8.4% yearly revenue decline and an earnings decrease of about $215 million from $636.5 million today.
Uncover why Centerra Gold's fair value indicates a 14% potential upside to its current price, which could narrow quickly.
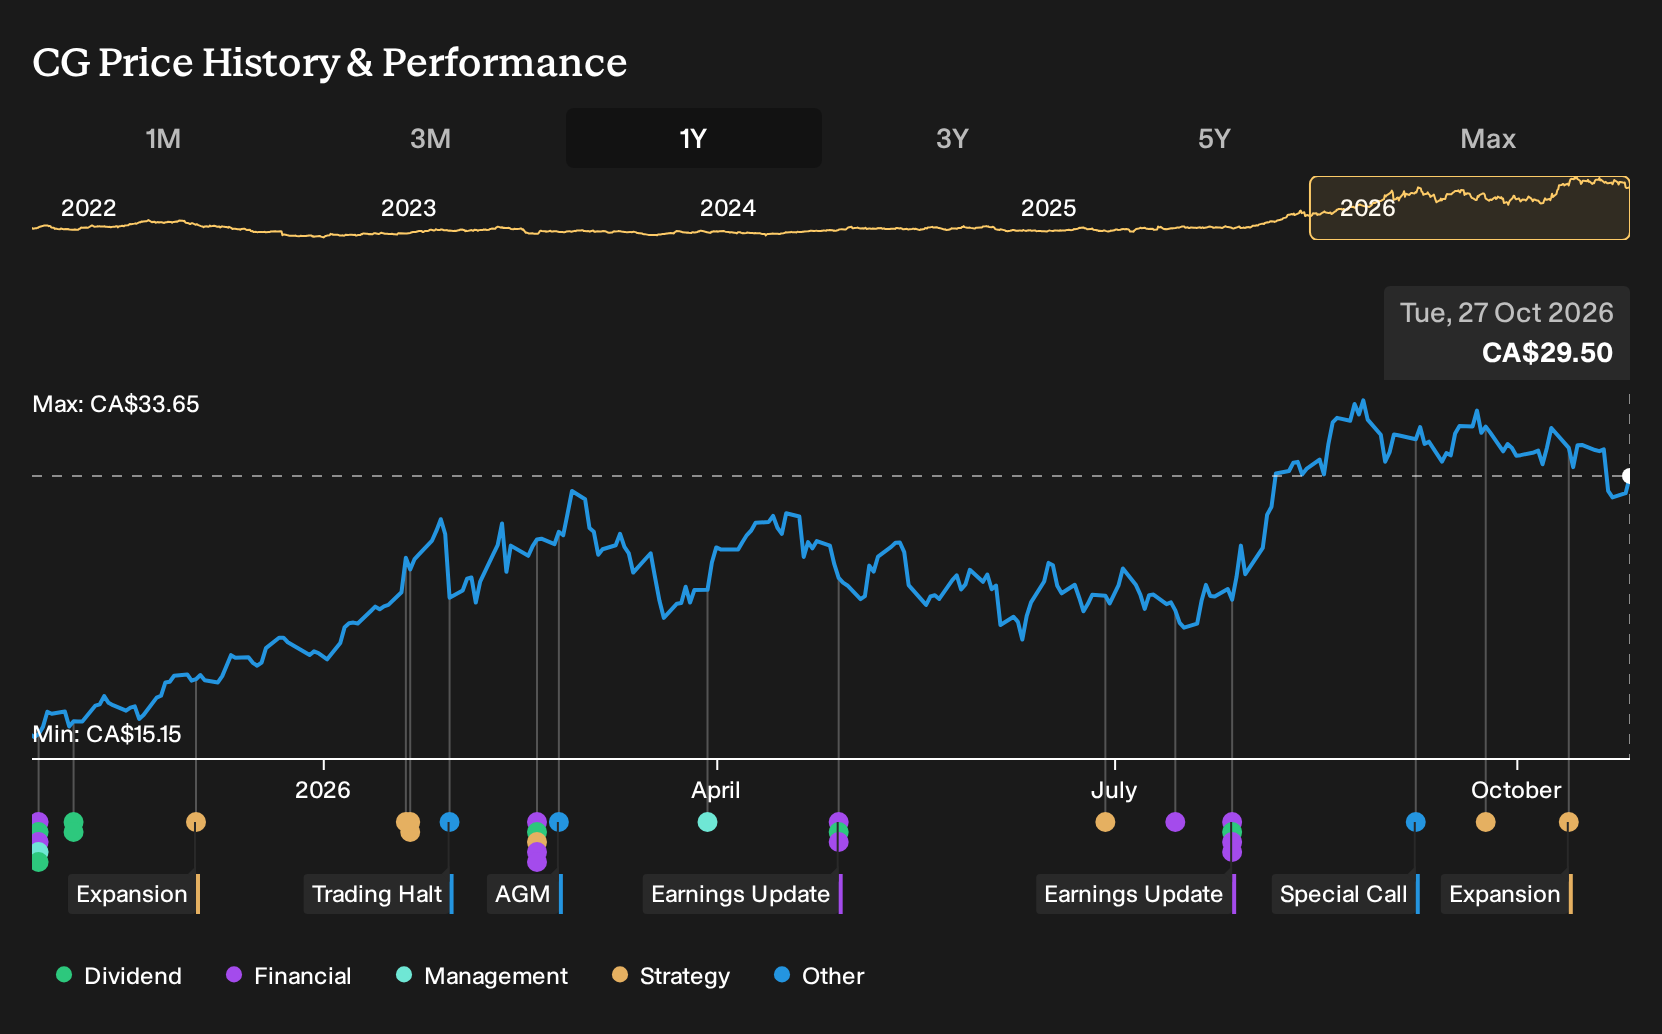
Exploring Other Perspectives
One alternate view focuses on free cash flow pressure rather than Québec upside. The most bearish analysts were already pencilling in about $1.2b of 2029 revenue and $486.2 million of earnings, then applying a low 7.4x P/E. You can treat the Québec and Azimut moves as fresh information that might eventually shift those expectations.
Explore 3 other Centerra Gold fair value estimates, including one that suggests as much as 68% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis and judgment.
- A great starting point for your Centerra Gold research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Centerra Gold. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to review Centerra Gold's overall financial health at a glance.
Looking For More Ideas Beyond Centerra Gold?
If the Centerra Gold story has you thinking about how different miners and sectors might respond to the same set of commodity headlines, it can be useful to line up a few alternatives side by side using a broader stock screener.
- If capital preservation matters to you, consider starting with companies that score well on resilience by checking out 8 resilient stocks with low risk scores.
- For investors who care about balance sheet strength before anything else, focus on businesses that pair cleaner debt profiles with consistent fundamentals via the list of solid balance sheet and fundamentals (7 results).
- If you are searching for less crowded opportunities, scan through the 9 high quality undiscovered gems that combine strong underlying metrics with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com