


Emerson Electric has delivered a strong share price run in recent years, which naturally raises a simple question for you as an investor: Is the current US$166.27 price tag adequately explained by the earnings the business is generating today and what those profits may reasonably support over time?
- Over the past 3 years the stock has returned 97.0%, which puts real pressure on the question of whether earnings power has risen enough to keep that move grounded.
- The company’s mix of industrial automation and technology focused solutions can influence how consistently it converts accounting earnings into cash, which is crucial when you try to judge what multiple those profits might justify.
- There is a second opinion on Emerson Electric worth weighing. See what analysts think Emerson Electric's shares could be worth.
The issue now is whether the earnings that underpin Emerson Electric can support today’s valuation or if expectations have moved ahead of the underlying profit stream.
If you want a quick reference point for how Emerson Electric’s recent 97.0% three year return compares with other potential opportunities, it can help to line it up against 29 high quality undervalued stocks.
Is Emerson Electric Getting Expensive on Earnings?
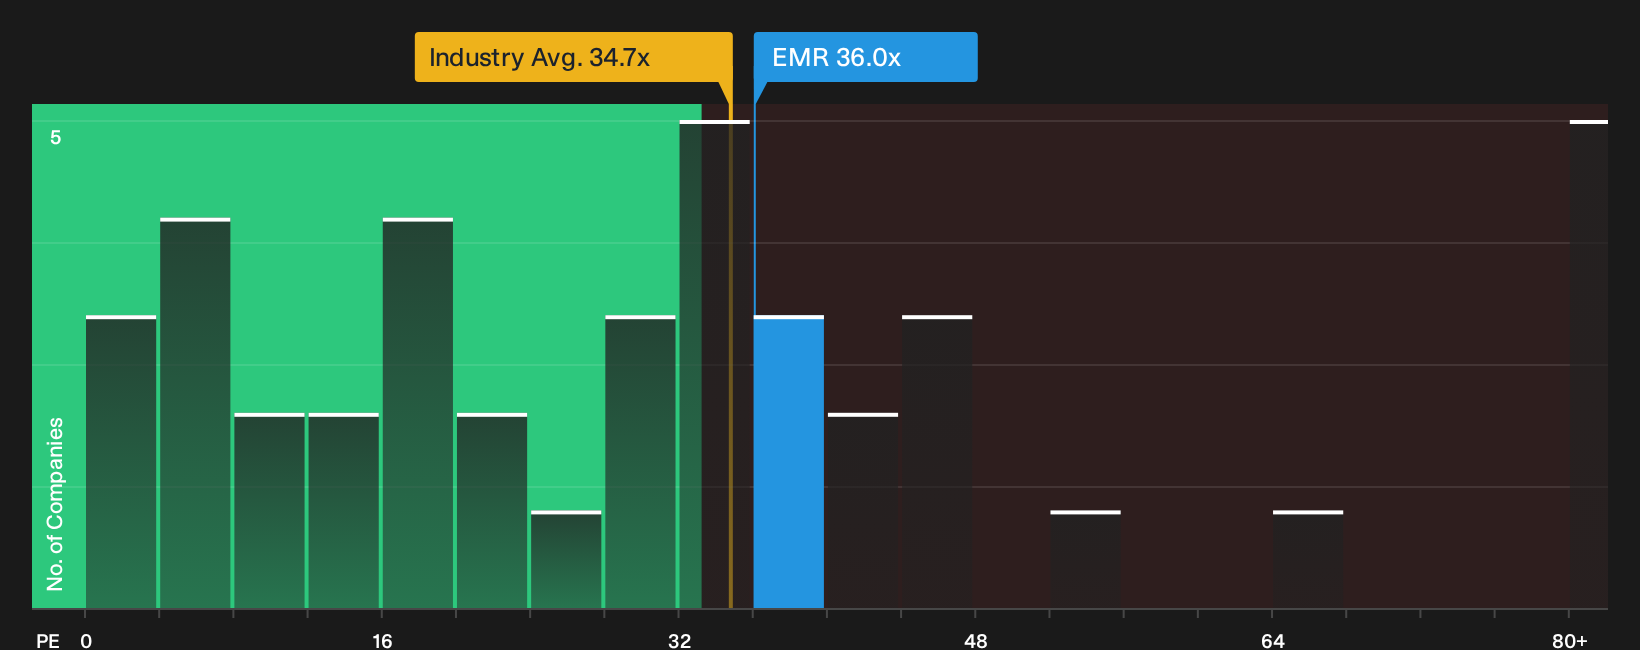
The P/E ratio works well for Emerson Electric because earnings remain the main anchor for how investors weigh this kind of industrial and automation business. At roughly 36.0x earnings, the stock trades above the Electrical industry average of about 34.7x and below the broader peer group on roughly 40.5x. That leaves Emerson Electric priced on the richer side of its sector, but not at the very top of the peer range.
The fair P/E multiple suggested by this model, which blends the company’s growth outlook, profitability, size and risks, sits below where the shares currently change hands. On this framework the valuation screens as overvalued relative to what those fundamentals might justify. Anyone considering the stock needs to judge whether the quality and durability of Emerson Electric’s earnings profile are strong enough to warrant that premium. Explore the numbers behind Emerson Electric's P/E valuation.
The Emerson Electric Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Emerson Electric pick up where the P/E debate leaves off and spell out what sort of growth, margins and earnings path would need to play out for the stock to be worth materially more or less than today’s price, and they sit on the platform’s Community page. Instead of a single output from a ratio or valuation model, Narratives lay out the future that figure implicitly relies on so you can follow whether those assumptions keep holding up over time.
Community views on Emerson Electric’s potential are split between those who see more to play for and others who think expectations already look full.
Bull case: roughly fairly valued
"Emerson Electric's focus on subscription-based software and recurring revenue streams is reinforced by software annual contract value of about US$1.64b to US$1.68b..."
Discover why this Narrative puts Emerson Electric at roughly fairly valued.
Bear case: 23% overvalued
"The numbers indicate that Emerson Electric’s current share price already reflects optimistic outcomes on long cycle power, LNG, and software growth..."
Explore why this Narrative puts Emerson Electric at 23% overvalued.
Emerson Electric's price is only part of the story
Before you decide how Emerson Electric fits into your portfolio, it helps to see how professional analysts currently map out its profit and revenue path over the next few years. Explore where analysts expect Emerson Electric to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com