


Rapid growth outlook collides with margin and customer concentration questions
Credo Technology Group Holding (CRDO) is drawing attention after management projected over 85% revenue growth for fiscal 2027, while investors weigh declining operating margins and heavy reliance on a few large customers.
Recent trading tells a mixed story for Credo Technology Group Holding. The share price jumped 10.77% in the last session to US$167.43, yet it is still down 20.64% over 30 days and 5.65% over 90 days. At the same time, the year-to-date share price return of 16.90% and a very large 3-year total shareholder return of about 11x suggest longer term momentum has been strong, even as sentiment cools around margin pressure and customer concentration risk.
Scan how Credo Technology stacks up against other high-growth chip players by reviewing the hand picked 55 AI infrastructure stocks that are powering data centers and next generation connectivity.
After a sharp one day pop followed by a steep 30 day slide, the question for Credo Technology now is whether the current valuation still compensates you for margin and customer concentration risk.
Most Popular Narrative: 22% Undervalued
On the most followed narrative, Credo Technology Group Holding is priced below an assessed fair value of $215, with the last close at $167.43 and an implied discount of about 22% that hinges on very strong execution.
Credo’s latest results make me more positive about the underlying business, but I still classify CRDO as a high-risk investment because the valuation assumes continued exceptional execution. My personal fair value is $215 per share. This is my personal opinion and not a recommendation to buy or sell.
See why 22 investors see Credo Technology Group Holding as 22% undervalued.
Result: Fair Value of $215 (UNDERVALUED)
However, the bullish Credo Technology story can reverse quickly if AI infrastructure demand fades or a major customer pullback exposes that concentration risk.
Find out about the key risks to this Credo Technology Group Holding narrative.
Another view on Credo Technology’s valuation
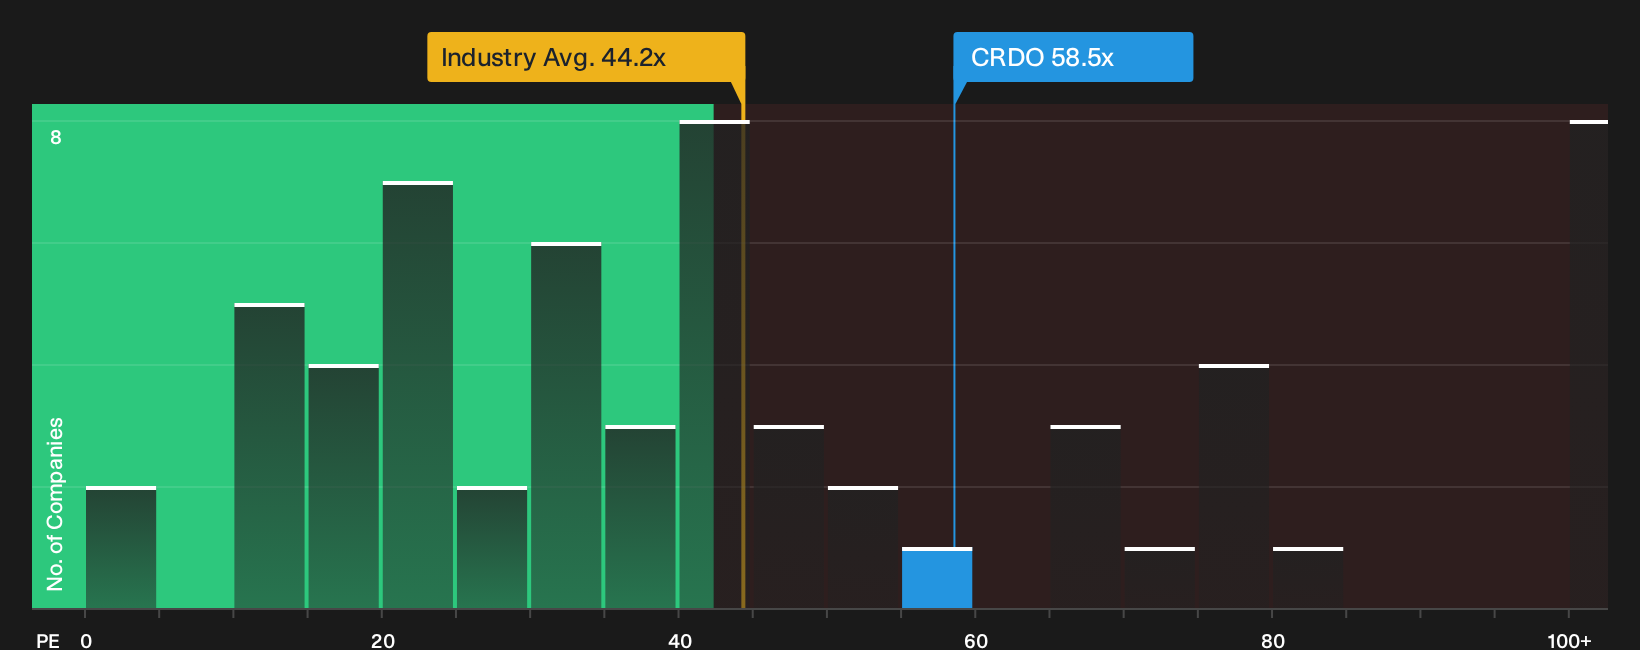
On pure price multiples, Credo Technology Group Holding screens as expensive. The P/E sits at 58.5x, above both the US Semiconductor sector on 44.2x and the peer group at 50.5x, and even above an estimated fair ratio of 50.6x that the market could move toward over time.
That gap points to less room for error. If earnings growth or sentiment cools, a move closer to the sector, peers or the fair ratio would mean a much lower valuation than the user narrative suggests. Which yardstick matters more for you: the story-based $215 fair value or where the multiples currently sit?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Credo Technology can tempt you to lean heavily bullish or bearish, so move quickly, review the underlying data, and weigh the 4 key rewards and 2 important warning signs.
Looking for more Credo Technology ideas and beyond?
If you only focus on Credo Technology Group Holding today, you may miss other opportunities that fit your risk level, income goals, and valuation preferences.
- Target stronger downside protection by scanning a 30 resilient stocks with low risk scores that aims to keep portfolio shocks in check.
- Hunt for quality at a discount by reviewing a 21 high quality undiscovered gems that highlights companies with solid fundamentals flying under the radar.
- Build staying power into your portfolio by checking a list of solid balance sheet and fundamentals (24 results) that focuses on financially robust businesses ready for tougher conditions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com