


Agilent Technologies, Inc. (A), headquartered in Santa Clara, California, is a global provider of laboratory instruments, software, consumables, and services. It supports life sciences research, clinical diagnostics, and testing across pharmaceuticals, food, water, chemicals, and applied materials, helping scientists and laboratories achieve accurate, reliable results and improve operational efficiency. The company has a market capitalization of approximately $49.6 billion.
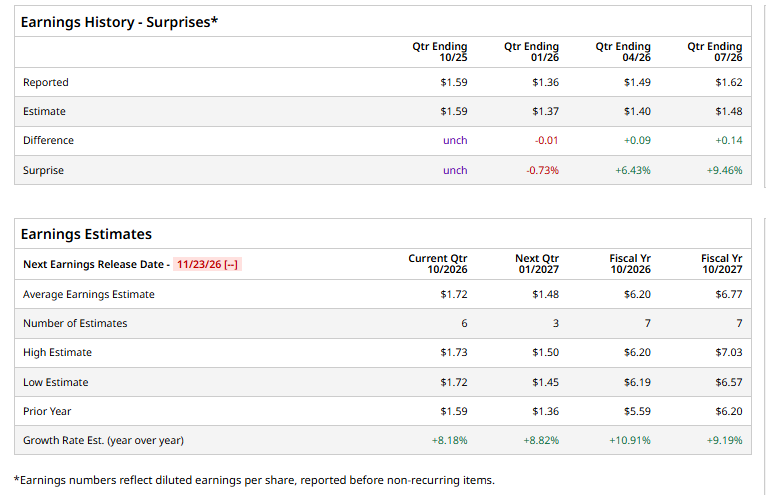
A is set to report its Q4 earnings soon. Ahead of the release, analysts expect the company to report diluted EPS of $1.72, up 8.2% from $1.59 in the year-ago quarter. Moreover, it has met or exceeded Wall Street’s EPS estimates in three of the past four quarters, while missing on another quarter.
For fiscal 2026, analysts expect A to report EPS of $6.20, reflecting a 10.9% increase from $5.59 in fiscal 2025. Furthermore, its EPS is projected to increase another 9.2% year over year to $6.77 in fiscal 2027.
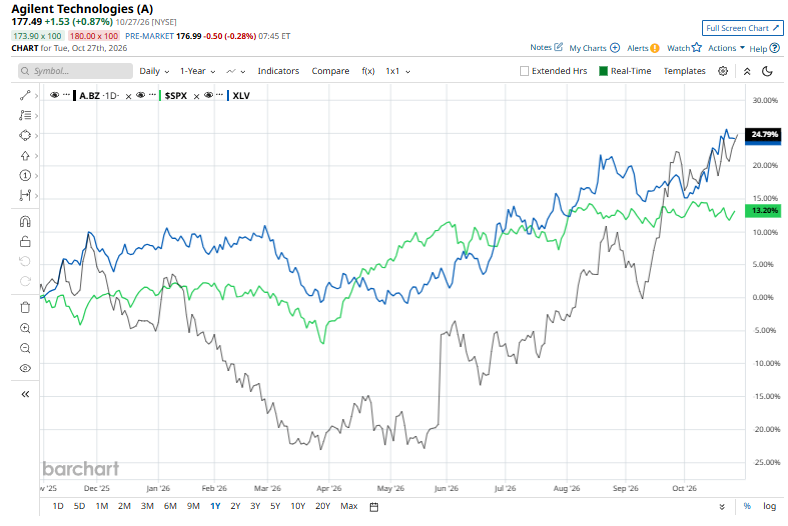
A stock has surged 21.1% over the past 52 weeks, outperforming the S&P 500 Index ($SPX), which returned 12.3%. However, it slightly trailed the State Street Health Care Select Sector SPDR ETF (XLV), which gained 22.4% over the same period.
Agilent Technologies maintains solid momentum through strategic partnerships and acquisitions, expanding its capabilities across energy research and digital pathology. On October 27, 2026, Agilent announced a collaboration with the University of Chicago to establish a Center of Excellence for Energy Materials Research. The center will use Agilent’s analytical instruments to support research into next-generation batteries and energy storage technologies, potentially creating opportunities to expand its instrumentation and services.
Earlier, on October 13, Agilent agreed to acquire Proscia for $240 million upfront, plus up to $30 million tied to future performance milestones. The acquisition will broaden Agilent’s digital pathology and AI capabilities, strengthen its companion diagnostics and biopharmaceutical research offerings, and add a high-growth, high-margin software business with recurring revenue. Expected to close in early fiscal 2027, the deal could support Agilent’s long-term growth.
Analysts remain moderately bullish on A, with the stock carrying a consensus “Moderate Buy” rating. Of the 20 analysts covering the stock, 13 recommend a “Strong Buy,” one recommends a “Moderate Buy,” and six suggest a “Hold.” The average analyst price target of $182.28 implies potential upside of 2.7% from the current share price.
On the date of publication, Kritika Sarmah did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.