


Williams-Sonoma, Inc. (WSM), headquartered in San Francisco, California, operates as an omni-channel specialty retailer of various products for home. With a market cap of $29.4 billion, the company retails cooking and serving equipment, home furnishings, and home accessories through retail stores, mail order catalogs, and e-commerce. The multi-channel specialty retailer is expected to announce its fiscal third-quarter earnings for 2026 in the near future.
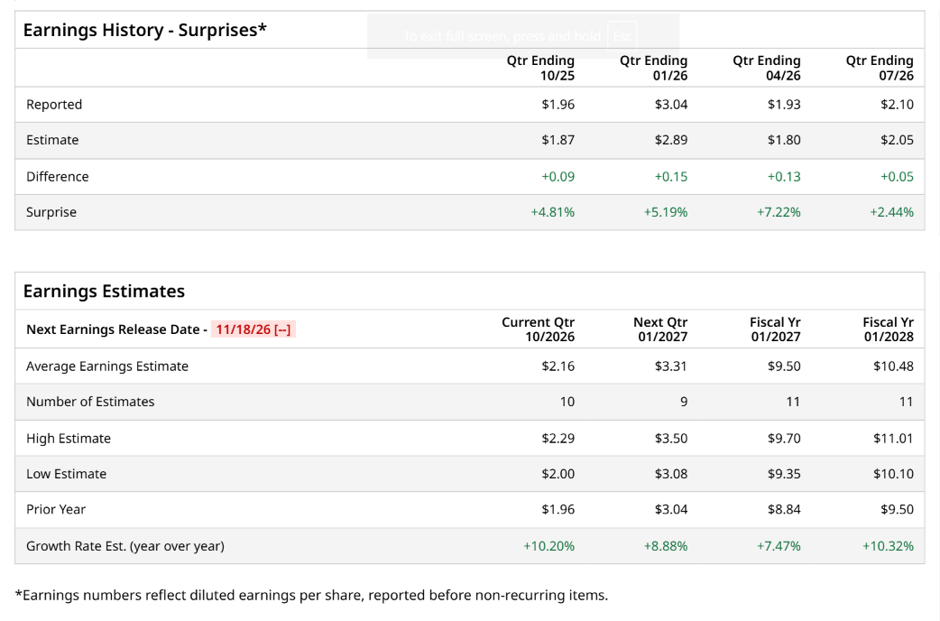
Ahead of the event, analysts expect Williams-Sonoma to report a profit of $2.16 per share on a diluted basis, up 10.2% from $1.96 per share in the year-ago quarter. The company has consistently surpassed Wall Street’s EPS estimates in its last four quarterly reports.
For the full year, analysts expect Williams-Sonoma to report EPS of $9.50, up 7.5% from $8.84 in fiscal 2026. Its EPS is expected to rise 10.3% year over year to $10.48 in fiscal 2028.
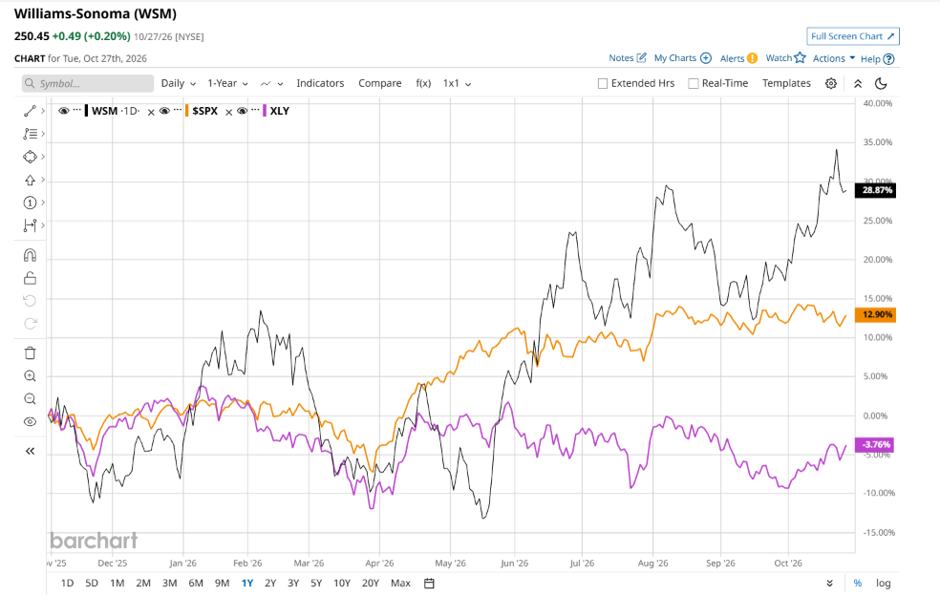
WSM stock has outperformed the S&P 500 Index’s ($SPX) 12.3% gains over the past 52 weeks, with shares up 29.9% during this period. Similarly, it outperformed the State Street Consumer Discretionary Select Sector SPDR ETF’s (XLY) 4.2% losses over the same time frame.
WSM’s strong performance is underpinned by its growth, fueled by broad-based momentum across all brands, successful collaborations like Emma Chamberlain at West Elm and Hill House Home at Williams Sonoma, and a robust product innovation pipeline. CEO Laura Alber highlighted market share gains driven by strength in both DTC and retail, supported by efficiency gains, moderating tariff pressures, and margin-boosting lower shrink accruals. Furthermore, the company scaled AI-driven personalization tools, such as the Oliver shopping assistant, which generated about 620% revenue jump, while double-digit growth in its B2B segment and high-performing partnerships continue to attract younger demographics and drive full-price selling.
Analysts’ consensus opinion on WSM stock is reasonably bullish, with a “Moderate Buy” rating overall. Out of 21 analysts covering the stock, nine advise a “Strong Buy” rating, one suggests a “Moderate Buy,” and 11 give a “Hold.” WSM’s average analyst price target is $254.95, indicating a potential upside of 1.8% from the current levels.
On the date of publication, Neha Panjwani did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.