


- XPENG has already announced a deeper collaboration with Alphabet by integrating Google Play and Android Automotive OS directly into its vehicles, while investors also await Alphabet's upcoming quarterly update on AI driven Search, YouTube, and Cloud operations.
- The integration of Google Play into XPENG's AI powered cockpit, alongside potential TPU deals with OpenAI, highlights how Alphabet is extending its app ecosystem and AI hardware beyond phones and PCs into cars and external data centers.
- We will now look at how Alphabet's earnings focused AI and cloud narrative could be influenced by the potential TPU deal.
Scan how the AI spending story extends beyond Alphabet by comparing it with other data center and chip hungry businesses using the 55 AI infrastructure stocks.
Alphabet Investment Narrative Recap
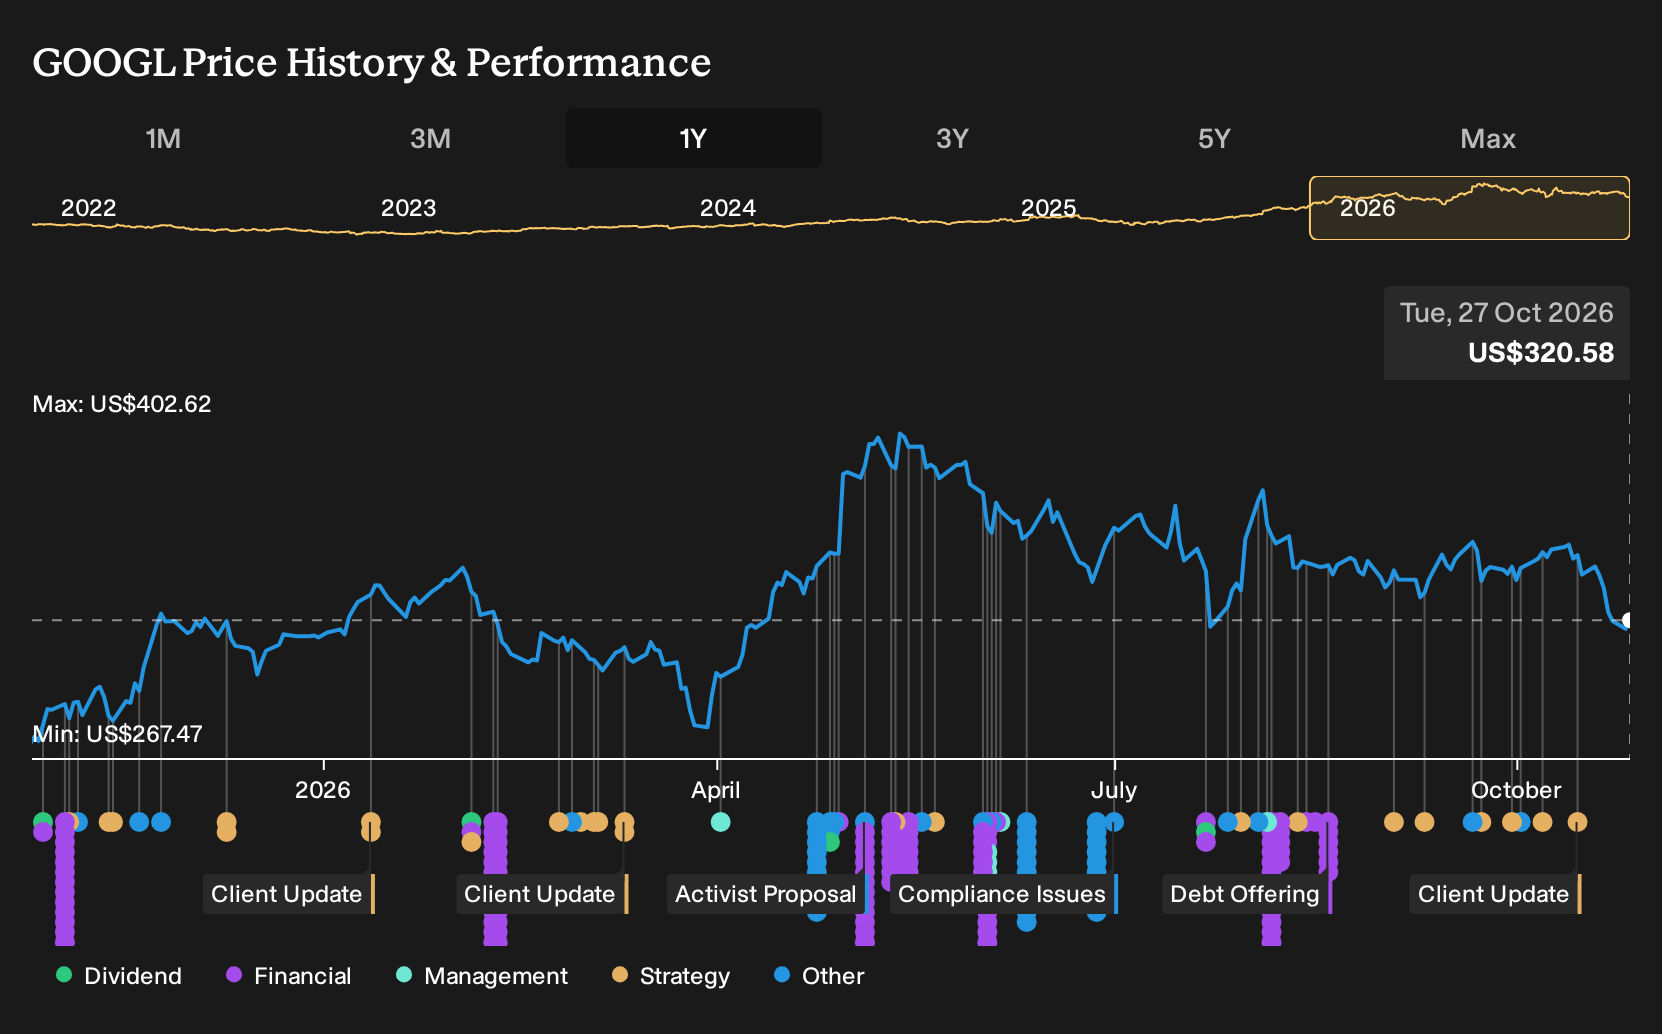
To hold Alphabet, you need to believe its heavy AI spending eventually turns today's cash pressure into durable demand across Search, YouTube, and Google Cloud. In the near term, the key question is whether AI driven products such as Gemini, AI Overviews, and APIs keep pulling more usage into Alphabet's ecosystem and support that thesis.
The biggest operational risk is that AI infrastructure and TPU capacity fail to earn back their cost quickly enough, especially with free cash flow recently in loss territory. Upcoming earnings, with close scrutiny on cloud margins and cash generation, appear more important to the story than the XPENG and Google Play headlines.
The OpenAI interest in buying Alphabet's Tensor Processing Units ties directly into that AI infrastructure bet. If TPUs see broader uptake from external data centers alongside customers like Oracle, investors gain more evidence that Google's custom chips are useful beyond its own workloads and that its hardware stack is competitive with Nvidia GPUs.
This potential TPU deal also intersects with Google Cloud's US$514b AI weighted backlog and the broader AI spending cycle across Microsoft, Amazon, and others. Execution on chip supply, data center capacity, and reliable delivery to third parties becomes a key operational catalyst. At the same time, any slowdown in AI adoption or tighter capital budgets remains a clear overhang.
Alphabet's narrative projects US$795.9b revenue and US$243.1b earnings by 2029. This assumes revenue grows at 21.3% per year and earnings decline by about US$1.0b from US$244.1b today.
Uncover how Alphabet's fair value indicates a 34% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
Some of the most cautious analysts focus less on XPENG style app wins and more on Alphabet’s heavier AI CapEx and questions around cloud reliability. Before this auto deal, the lowest group was modelling revenue of about US$744.4b and earnings of roughly US$172.8b by 2029. That is a far more pessimistic story. Use it as a prompt to compare several narratives and decide which assumptions feel reasonable to you, especially if this in car Google Play expansion leads analysts to revisit those forecasts.
Explore 59 other Alphabet fair value estimates, including one that suggests as much as 37% downside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Alphabet research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Alphabet. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Alphabet's overall financial health at a glance.
Looking For More Investment Ideas Beyond Alphabet?
If Alphabet has sharpened your focus on AI heavy spending and cash generation, it can be useful to line it up against other businesses with different balance sheet strength, risk profiles, and income potential using the Simply Wall St Screener.
- For investors who want staying power in tougher conditions, start by reviewing a list of solid balance sheet and fundamentals (24 results) that can help you focus on companies with stronger financial foundations.
- If your priority is resilience and smoother sleep at night, narrow your search to a 30 resilient stocks with low risk scores that highlights businesses with lower assessed risk scores.
- For those who care most about income today, scan a 5 dividend fortresses that filters for higher yielding payout streams.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com