


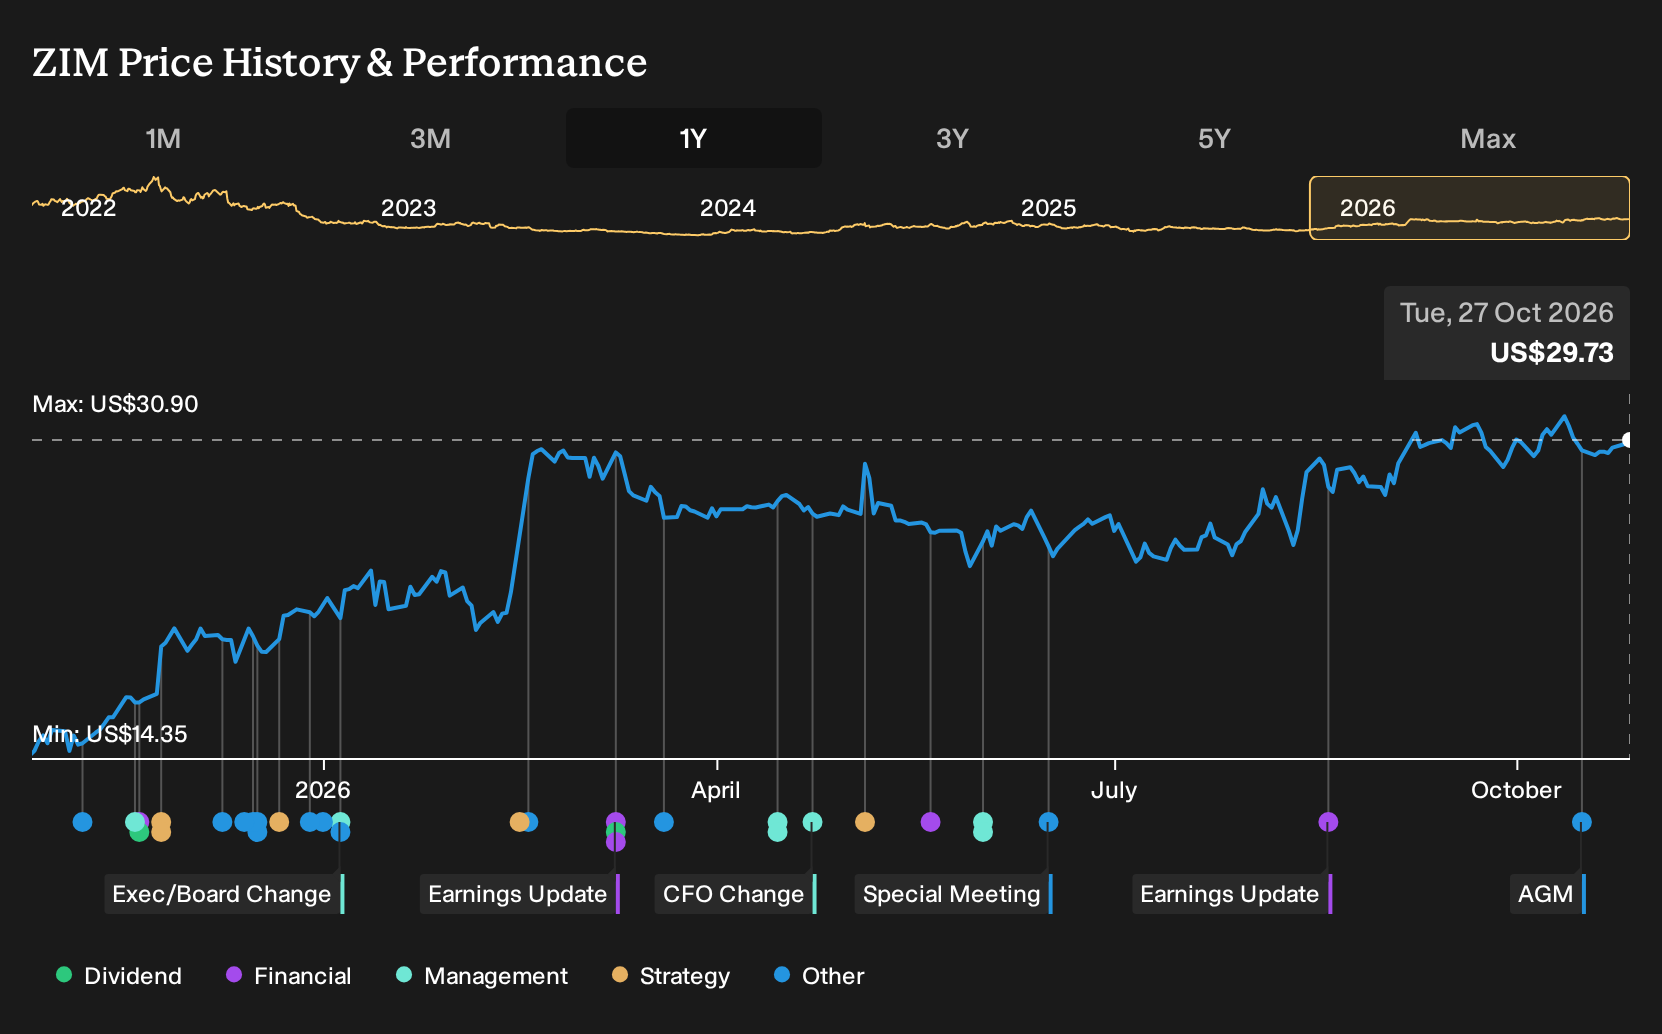
If ZIM Integrated Shipping Services was on your watchlist rather than in your portfolio, the return may sting. Holding ZIM Integrated Shipping Services over the past year would have returned 110.4%, including dividends. That kind of move invites a harder question. Back on 27 October 2025, when analysts were split between a bullish US$19 view and a more cautious stance, what sign in ZIM’s push into digital shipping and e-commerce could have helped you judge whether that margin trade-off was worth betting on?
ZIM Integrated Shipping Services has already moved. See which of 29 high quality undervalued stocks still trade below our estimates.
The Two Stories Investors Were Weighing On ZIM Integrated Shipping Services
The shares cost US$14.35 at the start of the period, and the real question for ZIM Integrated Shipping Services investors was which story about digital shipping and trade routes felt more realistic.
On the optimistic side, the bullish view pointed to a Fair Value of US$19, a price implied by expectations, built on ZIM’s LNG capable fleet and digital tools like AI driven pricing supporting revenue that was assumed to fall 12.5% a year with profit margins compressing toward 4.5%.
The more cautious camp worked off a Fair Value of US$13.26 based on assumptions that revenue would decline 16.9% annually, margins would narrow toward 1.4%, and heavy exposure to Transpacific trade plus chartered vessels could leave earnings highly sensitive to weak China US flows and industry overcapacity.
What The Results Changed For The ZIM Integrated Shipping Services Debate
ZIM Integrated Shipping Services reported Q2 2026 revenue of US$1.78b and net income of US$63.5m, compared with US$1.64b and US$22.8m in Q2 2025. Net margin moved from 1.4% to 3.6%. That combination gave more weight to the optimistic case that digital tools and route choices could support profitability, although margin stayed well below the bullish 4.5% assumption.
The key hinge here was not headline demand but whether higher quality services could show up in earnings. For another stock built on a similar story, an investor would typically track the shift in net margin alongside any new contract wins or guidance changes. From there, they could test whether management’s promised mix and digital uplift actually appear in those reported numbers.
What ZIM Integrated Shipping Services' 110% Run Already Prices In
With ZIM Integrated Shipping Services now at US$29.73 after a 110.4% gain over the past year, this Narrative’s Fair Value sits below the current price. The gap reflects a view that recent strength already bakes in optimistic assumptions about execution and industry conditions.
The Narrative focuses on how added capacity, charter exposure and deal timing could affect future freight cycles. A buyer at today’s level would need to believe ZIM can keep renewing its fleet and shifting routes without letting unit costs or freight rate pressure erode margins.
"Key Takeaways: Bearish analysts expect ZIM Integrated Shipping Services to face long term pressure on revenue and competitive positioning as container shipping supply additions, alliance reshuffles and consolidation among larger carriers and partners reshape global trade flows and industry structure. The main factor that has to go right is that ZIM executes on fleet renewal, cost control and route diversification into areas like Southeast Asia and Latin America, while managing regulatory, environmental and technology related costs so that margins remain resilient through future freight rate cycles."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
Which Company Could Surprise You Next?
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 46% below our estimate - turns a record backlog of data center builds into installation projects.
- Company 2 - 22% below our estimate - embeds AI assistants inside everyday productivity, cloud and developer software workflows.
- Company 3 - 38% below our estimate - advises on AI system breakdowns, safety issues and regulator-facing technical reviews.
Three companies from the same screener. Open every one of the 24 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com