


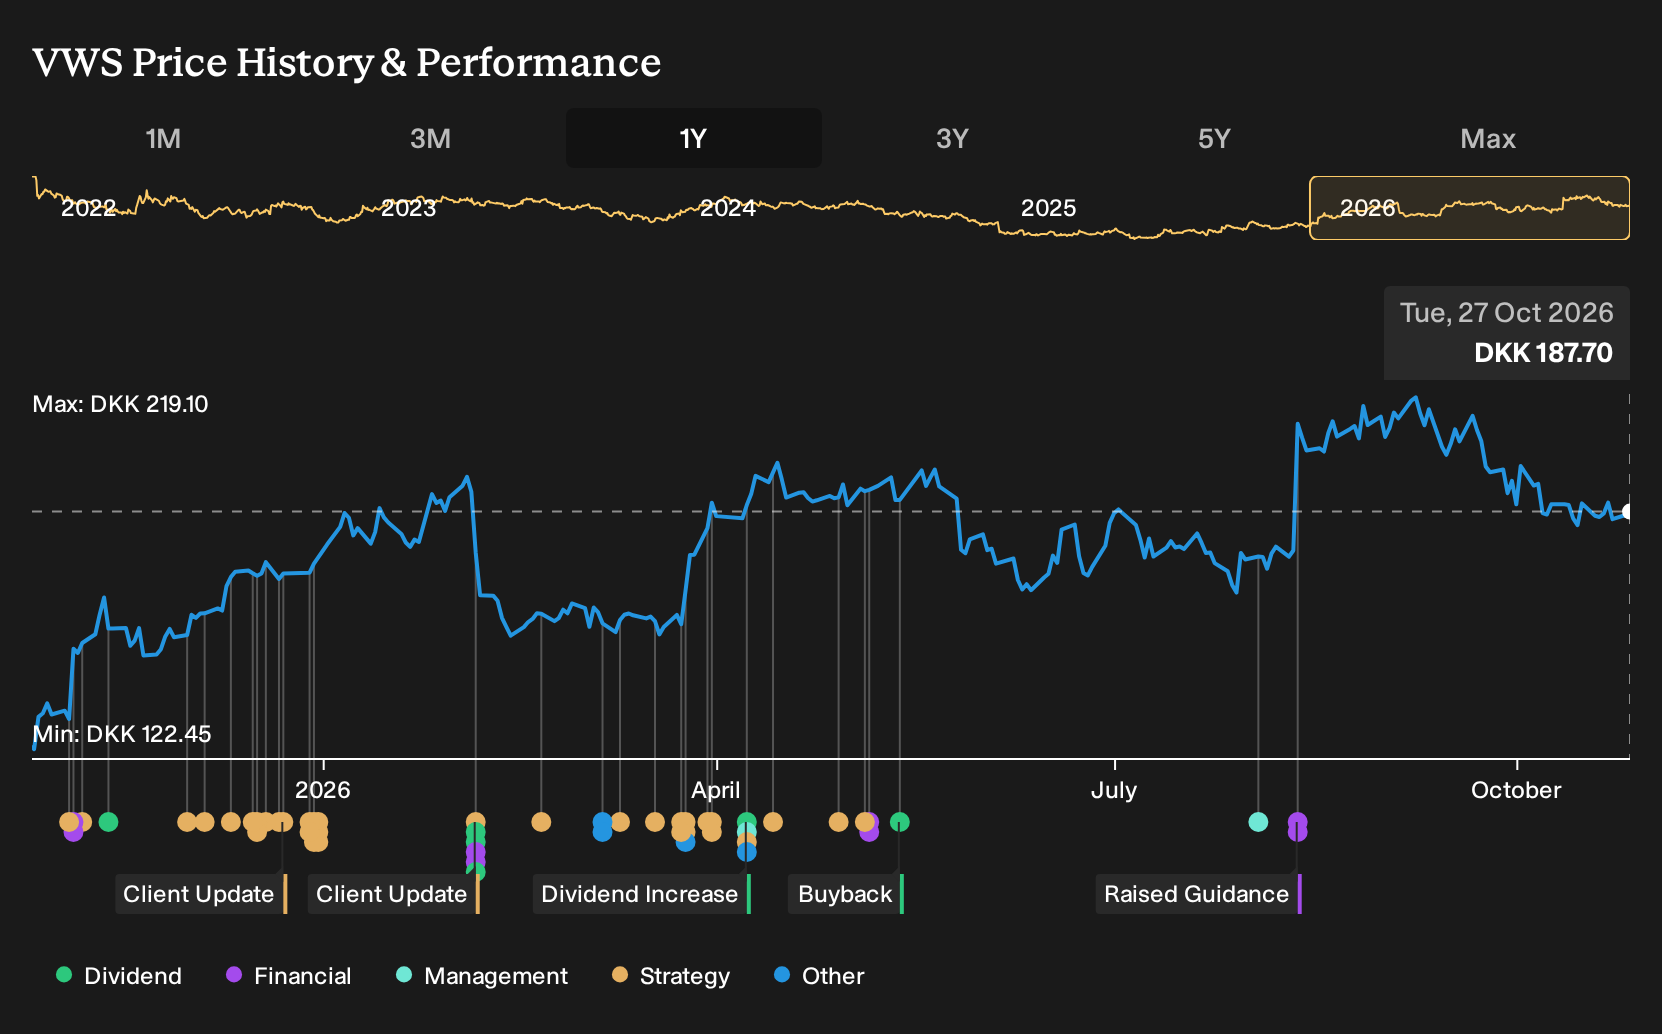
One concrete sign of momentum for Vestas Wind Systems arrived when it secured the first order for its new 7.2 MW V182 turbine in Sweden, tying fresh hardware to real demand rather than just a product announcement. For Vestas Wind Systems shareholders, the return over the past year was 43.5%, including dividends. If you were deciding whether to buy on 2025-10-27, what exactly had to be true in your mind before that order and the later earnings jump hit the screens?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
Vestas Wind Systems is not the only name tied to this theme. Zero in on 42 power grid technology and infrastructure stocks and compare how each one is priced.
The Two Vestas Wind Systems Stories Investors Had To Weigh
The shares cost DKK122 at the start of the period, and anyone looking at Vestas Wind Systems had to pick between two very different stories about the next few years.
The bullish Narrative put Fair Value at DKK141, or 15% above the start price. It leaned on policy support, grid reforms, and an assumption of 7.6% annual revenue growth with profit margins reaching 5.8%.
The bearish view set Fair Value at DKK60, or 51% below the start price. That camp focused on rising tariffs, fierce Chinese competition, and the risk that mounting offshore ramp up costs could keep squeezing margins.
What The Results Changed For The Vestas Wind Systems Story
Vestas Wind Systems landing the first firm order for its V182 7.2 MW turbine in Sweden backed the bullish argument that new products would see real demand. Later, Q2 2026 figures showed revenue of €4,723m and net income of €280m, with net margin at 5.9%. That margin outcome broadly supported the optimistic case, although long term risks from costs and competition remained untested here.
The episode turned on one assumption investors can reuse elsewhere. When a thesis leans on margin repair, track net income and net margin in each result. Then compare those figures directly with the percentages used in the original bullish or bearish narrative.
What Vestas Wind Systems' Price Now Assumes
Vestas Wind Systems now trades at DKK188, up 43.5% over the past year. The selected Narrative sees Fair Value below that level. It is built on the idea that offshore technology risk and service profitability keep the story more fragile than the share price suggests.
A buyer today effectively banks on offshore projects and Service margins progressing smoothly enough to support strong capital returns. The Narrative asks whether recurring blade or quality issues could force Vestas Wind Systems to prioritise remediation spending over that clean margin and payout path.
"Although Vestas Wind Systems is increasing offshore deliveries and reporting better manufacturing and installation efficiency, the recent blade failure at the He Dreiht project highlights that unresolved technology and execution risk could trigger additional remediation work, higher warranty usage and potential project penalties that weigh on EBIT margins and earnings."
That disagreement has a full argument behind it. → Uncover the lower Fair Value this Narrative argues for
How Could You Get There Earlier?
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 25% below our estimate - uses a cash-rich balance sheet to advance copper developments through permitting and production ramp-up.
- Company 2 - 21% below our estimate - leans on an extended aftermarket cycle while allocating capital to engine and defense capacity projects.
- Company 3 - 40% below our estimate - channels electrification and data demand into fee income from asset exits and new infrastructure vehicles.
Those are three of them. See the full list of 195 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com