


- TD SYNNEX recently expanded its Destination AI framework with SMB focused Game Plan experiences, Cloud Labs, an AI Skills Marketplace in StreamOne and dedicated AI training to help partners identify, test and deploy practical AI use cases more efficiently.
- The new SMB specific AI Skills Marketplace and proof of value Cloud Labs give TD SYNNEX resellers reusable tools to target everyday workflows like sales, support and operations, which can affect how recurring services and software revenue develop over time.
- We will examine how TD SYNNEX's investment narrative is influenced by this SMB focused AI Skills Marketplace initiative within Destination AI.
TD SYNNEX Investment Narrative Recap
For TD SYNNEX, the core belief is that AI driven demand, device refresh cycles and vendor consolidation keep feeding its distribution and Hyve businesses in a disciplined way. The most important short term catalyst is whether heavy AI infrastructure programs turn strong billings into cleaner cash generation. The new SMB focused Destination AI tools support this story, but mainly at the margin.
The biggest risk still sits with Hyve. Working capital needs and thinner margins on large AI server contracts could drag on free cash flow if they do not improve. The SMB AI Skills Marketplace does not remove that risk. It simply broadens where AI related services can show up in the model.
The fresh SMB focused Destination AI launch ties directly into the existing catalyst around digital engagement and recurring services. TD SYNNEX is giving resellers prebuilt AI Skills, structured enablement and proof of value Cloud Labs, which can make it easier for partners to standardize repeatable projects across sales, marketing, support and operations workflows.
That kind of repeatability matters for both execution and risk. It can support more predictable usage based and software related income streams, while Hyve works through its cash flow and margin challenges on large AI server programs. For investors watching quality of earnings, this SMB build out is most relevant as a potential stabilizer around the distribution and services engine.
TD SYNNEX's current analyst narrative points to revenues of US$105.4b and earnings of US$2.2b by 2029, based on forecasts of 11.7% yearly revenue growth and an earnings increase of about US$0.9b from US$1.3b today.
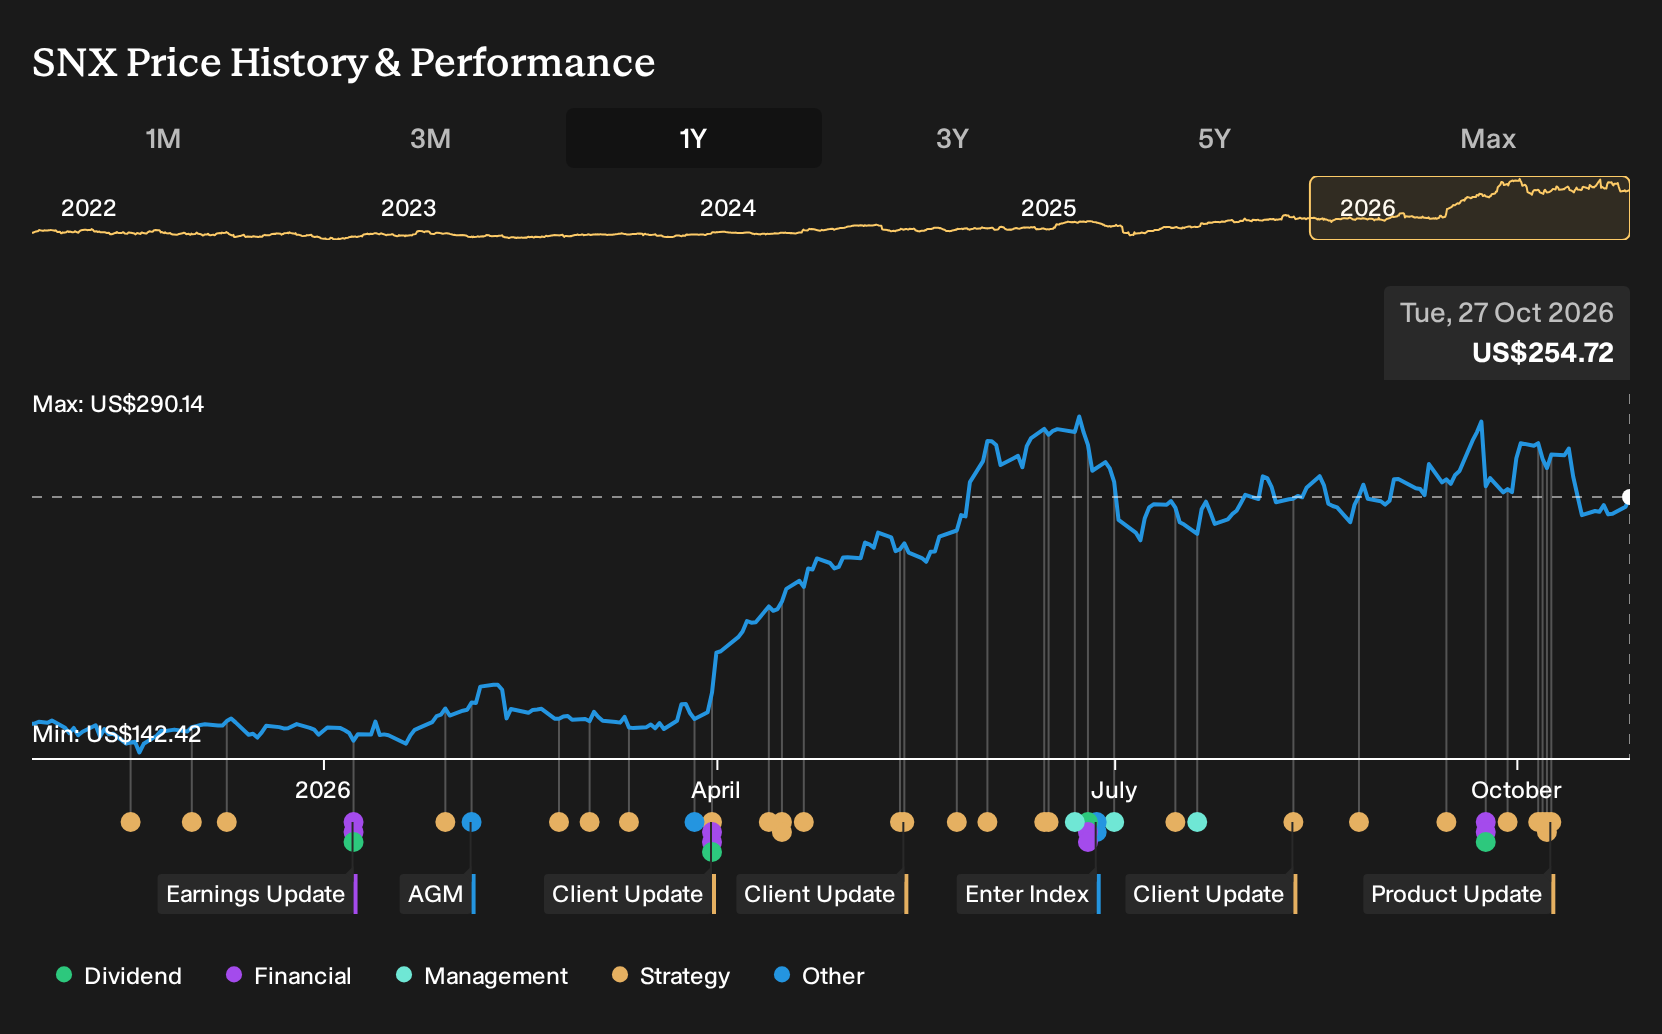
Uncover why TD SYNNEX's fair value indicates a 33% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts frame Hyve very differently from the baseline cash flow worries. They lean on broad AI and cloud buildouts with forecasts like US$97.9b in revenue and US$1.7b in earnings by 2029. Those views came before TD SYNNEX expanded Destination AI for SMBs, so you may see those projections shift as analysts update their models.
Explore 2 other TD SYNNEX fair value estimates, including one that suggests there may be as much as 108% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your TD SYNNEX research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for TD SYNNEX. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate TD SYNNEX's overall financial health at a glance.
Looking for more TD SYNNEX style investment ideas?
If TD SYNNEX has sharpened your focus on quality, recurring cash flows and clear business models, it can help to broaden your watchlist with other companies that fit specific traits using the Simply Wall St Screener.
- For investors who want potential mispricing on their side, start with companies that combine quality fundamentals and attractive valuations through the 29 high quality undervalued stocks.
- If capital preservation and steadier profiles matter most to you, consider firms screened for robustness and lower overall risk using the 30 resilient stocks with low risk scores.
- When you want strong finances to underpin any thesis, focus on companies with cleaner balance sheets and solid fundamentals via the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com