


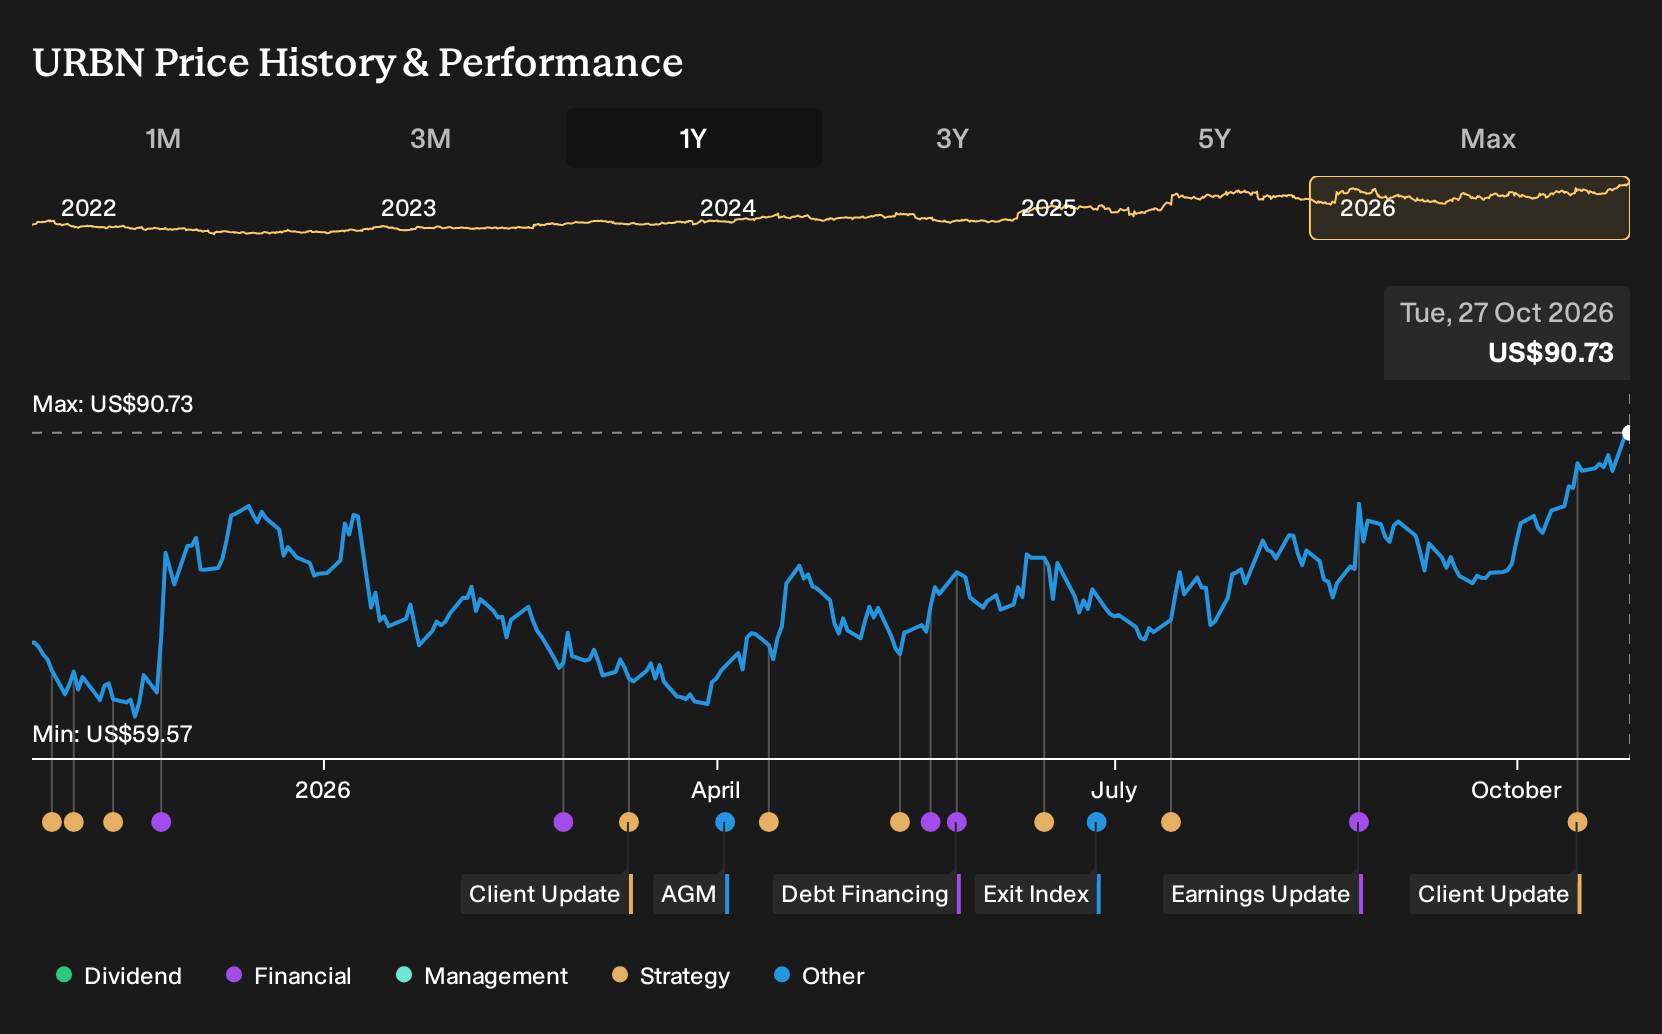
Urban Outfitters continued to expand its Nuuly rental arm, approving a nearly 975,000 square foot Pennsylvania distribution hub and targeting more automation in Kansas City to handle hundreds of thousands of subscribers. For Urban Outfitters shareholders, the return over the past year was 35.0%, including dividends. If you were considering a purchase a year ago, what would you have needed to believe about this capital-intensive rental buildout for that outcome to appear reasonable?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
If the move has made Urban Outfitters harder to judge, start where the gap is still open and scan 29 high quality undervalued stocks.
The Argument You Would Have Been Weighing Up On Urban Outfitters
The shares cost US$67.69 at the start of the period, and Urban Outfitters sat between two very different but reasonable stories about where the business might head next.
On the bullish side, the Fair Value was US$79.67, built on the idea that revenue could rise 7.1% a year and that Nuuly’s subscriber growth plus stronger e-commerce integration would support a future P/E of 16.5x.
The cautious view put Fair Value at US$47.28, assuming revenue would only rise 2.2% annually and that margin pressure from inventory and product issues would cap the future P/E at 13.2x.
What The Urban Outfitters Results Put To The Test
Nuuly moved from thesis to datapoint as subscription revenue rose 34.5% in Q1 fiscal 2027, with active users nearing 500,000 and operating margin at 6%. Q2 2027 results showed total revenue at US$1,661.9m and net income at US$240.7m, with net margin up to 14.5%. The evidence mainly backed the optimistic case.
The real hinge was not style or brand heat. It was whether Urban Outfitters could scale Nuuly and logistics while lifting profitability, so the figure to keep checking elsewhere is how new growth bets show up in segment margins and group net margin together.
What Urban Outfitters’ Price Already Bakes In
Urban Outfitters now trades at US$90.73, and this Narrative’s Fair Value sits below that level, which signals a view that much of the recent strength is already in the quote.
For today’s price to hold up, you would need Nuuly, FP Movement and the wider FP Group to scale profitably enough that their margins outweigh fuel surcharges, markdown risk and heavy capex.
"Although Nuuly is currently growing revenue with several hundred thousand subscribers and new automated facilities planned to support up to about 1.2 million subscribers, the roughly 70 basis point quarterly gross margin headwind from fuel surcharges risks absorbing much of the expected operating leverage from lower logistics cost per order. This could leave group operating income short of what is implied by current subscriber and revenue targets."
That disagreement has a full argument behind it. → Uncover the lower Fair Value this Narrative argues for
How Could You Get There Earlier?
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 46% below our estimate - turns a large AI-focused project backlog into installed systems and follow-on services.
- Company 2 - 38% below our estimate - builds multidisciplinary advisory practices as oversight intensifies around complex AI system failures.
- Company 3 - 31% below our estimate - secures shorter subsea tieback awards bundling equipment, engineering support and recurring service contracts.
Three companies from the same screener. Open all 24 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com