


Fresh debate around Poste Italiane (BIT:PST) has picked up as investors question whether its current market value really lines up with earnings generated across postal, financial, and insurance activities, as well as government linked digital projects.
At a latest share price of €24.46, Poste Italiane has recently combined a 13.19% year to date share price return with a softer 30 day move that declined 5.27%. However, the 1 year total shareholder return of 22.87% and very large 3 year total shareholder return hint that longer term momentum has been strong even as some investors reassess risks around mail volumes and government linked projects.
Scan how Poste Italiane compares with other income and quality plays by reviewing it alongside 224 dividend fortresses in similar yield-focused sectors.
After a strong multi year run and a recent pullback, Poste Italiane now forces a choice. Do you step in at €24.46, or wait for a deeper reset before committing fresh capital?
Most Popular Narrative: 17% Undervalued
On the most followed narrative, Poste Italiane screens as undervalued, with a fair value of €29.49 set against the latest close at €24.46. This puts the current discount under the microscope for anyone weighing fresh capital.
The main factor that has to go right is execution on the AI and network reorganization plans, including the creation of a single financial hub and a hub-and-spoke post office model, so that the targeted cost savings, workforce redeployment and higher cross-sell are reflected in earnings quality.
See why 28 investors see Poste Italiane as 17% undervalued.
Result: Fair Value of €29.49 (UNDERVALUED)
Still, the Poste Italiane story can flip if parcel momentum slows and mail volumes keep shrinking, or if rising HR and compliance costs squeeze margins harder than expected.
Find out about the key risks to this Poste Italiane narrative.
Another Angle On Poste Italiane’s Value
That 17% discount to fair value is only one story. The SWS DCF model for Poste Italiane points to a future cash flow value of €15.66 per share against the current €24.46. On that view, the stock screens as overvalued, which raises a simple question: Which set of assumptions do you trust more?
To understand how this cash flow view is built and where the sensitivities sit, Look into how the SWS DCF model arrives at its fair value.
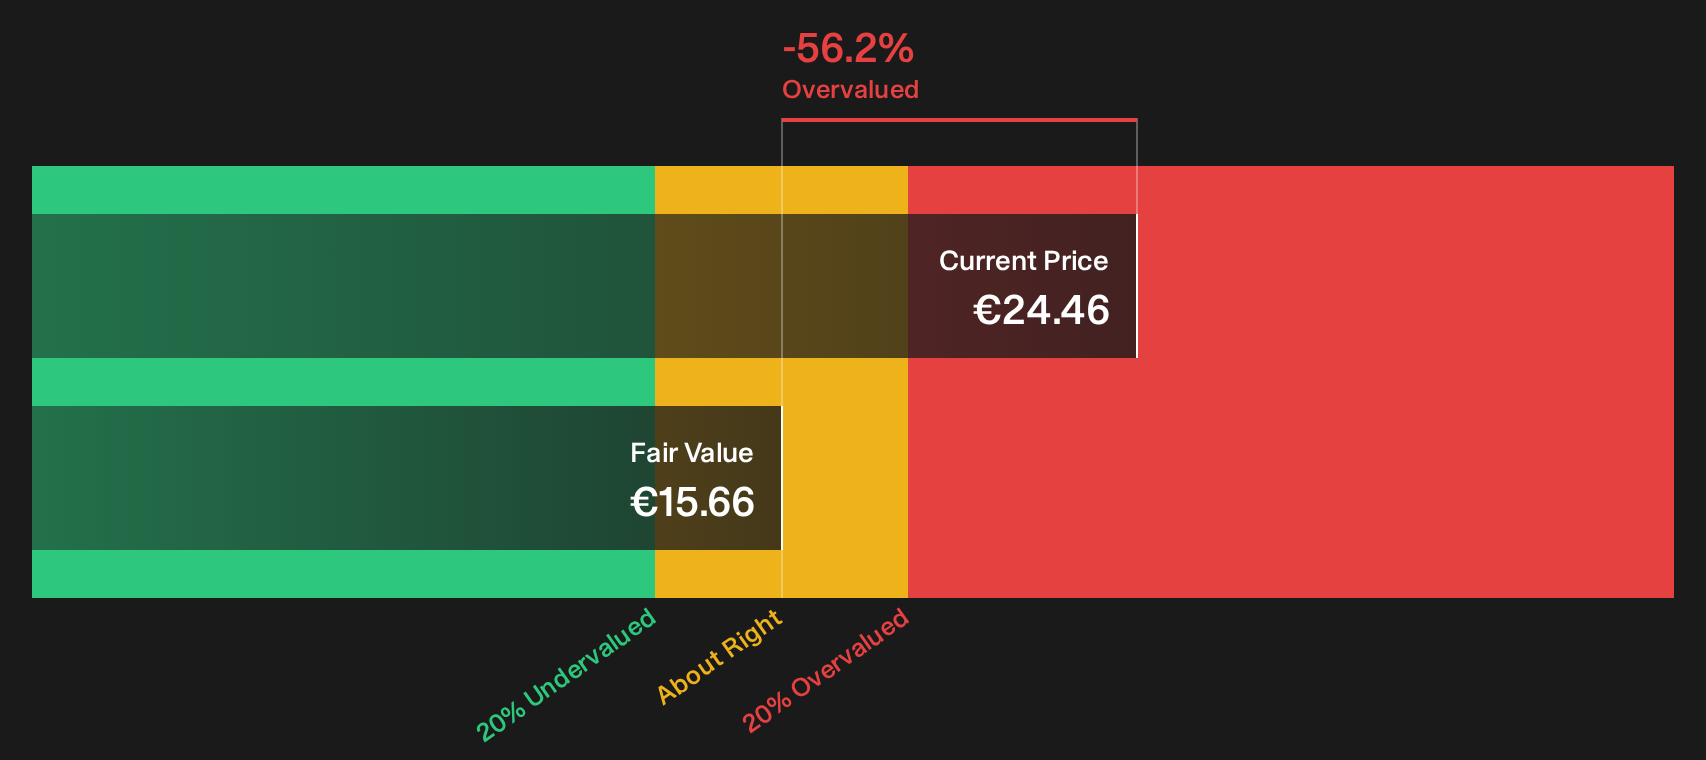
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Poste Italiane for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 195 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of optimism and concern around Poste Italiane feels familiar, act quickly with your own research and carefully weigh both sides through 3 key rewards and 3 important warning signs
Looking for more investment ideas beyond Poste Italiane?
Do not stop your research with Poste Italiane. Broaden your watchlist using focused stock ideas that match the kind of risk and return profile you actually want.
- Target long term wealth builders by scanning a curated set of high quality opportunities through 195 high quality undervalued stocks.
- Prioritise sleep at night resilience by checking companies screened for financial strength and staying power with the list of solid balance sheet and fundamentals (207 results).
- Get ahead of the crowd by reviewing a hand picked pool of overlooked opportunities using the 610 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com