


- Iovance Biotherapeutics reported final Phase 2 data at ESMO 2026 showing lifileucel plus pembrolizumab in frontline advanced melanoma with a 62.5% ORR, a 29.2% CR rate, and disease control in 83.3% of 24 treated patients, with safety in line with known profiles.
- The same congress featured early lifileucel results in soft tissue sarcomas and fast track designation for advanced UPS and DDLPS, pointing to a broader solid tumor opportunity and higher potential manufacturing and commercialization demands on Iovance’s TIL platform.
- We will look at how Iovance Biotherapeutics' investment narrative is shaped by lifileucel's melanoma data and the new sarcoma fast track designation.
Scan how Iovance Biotherapeutics fits into the wider oncology opportunity set by reviewing a hand picked 34 healthcare AI stocks working on data driven cancer and immunotherapy breakthroughs.
Iovance Biotherapeutics Investment Narrative Recap
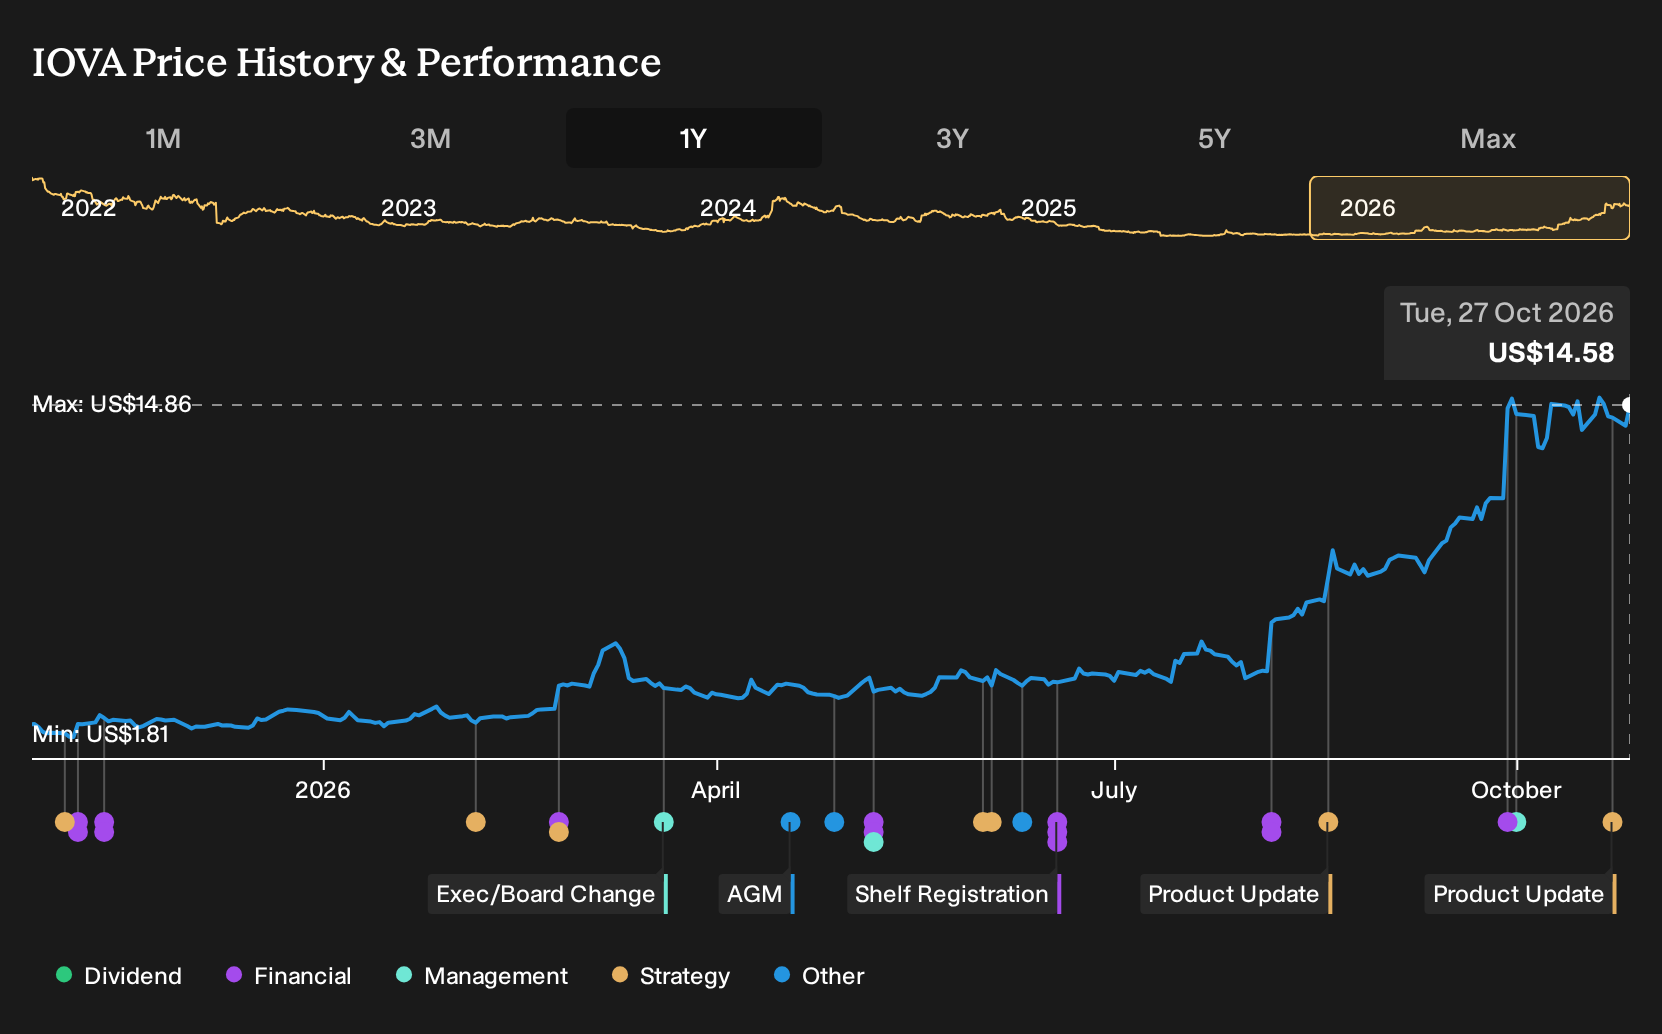
Iovance Biotherapeutics now asks investors to believe that tumor infiltrating lymphocyte therapy can move from a niche rescue option to a scalable commercial franchise. The lifileucel plus pembrolizumab Phase 2 melanoma data and early sarcoma readout both point toward a business increasingly built around multiple solid tumor indications using the same manufacturing engine.
The key near term swing factor remains execution on Amtagvi and lifileucel manufacturing, pricing and site activation, while TILVANCE 301 in frontline melanoma and the broader pipeline mature. The biggest risk stays the same: heavy reliance on a single complex, high cost platform, with regulatory friction in Europe and inherently pressured margins.
The lifileucel plus pembrolizumab Phase 2 melanoma update at ESMO 2026 is the announcement to focus on. It feeds directly into TILVANCE 301, which is designed to support frontline approval and act as the confirmatory study for full Amtagvi approval in previously treated disease. For a commercial stage cell therapy business, that is a central operational project.
If TILVANCE 301 tracks with the strength of the Phase 2 signal, the lifileucel franchise could have a clearer route to broader use in untreated advanced melanoma, with knock on implications for manufacturing scale, community oncology uptake and payer conversations. If the Phase 3 diverges meaningfully from these results, Iovance Biotherapeutics would be more exposed to its current single product, single geography concentration and existing cost base.
Iovance Biotherapeutics' current analyst story points to forecast revenues of US$1.0b and consensus earnings of US$121.2 million by 2029, off earnings today that reflect a loss of US$289.5 million, implying about 47.4% yearly revenue growth and an earnings swing of roughly US$410.7 million from loss to profit.
Uncover why Iovance Biotherapeutics' fair value indicates that it is roughly in line with its current price.
Exploring Other Perspectives
One alternate view on Iovance Biotherapeutics focuses less on trial headlines and more on earnings power. The most optimistic analysts were already penciling in about US$1.5b of revenue and US$254.7 million of earnings by 2029, far above consensus. You can use that gap to judge how much your own expectations might shift after the ESMO news.
Explore 5 other Iovance Biotherapeutics fair value estimates, including one that suggests as much as 274% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Iovance Biotherapeutics research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Iovance Biotherapeutics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Iovance Biotherapeutics' overall financial health at a glance.
Looking For More Investment Ideas Beyond Iovance Biotherapeutics?
If the Iovance Biotherapeutics story has sharpened your thinking about risk, reward and execution, it can help to compare it with other opportunities using the Simply Wall St Screener.
- Prefer to start with potential mispricings and quality fundamentals? Review a 29 high quality undervalued stocks that might warrant a place on your watchlist.
- If income is your priority and you care about consistency, scan a set of 5 dividend fortresses that could help anchor a portfolio with cash returns.
- For those who want sturdier finances to underpin any growth story, filter opportunities through a list of solid balance sheet and fundamentals (24 results) and see which ones match your risk tolerance.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com