


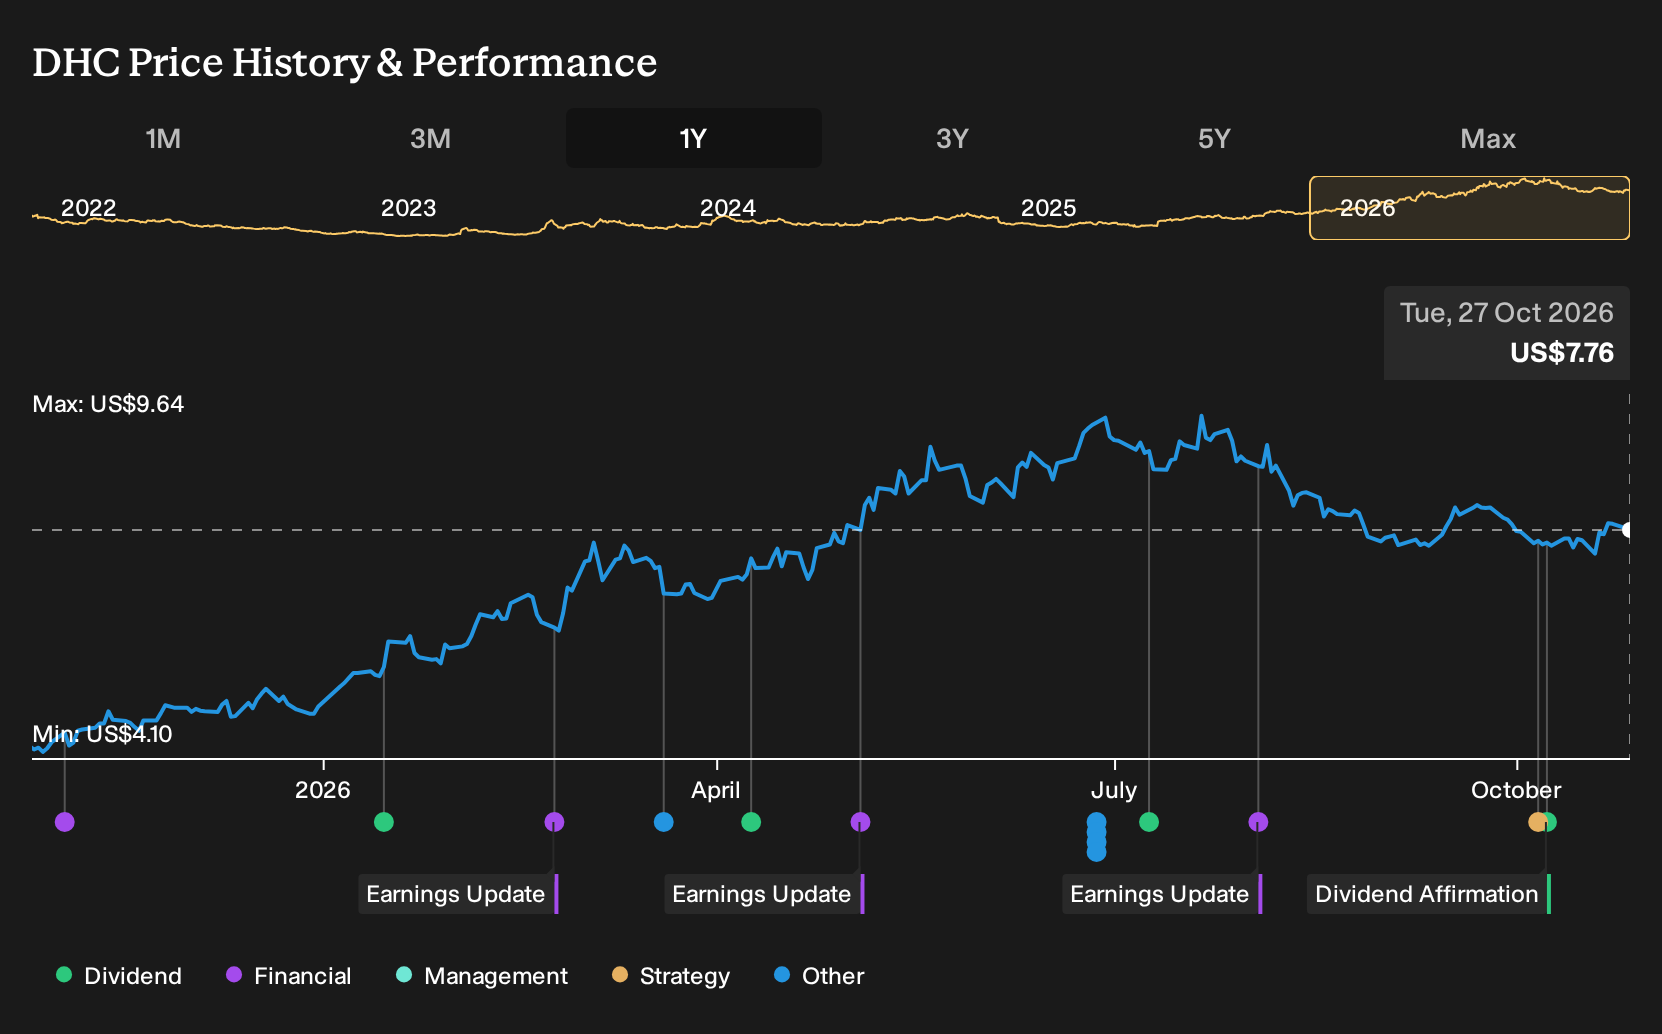
If you had looked at Diversified Healthcare Trust in late October 2025, the choice was anything but easy. Bulls pointed to aging demographics and telehealth driven demand for better facilities, while bears focused on heavy debt and shifting care models that could leave some properties behind. For Diversified Healthcare Trust shareholders, the return over the past year was 87.1%, including dividends. If you had been deciding that day, which risks and trade offs would have mattered most?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
If the move has made Diversified Healthcare Trust harder to judge, start where the gap is still open and scan 29 high quality undervalued stocks.
The Two Stories Investors Had To Weigh On Diversified Healthcare Trust
The shares cost US$4.14 at the start of the period, and Diversified Healthcare Trust sat between two very different but reasonable storylines.
On the bullish side, one view set Fair Value at US$4.5, expecting 2.8% annual revenue growth and a shift toward higher quality medical office and life science properties to support a 23.3% profit margin assumption.
The bearish camp anchored on a Fair Value of US$3. It built in 2.2% yearly revenue growth and highlighted refinancing risk from elevated debt as a central concern.
What The Results Changed For Diversified Healthcare Trust
Diversified Healthcare Trust locked in a 15 year triple net lease with Ensign Group for seven Colorado skilled nursing assets, shifting operating risk and property costs to the tenant and supporting the bullish focus on more stable cash flows. At the same time, revenue slipped from US$382.7m to US$365.4m, while the business still reported a loss, so the profitability piece of the optimistic case stayed unproven. Overall, the evidence cut both ways.
The lesson is simple. When a landlord story leans on better margins, you need to track two things together: the direction of net income and the terms of new leases that move costs and risks on or off the balance sheet.
What Diversified Healthcare Trust's Run Up Still Leaves You Paying For
Diversified Healthcare Trust now trades at US$7.76 after a 87.1% gain over the past year. The selected Narrative places its Fair Value above that price and ties the case to operations heavy work inside the existing portfolio rather than big new acquisitions.
The argument leans on management contracts, procurement savings and asset recycling. The Narrative suggests today's price may not fully credit sustained margin improvement and higher NOI from the senior housing operating portfolio.
"The view on Diversified Healthcare Trust has shifted from a broad focus on portfolio repositioning and sector tailwinds to a tighter, operations-led thesis built around reworked management contracts, cost savings programs, and asset-level capital recycling within the existing footprint."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Looking Beyond Diversified Healthcare Trust
Diversified Healthcare Trust keeps you focused on beds, rent and care. Yet the real estate story does not end there.
Healthcare tenants still need somewhere for medicines, equipment and supplies to move. That shifts attention toward logistics hubs and data heavy facilities supporting those flows.
Another property group concentrates on building and running those warehouses and digital infrastructure. It looks to turn large, powered sites into income producing logistics and data assets.
As care providers depend on connected supply chains and cloud tools, that kind of landlord could increasingly shape how healthcare operates behind the scenes.
One Narrative has already put a figure on it. → Uncover the company trading 22% below one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com