


Recent debate around Shizuoka Financial GroupInc (TSE:5831) has been triggered by its strong multi year share price gains, as investors reassess whether return on equity and book value trends still support the current valuation.
Recent trading has cooled some of that enthusiasm, with the share price down about 16% over the past month and 3% over the past quarter, even as the year to date share price return of 22.9% and a 5 year total shareholder return of 290.6% keep Shizuoka Financial GroupInc firmly in long term outperformance territory. This suggests that the current pullback may reflect a reset in expectations and risk perceptions rather than a complete break in the story that has supported its valuation debate so far.
Compare Shizuoka Financial GroupInc’s valuation reset with other potential value stories by reviewing the hand picked 16 high quality undervalued stocks that may also be pricing in similar expectation shifts.
After a sharp multi year climb and a recent pullback to ¥3,057, Shizuoka Financial GroupInc now sits at a crossroads. Does that reset leave more upside for buyers, or tip the balance of risk the other way?
Preferred P/E of 16.1x: Is it justified?
On current numbers, Shizuoka Financial GroupInc trades on a P/E of 16.1x, which sits slightly above both its closest peer set and the broader JP Banks industry, even though internal models still flag the shares as trading below some estimates of fair value.
The P/E ratio compares the share price to annual earnings per share. For a lender like Shizuoka Financial GroupInc, this metric gives a quick read on how much investors are willing to pay for each unit of profit relative to other financial institutions.
Here, the picture is mixed. On one hand, Simply Wall St flags the stock as good value versus an estimated fair P/E of 17.6x, a level the market could move towards if earnings forecasts and cash flow assumptions hold. On the other hand, the same 16.1x multiple looks expensive against both the direct peer average of 15.7x and the wider JP Banks industry at 14x, which implies that the market is already baking in relatively stronger profit resilience than many domestic banks.
Explore the SWS fair ratio for Shizuoka Financial GroupInc.
Result: Price-to-Earnings of 16.1x (ABOUT RIGHT)
Still, the Shizuoka Financial GroupInc story can be challenged quickly if its annual revenue decline of 2.1% persists, or if Japan-focused earnings momentum stalls.
Find out about the key risks to this Shizuoka Financial GroupInc narrative.
Another View: What The SWS DCF Model Says
The P/E discussion paints Shizuoka Financial GroupInc as only slightly mispriced. The SWS DCF model tells a stronger story, with an estimated future cash flow value of ¥4,824.18 against a share price of ¥3,057, which points to meaningful undervaluation if those long range cash flow assumptions hold.
That gap gives you a different kind of risk reward trade off. The P/E of 16.1x looks a bit rich versus peers today, while the DCF view suggests the market might be underpricing long term cash generation. Which lens do you trust more when sentiment swings again?
Look into how the SWS DCF model arrives at its fair value.
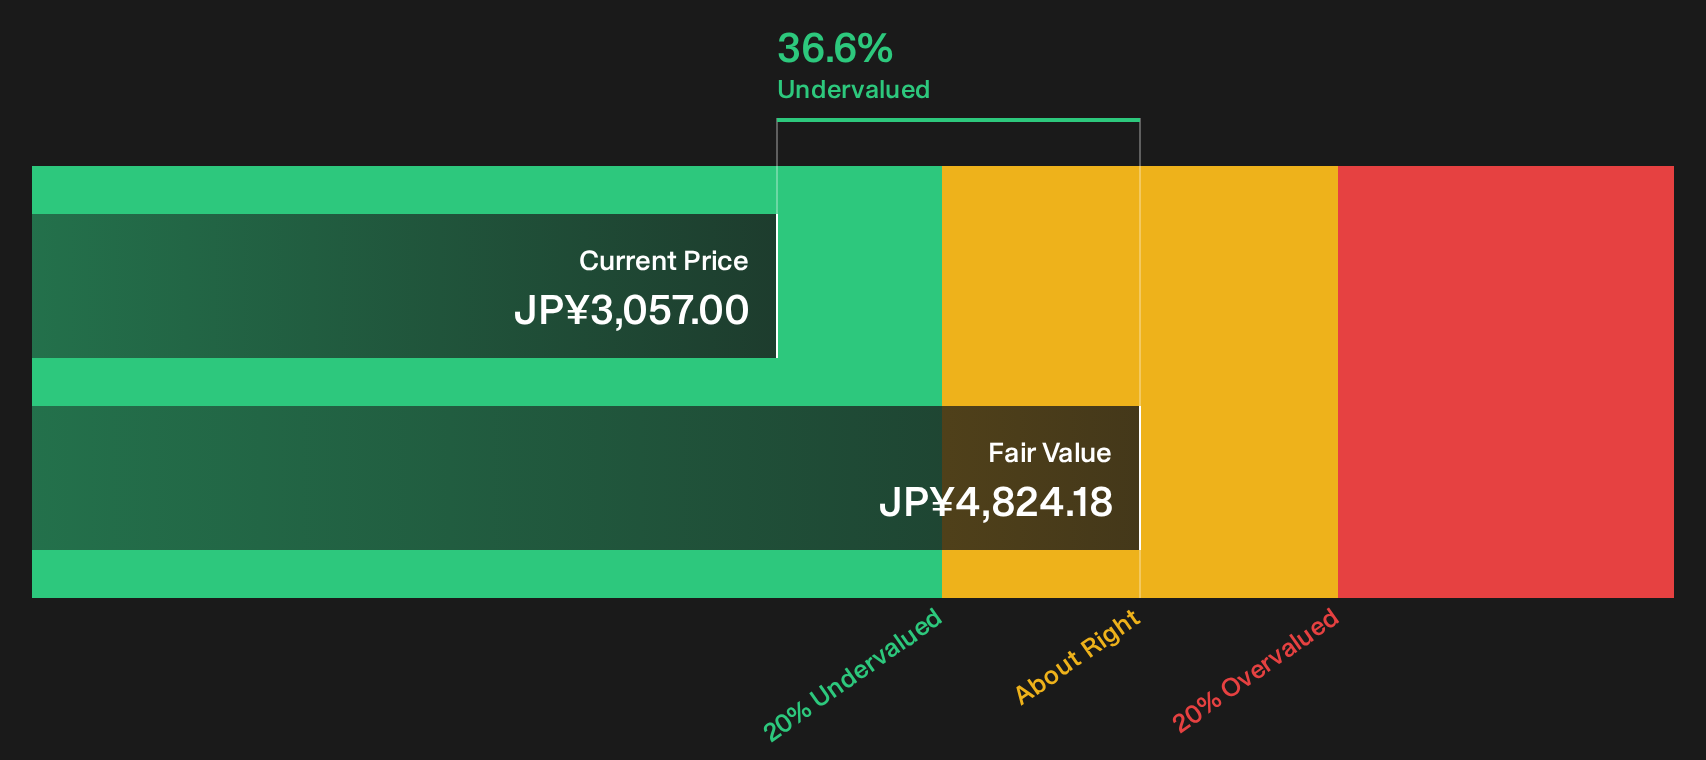
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Shizuoka Financial GroupInc for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 16 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Shizuoka Financial GroupInc can make the story feel murky, so it pays to move quickly and test the numbers yourself. To weigh the concern around risks against the potential upside from rewards, take a closer look at the 5 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Shizuoka Financial GroupInc?
Shizuoka Financial GroupInc might be front of mind today, but future returns often come from the ideas you almost skipped past.
- Target resilient balance sheets by scanning companies screened for strong financial foundations through the list of solid balance sheet and fundamentals (23 results).
- Hunt for potential mispricings by reviewing the curated 16 high quality undervalued stocks that could be overlooking improving fundamentals.
- Put reliable income streams on your radar by tracking businesses filtered as 29 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com