


World Bank forecasts of higher commodity prices in 2026 have put pricing power and leadership quality back in the spotlight for UK investors. When input costs and financing terms can shift, founders who still own a meaningful stake often treat every pound as if it is their own. This article highlights three founder-led UK stocks from our screener that show how that mindset can shape capital allocation and risk control.
The three stocks highlighted here offer a compelling starting point if you want exposure to founder led businesses where leadership is personally invested in long term outcomes. However, if you want the names that matter most, these 8 top founder-led companies are the strongest companies we've found.
Computacenter (LSE:CCC)
Overview: Computacenter is a founder-influenced IT services group that helps large organisations procure, run, and secure workplace, cloud, and managed infrastructure technology worldwide.
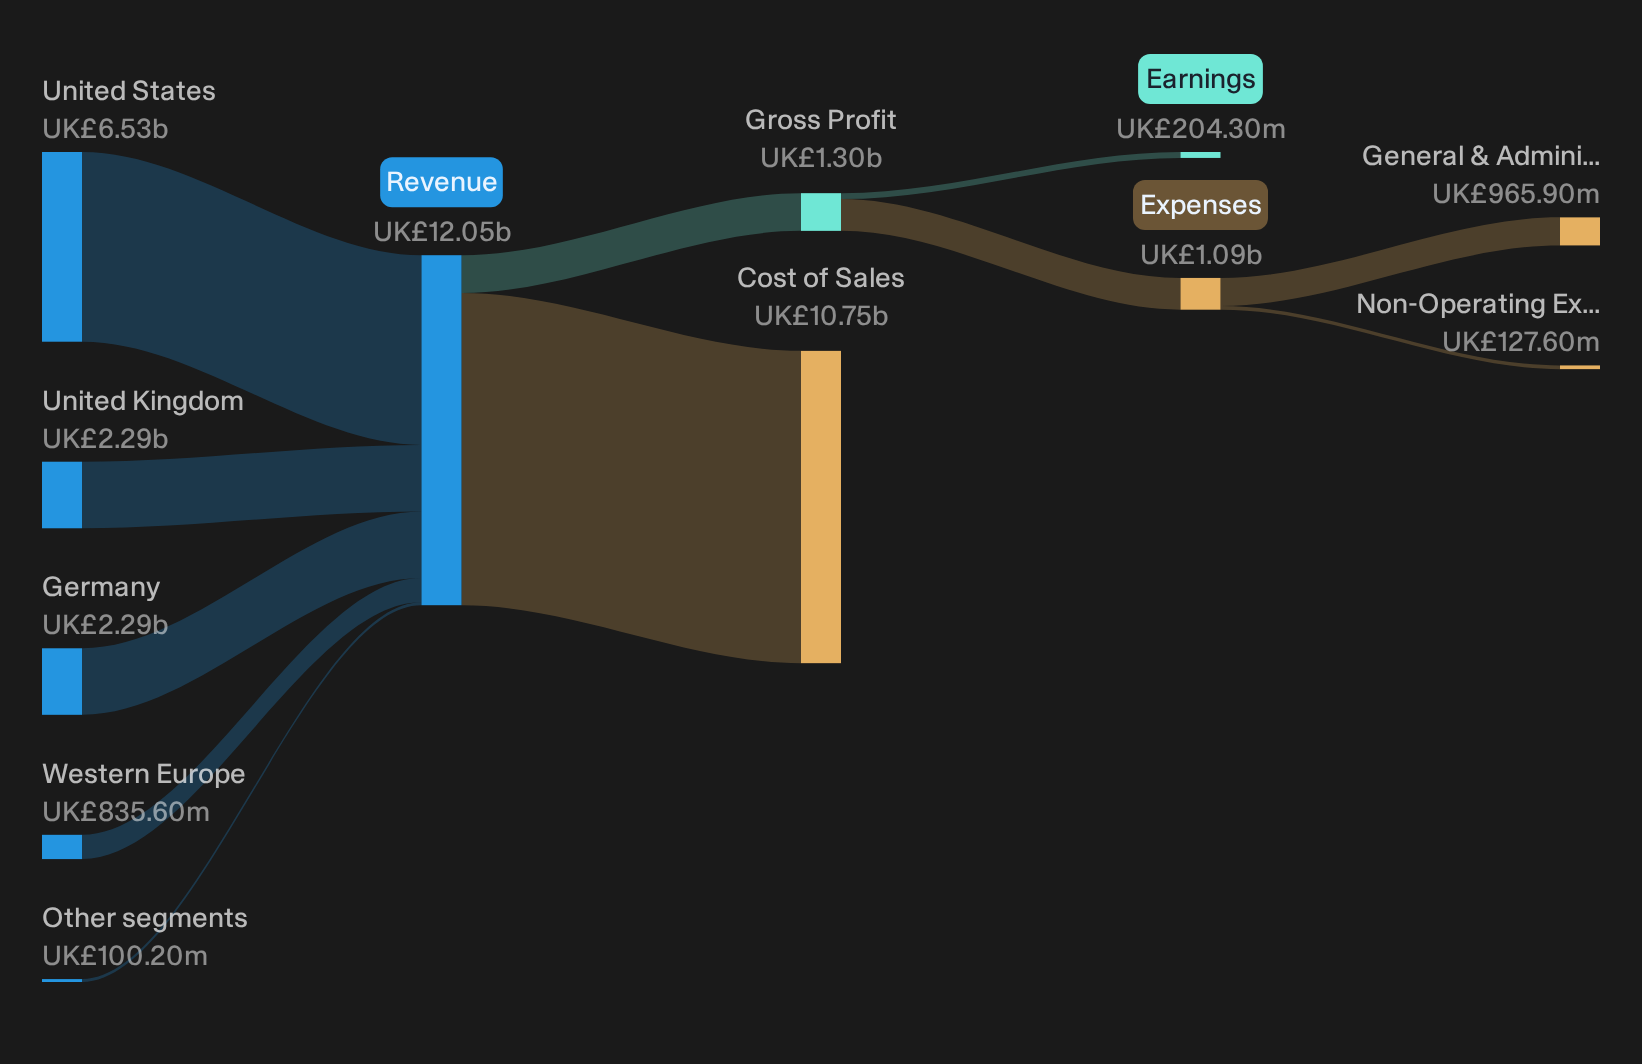
Operations: Computacenter generates £12.1b from Computer Services, with major contributions from the United States, the United Kingdom, Germany, and wider Western Europe.
Market Cap: £5.5b
Computacenter gives you a founder-legacy story with long-tenured leadership, high-quality earnings, and a 21.1% return on equity supported by a £12.6b product backlog tied to client relationships built over decades. That combination of stewardship and scale may be attractive for investors who are closely monitoring how pressures on margins and capital needs develop over time.
With that pressure on margins in mind, review the Computacenter financial health report to see what the balance sheet reveals about future flexibility.
W.A.G payment solutions (LSE:EWG)
Overview: W.A.G payment solutions runs founder-led digital payment and mobility platforms that help European commercial road fleets manage fuel, tolls, and fleet operations from one ecosystem.
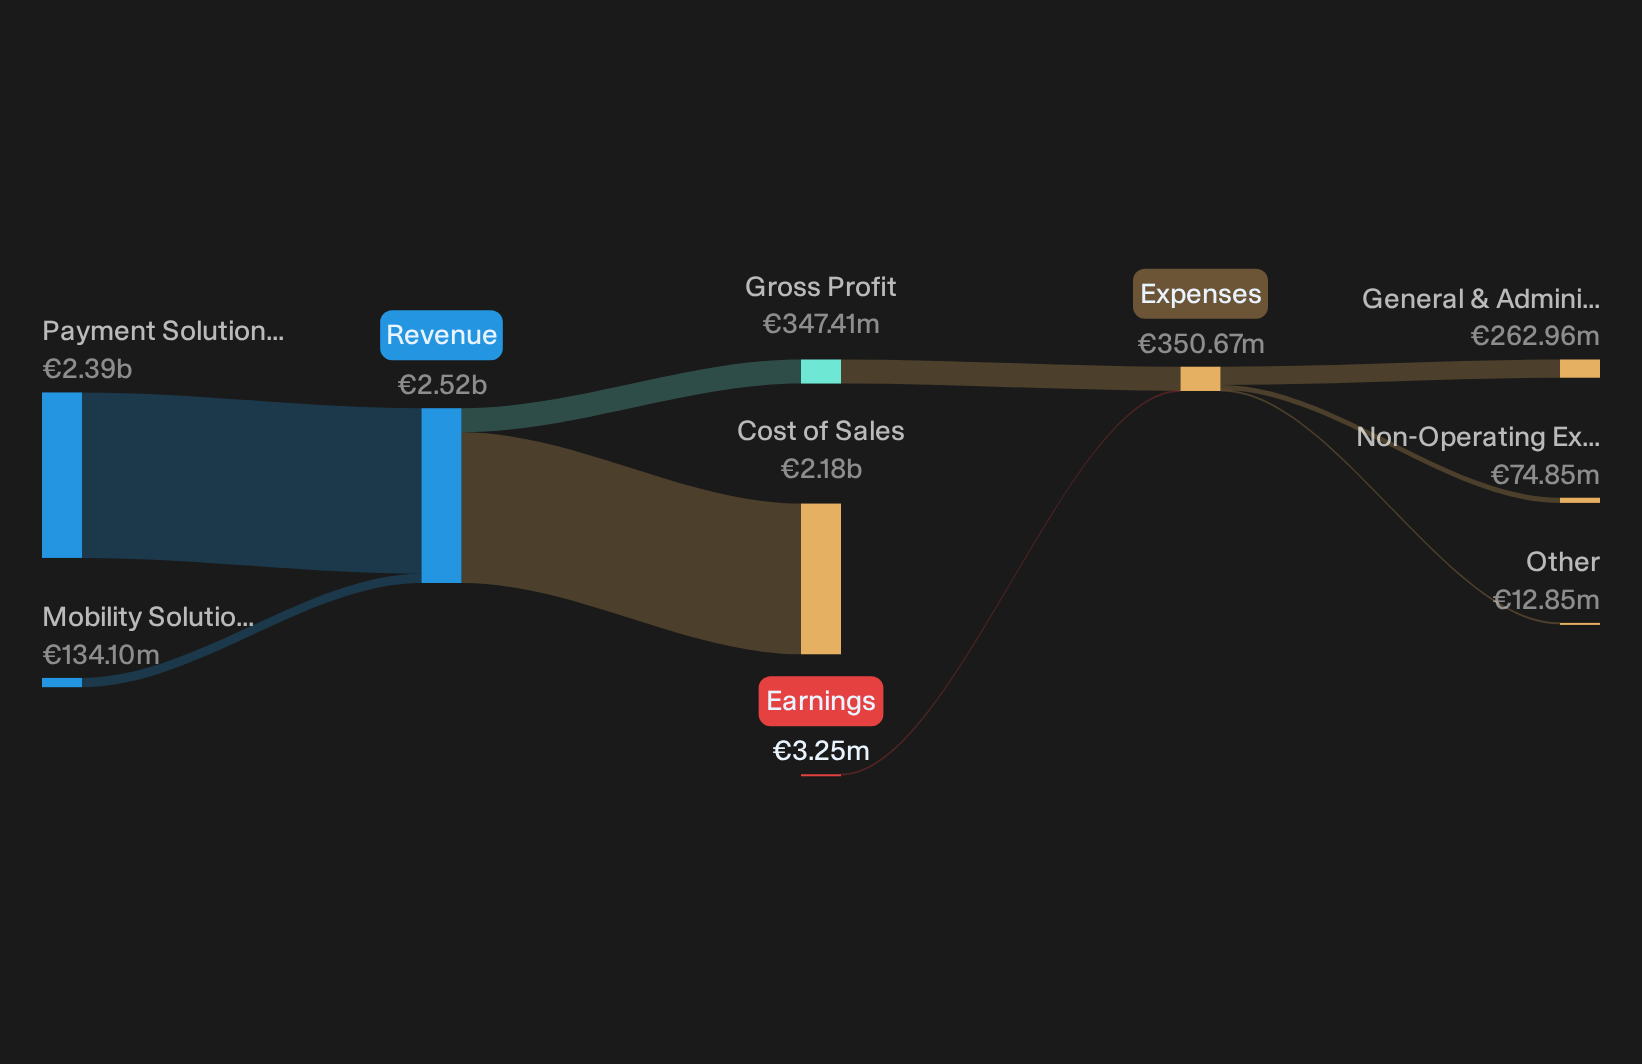
Operations: W.A.G payment solutions generates about €2.4b from Payment Solutions and €134 million from Mobility Solutions, across Central and Eastern European markets.
Market Cap: £748 million
Founder continuity matters here because W.A.G payment solutions is trying to build a long-lived payments and services ecosystem. Execution decisions may carry through for years, not quarters, and that ambition sits at the heart of why it fits a legacy-focused investing screen.
"Rollout of Eurowag Office as a unified, cloud based platform across fuel, toll, fleet management and financial services is designed to pull multiple revenue streams into a single ecosystem, which can support higher revenue per truck and more efficient EBITDA generation over time."
What happens to future profitability if one key assumption about how customers adopt that broader ecosystem shifts in either direction?
That adoption risk cuts both ways, and the full narrative for W.A.G payment solutions shows how Eurowag Office could accelerate monetisation, reshape customer stickiness, and surface underappreciated execution upside.
Foresight Group Holdings (LSE:FSG)
Overview: Foresight Group Holdings manages infrastructure and private equity funds with a focus on backing and scaling founder-led and manager-owned businesses.
Operations: Foresight Group Holdings generates about £114.8 million from Real Assets and £50.1 million from Private Equity, mostly sourced from the United Kingdom.
Market Cap: £520 million
Foresight Group Holdings taps directly into the Founder-Led Companies theme by supplying capital and long-term oversight to owner-managed businesses, which ties your returns to how effectively those founders turn patient support into durable compounding.
"Acceleration in real assets deployment into energy transition projects, supported by a near doubling of deployment in the most recent year and over £3.6b of identified future deployment rights in international mandates, gives Foresight Group Holdings room to turn existing pipelines into higher management fees and potentially stronger EBITDA growth as those commitments are drawn."
What happens to future fee margins if one quiet shift in how consistently new commitments refill that pipeline does not quite go to plan?
When that pipeline risk feels hard to price, reading the full narrative for Foresight Group Holdings shows how Foresight Group Holdings could turn contract timing swings into accelerating fee compounding.

Seeking Fresh Alternatives Before They Fly
Fresh ideas often move first. The strongest themes can see money rotate quickly, then momentum can build and early entry windows may narrow. Scan these under the radar lists now to explore potential opportunities early.
- Spot income workhorses paying meaningful yields and evaluate them with the curated 5 dividend fortresses before the next wave of yield-focused investors considers them.
- Track real-world automation demand by scanning curated 94 robotics and automation stocks that could be relevant as factories, warehouses, and logistics operators look for smarter hardware and software.
- Review the hand picked 42 power grid technology and infrastructure stocks for companies involved in energy and electrification upgrading while broader market focus continues to develop.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com