


Recent analyst updates around Quanta Services (PWR) have focused on higher earnings forecasts, supported by a large project backlog and management’s raised 2026 revenue and profit guidance.
At a recent share price of $578.83, Quanta Services has seen short term momentum soften, with a 30 day share price return down 10.83%, even though the year to date share price return is 31.65% and the 5 year total shareholder return is 383.28%. This suggests longer term enthusiasm has remained strong even as expectations around growth and risk are reassessed.
Scan for other infrastructure builders with similar momentum shifts by checking out our curated 42 power grid technology and infrastructure stocks as you continue your work on Quanta Services.
Quanta Services now trades after a steep multi year climb and a recent pullback, which raises a simple tension: Is most of the easy upside already captured, or are investors still underestimating what the current price implies?
Most Popular Narrative: 18% Undervalued
Quanta Services is trading at a last close of $578.83, while the most followed narrative on the stock pegs fair value at $710. That gap underpins a bullish long-term story built around grid buildout, data center power needs, and a deep project pipeline.
The long case is simple. Quanta sits at the intersection of several unusually durable spending waves: aging grid replacement, transmission expansion, utility hardening, manufacturing reshoring, renewable interconnection, and AI-driven power demand. The company’s scale, labor base, customer relationships, and expanding “total solutions” model make it one of the few contractors able to execute very large, complex programs.
See why 70 investors see Quanta Services as 18% undervalued.
According to HedgeY, this thesis leads to a narrative fair value of $710 per share, which is about 18.5% above the recent market price and treats Quanta Services as a premium infrastructure platform tied to long-duration power investment themes rather than a short-cycle contractor.
Result: Fair Value of $710 (UNDERVALUED)
Still, two pressure points could crack this Quanta Services narrative fast: a slowdown in new grid or data center awards, and any stumble on large project execution.
Find out about the key risks to this Quanta Services narrative.
Another View On Quanta Services: Paying Up For Quality?
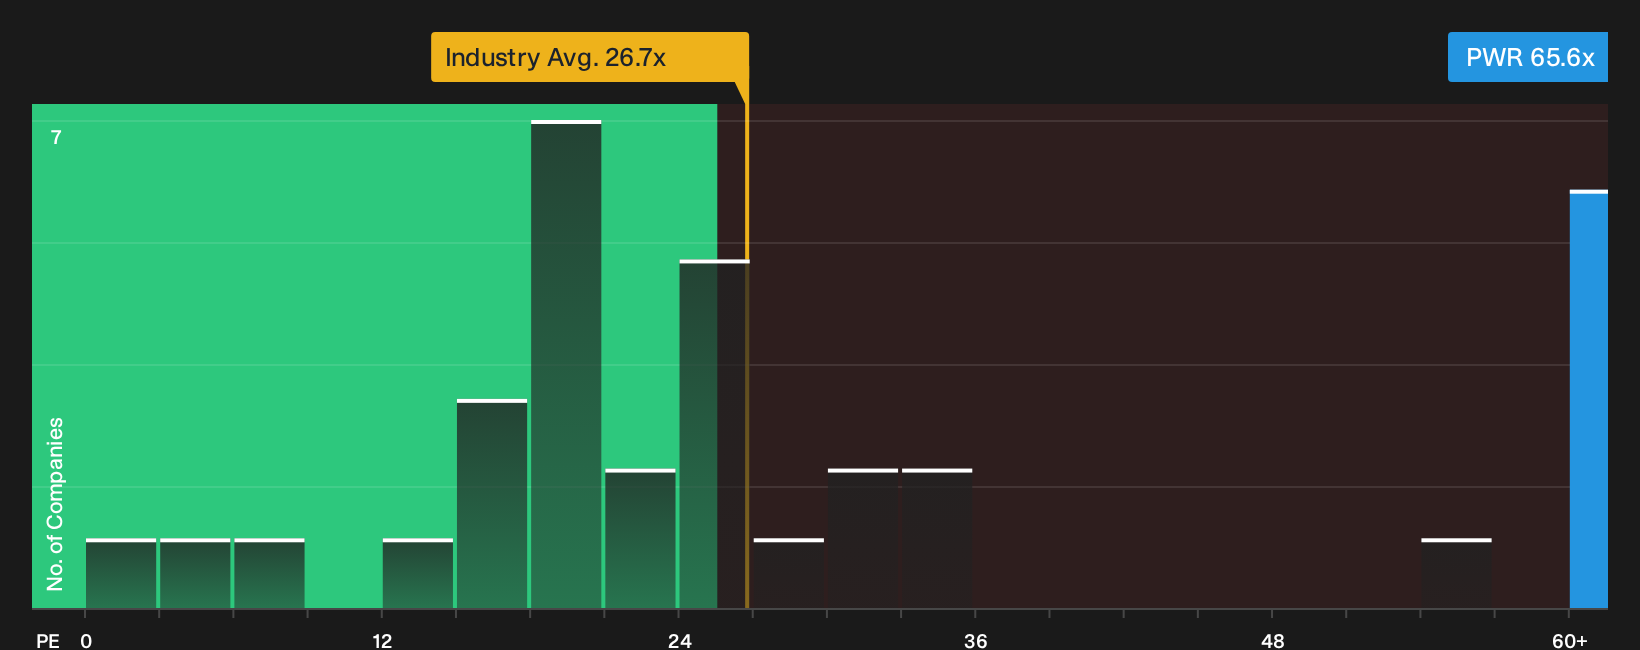
That 18% discount to narrative fair value clashes with what the market is already charging for Quanta Services. The P/E sits at 65.6x, which is far richer than the US Construction industry on 26.7x, peers at 25.6x, and even a fair ratio of 38.7x that the market could move toward.
If sentiment cools, a move closer to that fair ratio would mean a lot of valuation air coming out of the price. How comfortable are you paying this kind of premium for execution quality?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Quanta Services can either paralyse you or push you to look closer and move with intent. Pressure test the thesis from both angles by weighing 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Quanta Services?
If Quanta Services has sharpened your thinking on pricing, risk and quality, do not stop there. Broaden your watchlist with other focused opportunities.
- Target resilient, income-focused holdings by scanning companies in our 5 dividend fortresses that combine higher yields with an emphasis on durability.
- Hunt for quality at a discount by reviewing the 29 high quality undervalued stocks, where stronger fundamentals meet more modest pricing.
- Prioritise capital protection first by working through a 30 resilient stocks with low risk scores that filters for sturdier balance sheets and lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com