


Ensign Group guidance hike and what it means for investors
Ensign Group (ENSG) raised its 2026 earnings outlook after reporting third quarter results that outpaced earlier expectations, putting fresh attention on how the stock reflects the company’s updated profit and revenue targets.
Despite the stronger third quarter and higher 2026 guidance, Ensign Group’s recent trading has been soft, with the share price down about 4% over the last day and posting a 30 day share price return decline of 3.24%. Over a longer stretch, total shareholder return has fallen 8.56% over the past year. However, the 3 year total shareholder return of 76.37% and 5 year total shareholder return of 125.99% point to a much stronger multi year story, where current weakness may reflect a reset in expectations and risk appetite rather than a break in the broader trend.
Scan how Ensign Group’s guidance reset compares with other healthcare operators by reviewing our hand picked list of solid balance sheet and fundamentals (24 results) as potential watchlist candidates.
Ensign Group is trading below both its intrinsic value estimate and the average analyst target after raising 2026 guidance. Is that a straightforward discount, or is the market pricing in real execution risk around those higher goals?
Most Popular Narrative: 23% Undervalued
Ensign Group last closed at $169.50, while the most followed narrative anchors fair value around $220, using a 7.2% discount rate and detailed earnings assumptions to bridge that gap.
A sizeable pipeline of low occupancy, clinically challenged acquisitions, particularly in Texas, creates room for operational turnaround using the existing cluster and ONE CLINICAL model, which can affect occupancy driven revenue and EBIT over multi year periods.
See why 1 investors see Ensign Group as 23% undervalued.
Result: Fair Value of $220 (UNDERVALUED)
Still, this Ensign Group narrative depends heavily on stable Medicare and Medicaid funding, as well as recently acquired low occupancy facilities improving on schedule, both of which could undermine the thesis.
Find out about the key risks to this Ensign Group narrative.
Another View on Ensign Group valuation
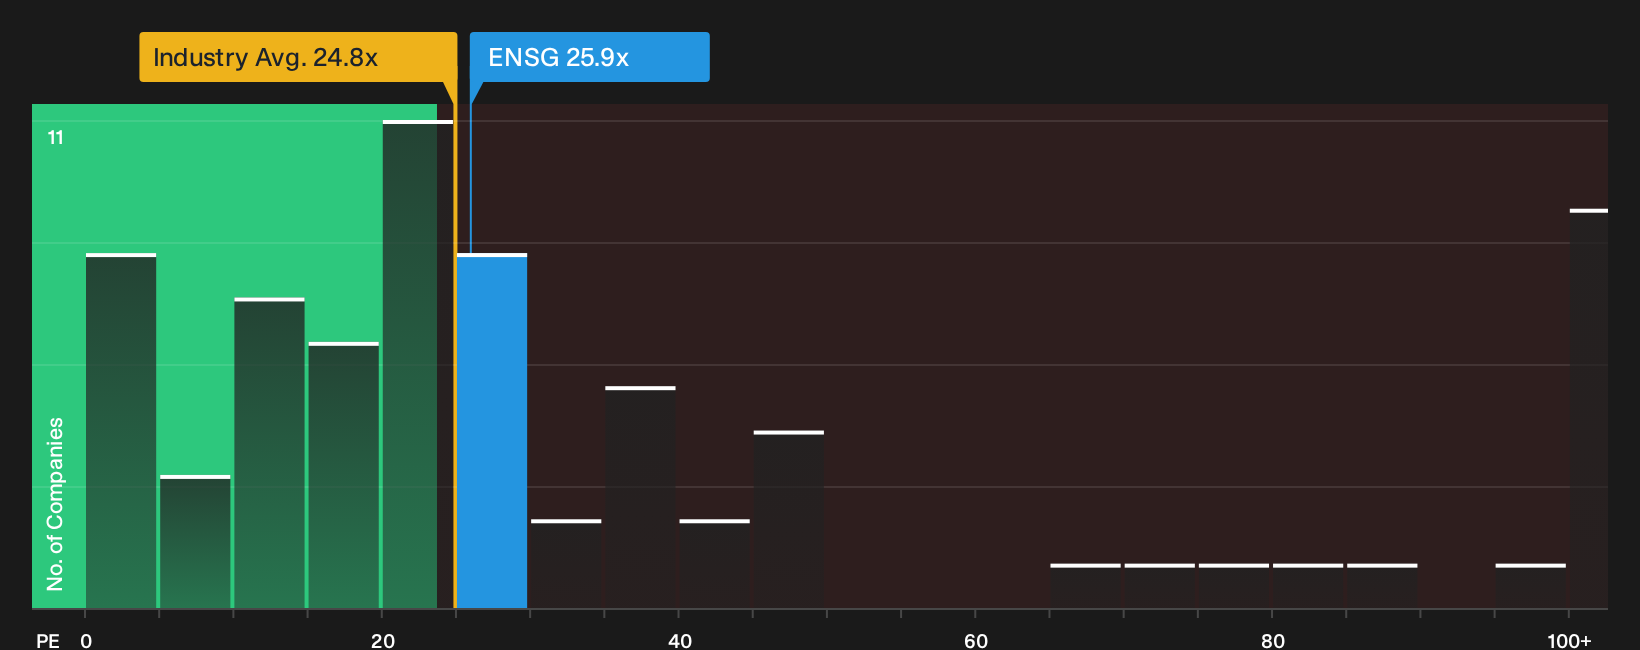
The story looks different when you step away from fair value estimates and focus on what the current P/E implies. Ensign Group trades at 25.9x earnings, only slightly above its fair ratio of 25.8x, and also sits higher than both the US Healthcare industry at 25.6x and peers at 19.6x. That points to limited cushion if sentiment cools, so how comfortable are you paying up for this quality of earnings?
See what the numbers say about this price in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Ensign Group is mixed on the surface, yet the underlying data tell a richer story that deserves your own fresh look. To see what investors are optimistic about and to pressure test your thesis against the underlying metrics, review the 4 key rewards.
Looking for more Ensign Group style investment ideas?
If you stop with Ensign Group, you risk missing other opportunities that align with your risk profile and return goals across different corners of the market.
- Target resilient compounding potential by reviewing a curated 29 high quality undervalued stocks that combine quality fundamentals with prices that sit below their estimated worth.
- Strengthen income potential and cash flow stability by scanning 5 dividend fortresses designed for investors who want yield plus financial robustness.
- Prioritise capital protection by focusing on 30 resilient stocks with low risk scores so you concentrate on companies with sturdier balance sheets and lower quantified risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com