


GEO Group (GEO) has retired all of its $650 million 8.625% Senior Secured Notes due 2029 and extended its $550 million revolving credit facility, moves that reshape the company’s balance sheet and capital return flexibility.
Recent trading shows that momentum in GEO Group has cooled in the short term, with the 30 day share price return down 9.45% and the 90 day move down 5.61%. At the same time, the year to date share price return is 77.46% and the 5 year total shareholder return is 232.59%, which keeps longer term performance firmly in positive territory. This frames the latest debt redemption and expanded buyback capacity as a possible reset in how investors assess the stock’s risk and capital return profile at a last close of $28.27.
Capitalize on GEO Group’s balance sheet reset by comparing it with other companies screened for stronger fundamentals and lower risk profiles in our 30 resilient stocks with low risk scores.After GEO Group’s debt clean up and expanded buyback firepower, the question now is simple: Does the current valuation still compensate you for the remaining risk, or has most of the easy upside already been claimed?
Most Popular Narrative: 25.1% Undervalued
On the most followed view, GEO Group screens as undervalued, with a fair value of $37.75 against the last close at $28.27. This puts debt reduction, idle beds and contract execution in the spotlight for anyone weighing what the current price already reflects.
The federal funding package that provides ICE with multi year access to US$45b for detention expenditures and US$38.5b of broader funding is supporting ICE plans to increase total detention capacity toward 100,000 or more beds. This could allow GEO Group to activate additional contracted and idle facilities and lift revenue and adjusted EBITDA if its share of beds continues to rise.
See why 29 investors see GEO Group as 25% undervalued.
Result: Fair Value of $37.75 (UNDERVALUED)
Still, the GEO Group narrative can unravel quickly if ICE detention funding is reduced, or if political and legal scrutiny starts to constrain contract renewals.
Find out about the key risks to this GEO Group narrative.
Another View: GEO Group Through The P/E Lens
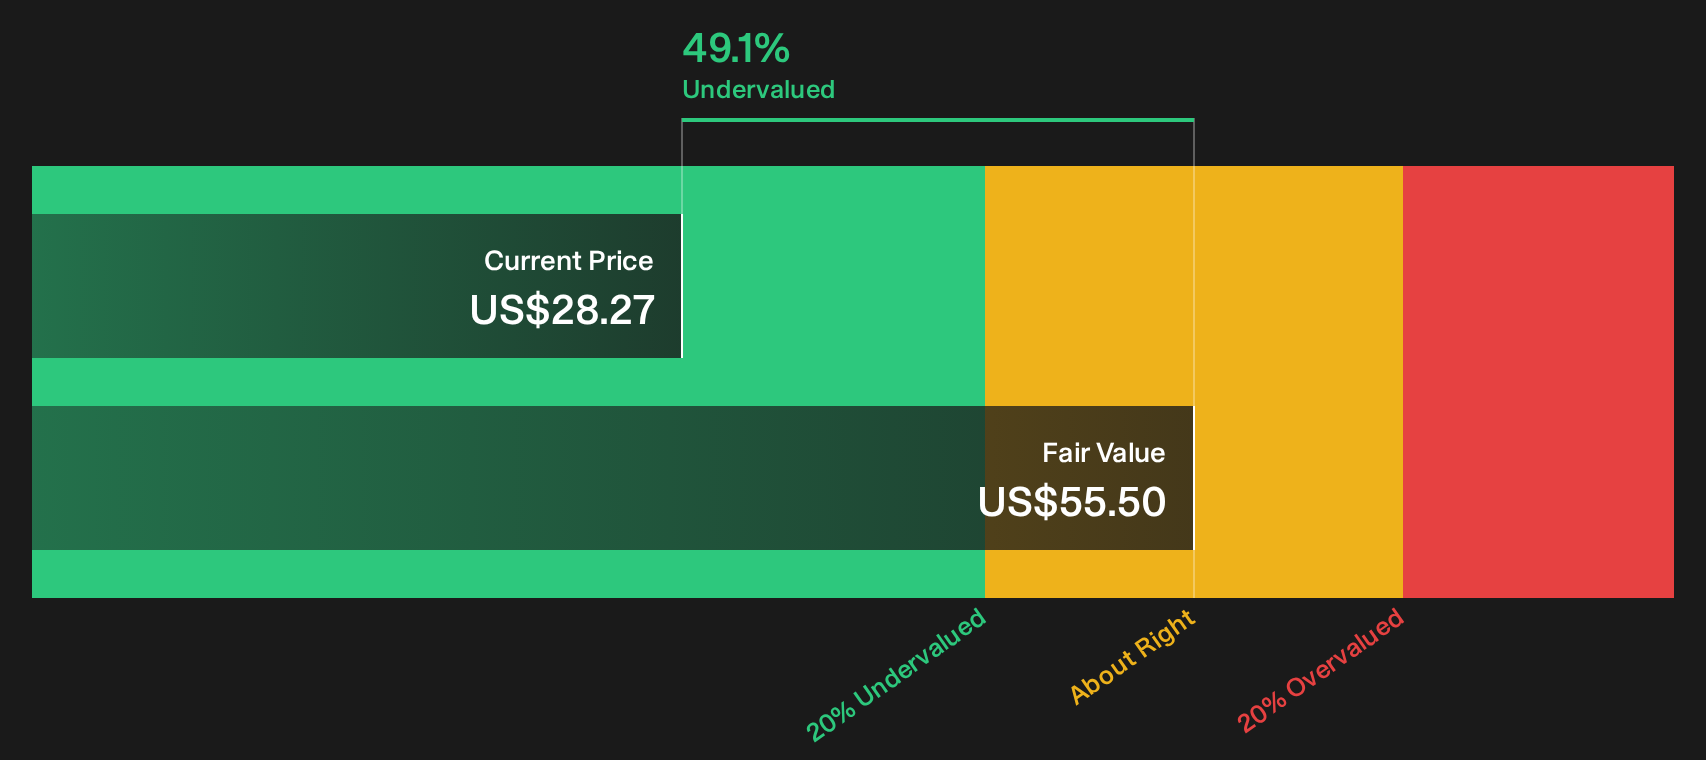
The SWS DCF model points to GEO Group trading 49.1% below an estimated future cash flow value of $55.50, which supports the idea that the market may be pricing in heavy risk around earnings staying low. If cash generation holds up better than forecast, is sentiment simply too far behind the numbers?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Sentiment on GEO Group is split, which is exactly when fresh eyes can matter most. Move quickly and weigh the 3 key rewards and 4 important warning signs.
Looking for more GEO Group sized investment ideas?
GEO Group is only one way to put a thesis to work, and you risk missing stronger setups if you do not scan across other opportunities right now.
- Target potential mispricings by scanning a curated pool of companies that combine quality fundamentals with attractive valuations through our 29 high quality undervalued stocks.
- Strengthen portfolio resilience by focusing on businesses that pair solid cash positions with prudent leverage in the list of solid balance sheet and fundamentals (24 results).
- Hunt for fresh opportunities off the beaten path by filtering for overlooked quality stories using the 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com