


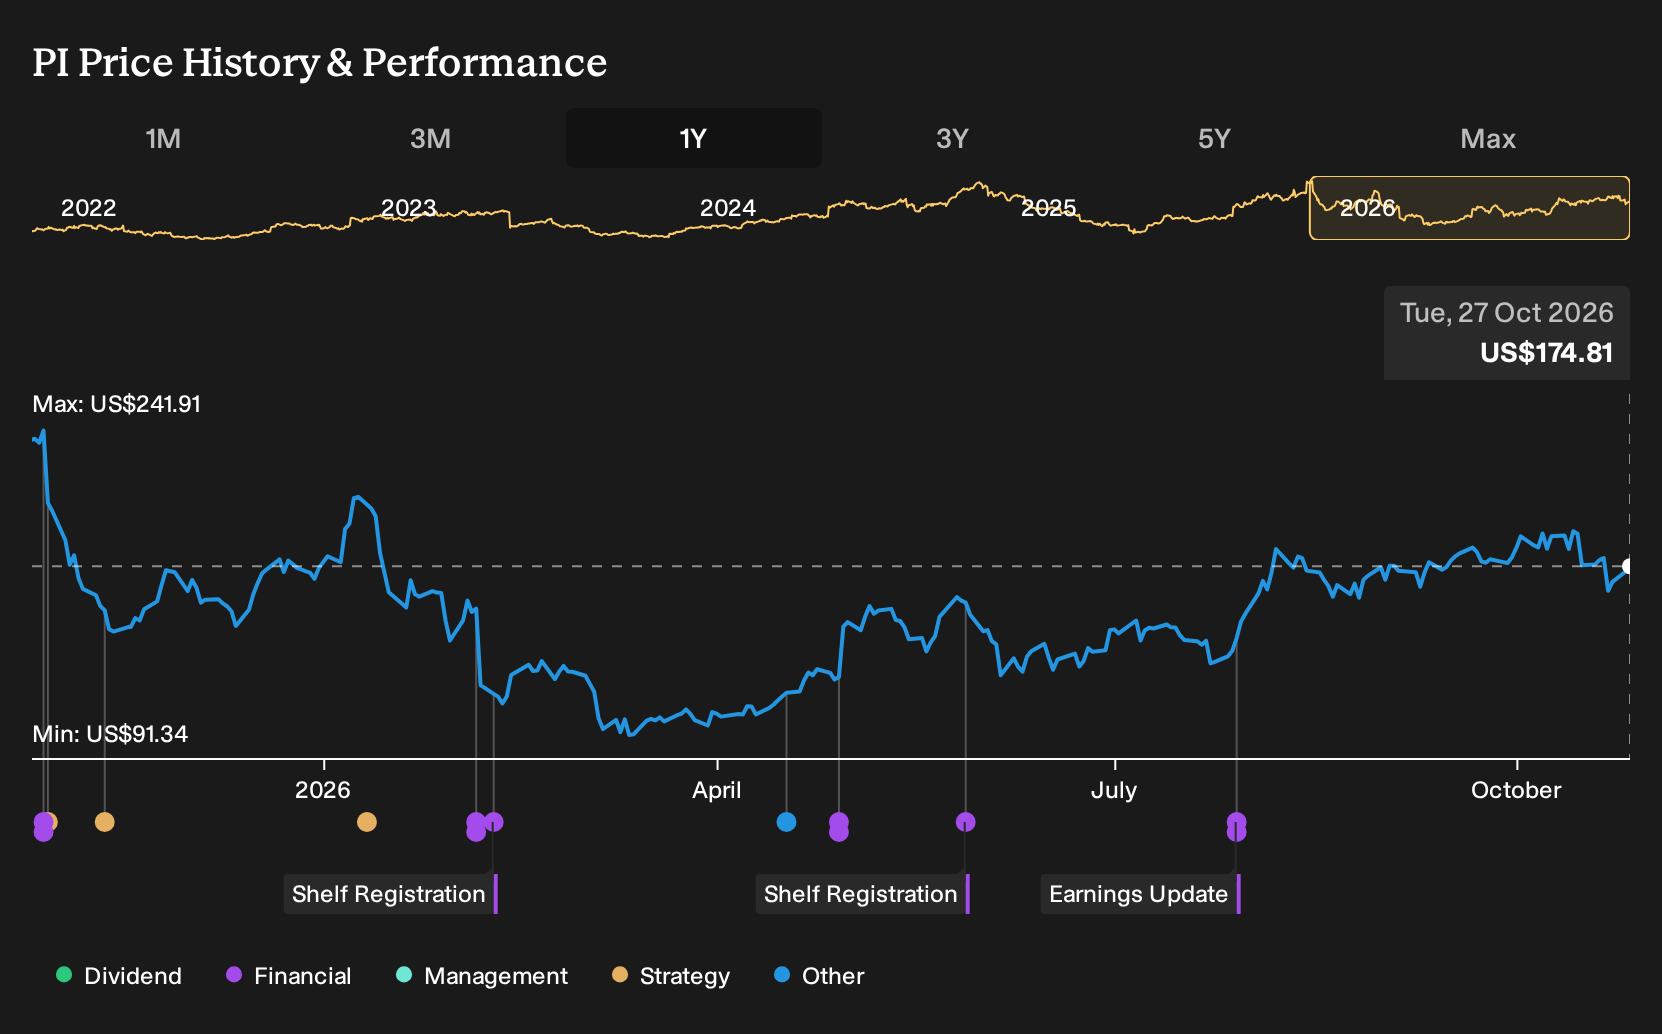
- Impinj is set to report earnings after the market close this Wednesday, with analysts expecting revenue to be 11.7% higher than the same quarter last year and pointing to earlier progress on inventory levels.
- The combination of prior revenue outperformance and cleaner inventory positioning adds extra focus on how effectively Impinj is converting demand into more predictable operations this quarter.
- We will examine how Impinj’s broader investment narrative is influenced by the upcoming earnings report and its expected 11.7% revenue growth.
Impinj Investment Narrative Recap
To own Impinj, you need confidence that RAIN RFID adoption across retail, logistics and food keeps pulling more endpoint IC units through its platform, and that this eventually supports steadier profitability. The immediate swing factor is how clean demand signals look this quarter after past channel inventory issues, because that directly affects how predictable orders feel.
The biggest operational risk in the near term is another surprise from large logistics customers if inventory visibility still falls short. This week’s earnings update matters mainly for what it indicates about order quality, gross margin mix from M800 and systems, and whether recent revenue expectations look sustainable or need a reset.
Recent commentary around record free cash flow of US$29.2 million in Q2 2026, a cash balance of US$263.7 million and the effective retirement of almost all 1.125% convertible notes due 2027 is highly relevant here. A cleaner balance sheet gives Impinj more room to absorb lumpier quarters while still funding R&D and partner efforts.
For you as an investor, that financial flexibility links directly to the current catalyst and risk mix. If the business can keep strengthening its cash generation while tightening execution around demand forecasting and channel inventory, the upcoming print becomes less about survival and more about how quickly RFID deployments might relate to consistent earnings over time.
Impinj's current analyst narrative points to US$659.4 million in revenue and US$85.9 million in earnings by 2029. That profile is built on forecast revenue growth of 21.1% per year and an earnings swing of US$112.9 million from a loss of US$27.0 million today.
Uncover how Impinj's fair value indicates a 3% potential upside to its current price before that discount to sentiment closes.
Exploring Other Perspectives
One alternate angle on Impinj focuses less on unit growth and more on what you actually pay for those earnings. The most cautious analysts were penciling in 2029 revenue of about US$605.1 million and earnings of US$59.5 million, yet still using a triple digit P/E. Their view is that if Wednesday’s report challenges those assumptions in either direction, the whole narrative could shift. That spread in expectations is exactly why you should compare several viewpoints before deciding how this setup fits your own risk tolerance.
Explore 2 other Impinj fair value estimates, including one that suggests as much as 99% downside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Impinj research is our analysis highlighting 1 key reward that could impact your investment decision.
- See our latest analysis for Impinj. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Impinj's overall financial health at a glance.
Looking For More Investment Ideas Beyond Impinj?
If the Impinj setup has you thinking about position sizing and diversification, it can help to line it up against a few carefully filtered opportunities that fit different risk profiles and income goals.
- For investors who want lower drama around business quality, start by scanning a 30 resilient stocks with low risk scores that screens for more measured balance sheets and earnings profiles.
- If your focus is long term value, weigh Impinj against a 29 high quality undervalued stocks that flags companies with strong fundamentals trading on more modest expectations.
- Income minded investors who still care about financial resilience can review a 5 dividend fortresses that highlights payout strength alongside business stability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com