


Roblox (RBLX) has built a virtual playground where millions of people can play games, create their own experiences, and hang out with friends. But lately, the fun has not exactly translated into a happy ride for investors. While the platform continues to attract users, its stock has struggled as Wall Street questions whether that engagement is translating into more spending.
Now, Roblox investors have another important date to circle on their calendars. The company is set to report its third-quarter 2026 financial results after the market closes on Thursday, Oct. 29. Roblox has beaten Wall Street’s EPS estimates for four straight quarters, but its revenue track record is more mixed, with two beats and two misses over the same period. This time, analysts expect a tougher quarter, forecasting year-over-year (YoY) declines in both revenue and earnings.
Roblox has faced pressure from child safety concerns, a lawsuit in Los Angeles County, Wall Street downgrades, and weaker per-player spending. Earlier this year, its mandatory age-check requirements also slowed new user acquisition, prompting management to lower its full-year revenue growth outlook. By July, executives declined to provide updated full-year guidance.
Still, the bull case is not over. Roblox’s growing daily user base, AI-powered creation tools, and new discovery features could eventually help improve engagement and spending. The catch is that the improvement has not fully shown up in bookings yet.
Thursday’s report could offer investors a clearer picture of whether Roblox can turn its growing audience into stronger financial results. So, before the numbers drop, let’s take a closer look at how Roblox stock has performed so far and what’s awaiting investors next.
About Roblox Stock
Headquartered in San Mateo, California, Roblox Corporation is a technology and gaming company that operates an online platform where users can play games, explore virtual worlds, and connect with others. Founded in 2004, the company also gives creators the tools to design and publish their own multiplayer experiences through Roblox Studio, supported by Roblox Cloud’s underlying infrastructure and services. Its business thrives on a global community of millions of developers who create content that keeps users engaged.
Roblox aims to build a shared digital space where billions of people can play, learn, communicate, explore, and form friendships. Its popularity among younger audiences has made it a major player in online entertainment. Roblox has a market capitalization of approximately $36.4 billion.
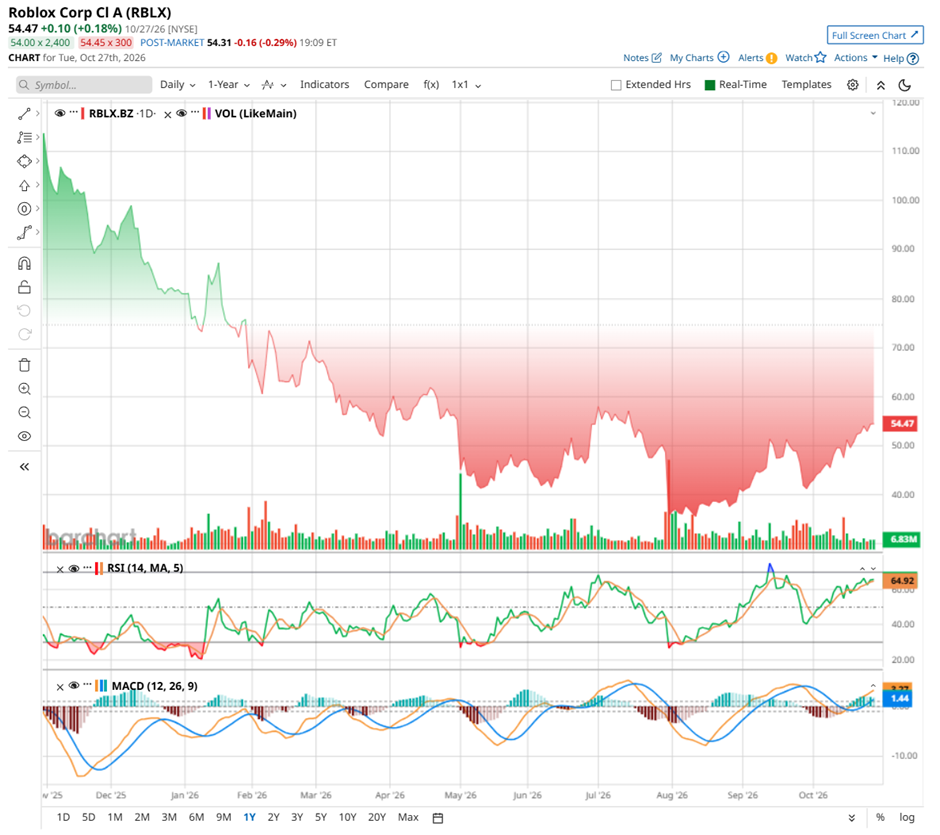
But while Roblox has built a popular platform for gamers and creators, its stock performance has been a much bumpier ride. RBLX has fallen 59% over the past 52 weeks and 33% on a year-to-date (YTD) basis as investors reassess whether its growing audience can translate into stronger financial results. The shares are also down nearly 60% from last year’s high of $134.67.
Much of that pressure intensified after Roblox reported its second-quarter results, which exposed weaker monetization and a disappointing bookings outlook, raising concerns about spending per player, and investors wasted little time reacting, sending RBLX stock plunging 26.9% on July 31.
The earnings disappointment wasn’t Roblox’s only headache. As mentioned earlier, child safety concerns, a lawsuit in Los Angeles County, analyst downgrades, and slower user acquisition following mandatory age checks have added to the pressure. Management had already lowered its full-year revenue growth outlook earlier in the year and declined to provide updated full-year guidance in July.
That said, the stock has not moved in just one direction. After hitting a 52-week low of $33.88 on July 31 after Q2 numbers, RBLX staged a strong rebound, climbing 61% from that level. Shares gained 10% over three months, advanced 31% over the past month, and rose nearly 4% over the latest five trading sessions.
However, that recovery has faced fresh hurdles. On Sept. 28, RBLX fell 9.9% after Jefferies downgraded the stock, arguing that the post-earnings rally had priced in overly optimistic expectations for bookings recovery.
Now, with its next earnings report approaching, investors will be watching closely to see whether Roblox can justify that rebound or whether monetization concerns will continue to weigh on the stock.
Despite the stock’s broader struggles, technical indicators suggest some bullish momentum is building. RBLX’s 14-day RSI stands at around 65.8, cooling from September’s overbought levels but still showing strength. Meanwhile, the MACD line has crossed above its signal line, and the positive histogram adds to the bullish signals.
Valuation-wise, Roblox stock isn’t exactly cheap. RBLX trades at 5.63 times forward sales and 30.68 times forward cash flow, both above the sector average. That premium may be difficult to justify while monetization remains under pressure. However, the stock is still trading below its historical median, suggesting its valuation has cooled from past levels.
A Closer Look at Roblox’s Mixed Q2 Numbers
Roblox’s second-quarter 2026 results offered a mixed picture. The gaming platform is still attracting millions of players, but getting them to spend more money has become a different challenge. That gap between user growth and monetization is now harder to ignore.
On July 30, Roblox reported that revenue jumped 36% year-over-year (YoY) to $1.5 billion. Bookings, however, grew just 8% annually to $1.6 billion, landing at the lower end of management’s guidance. The main culprit was a lower monetization per hour, particularly among younger users in the U.S. and Canada. In simple terms, people were spending more time on Roblox, but that time wasn’t generating as much money as the company had expected.
User engagement itself remained healthy. Daily active users (DAUs) climbed 10% YoY to 123 million, while total hours engaged increased 5% to 29 billion. Roblox also attracted older audiences, with U.S. users aged 18 and above rising 32% and their hours engaged increasing 27%. Meanwhile, the platform’s return to Russia in June provided a modest sequential boost, although the earlier disruption continued to weigh on annual user and engagement growth.
Meanwhile, Roblox narrowed its net loss to -$185 million from -$280 million a year earlier, while loss per share shrank 36.6% YoY to -$0.26. Adjusted EBITDA surged to $152 million from just $18 million, while operating cash flow rose 60% to $318 million. Free cash flow also climbed 66% to $294 million.
Players were moving away from viral games released in 2025, which generated higher spending, toward newer and evergreen titles that monetize less per hour. Its updated Recommended for You algorithm also prioritizes games that keep users coming back, even if that means sacrificing some near-term revenue.
Unfortunately, Roblox expects this pressure to continue in the near term. For Q3 2026, management forecasts revenue to be between $1.41 billion and $1.49 billion, implying 4% to 10% YoY growth, but bookings could fall 14% to 18% and be somewhere between $1.576 billion and $1.653 billion. The company also expects a net loss of $307 million to $348 million and adjusted EBITDA ranging from zero to $41 million.
Meanwhile, analysts tracking the company expect Roblox to report Q3 revenue of $1.62 billion, alongside a loss of -$0.41 per share. Looking further ahead, analysts project its fiscal 2026 loss to narrow 8.4% YoY to -$1.41 per share. The improvement is expected to continue into fiscal 2027, with the projected loss shrinking another 6.4% to -$1.32 per share.
What Do Analysts Expect for RBLX Stock?
Ahead of Roblox’s upcoming earnings report, analysts remain divided on how quickly the company can overcome its monetization challenges. Nick McKay of Freedom Capital Markets maintained a “Buy” rating on RBLX stock, keeping his price target unchanged at $55.
Meanwhile, Wedbush analyst Alicia Reese raised the price target to $55 from $48 but retained a “Neutral” rating. Wedbush believes Roblox’s user engagement has held up better than expected, although spending per user likely remains under pressure. The brokerage’s more optimistic price target hinges on a recovery in the second half of 2027, which has yet to materialize.
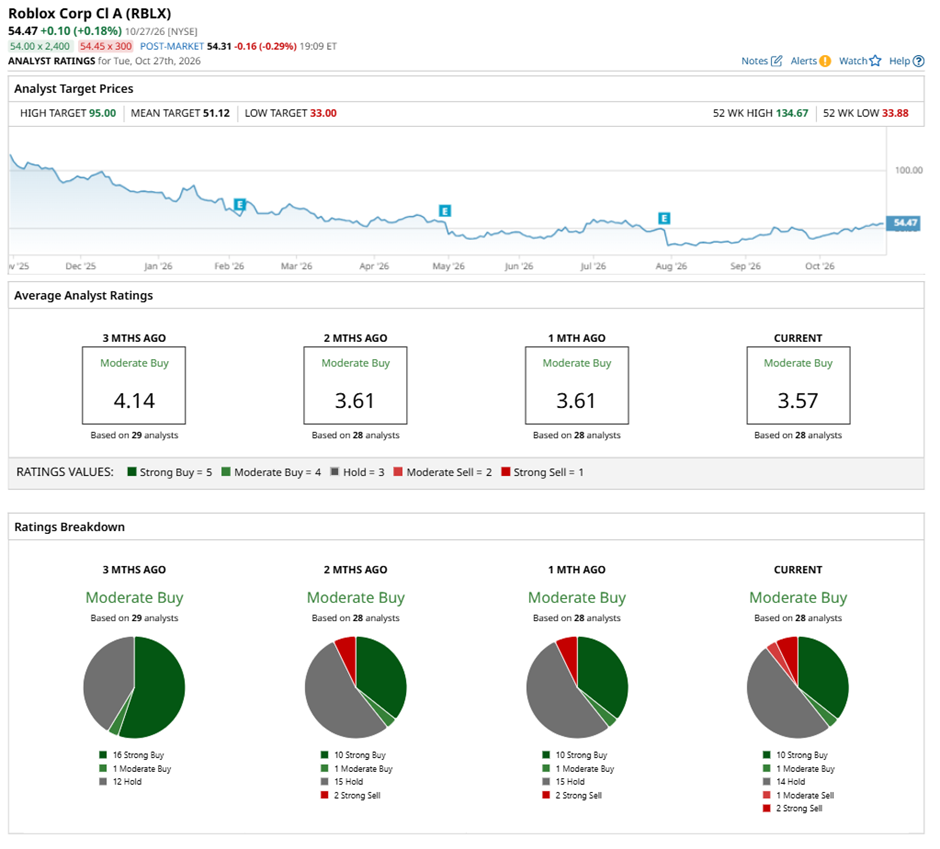
Overall, RBLX stock has a consensus “Moderate Buy” rating. Out of 28 analysts covering it, 10 are extremely optimistic, recommending a “Strong Buy”; one suggests a “Moderate Buy”; 14 are cautious with a “Hold” rating; one advises a “Moderate Sell,” and two give a “Strong Sell.”
RBLX stock already sits above the average analyst price target of $51.12, while the Street-high target price of $95 suggests the stock could rally as much as 74.4% from current price levels.
On the date of publication, Sristi Suman Jayaswal did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.